
Is United States Antimony (UAMY) Priced Too Richly On Sales?
United States Antimony has delivered a very large 3 year share price gain, even though the stock has fallen sharply over the past year. As a result, investors are now asking whether the current valuation can still be explained by its sales. With fresh government related contracts and new mining activity in the spotlight, the key issue is how the recent share price level lines up against what the business is generating in revenue.
- Over the last 3 years the share price has risen by a very large amount. This puts a lot of weight on whether the underlying sales base can support that move.
- Recent contracts linked to antimony supply and gold antimony exploration activity can influence future revenue visibility and may support a higher level of sales over time.
- Your read on United States Antimony is one view; the desks covering it have another. See what analysts think United States Antimony's shares could be worth.
The issue now is whether the current price for United States Antimony is justified by the revenue the company is producing today and the sales investors are effectively paying for.
If you want to pressure test United States Antimony's valuation question against a broader set of metals and mining ideas, line it up next to the 33 best rare earth metal stocks.
Does United States Antimony Look Pricey on Sales?
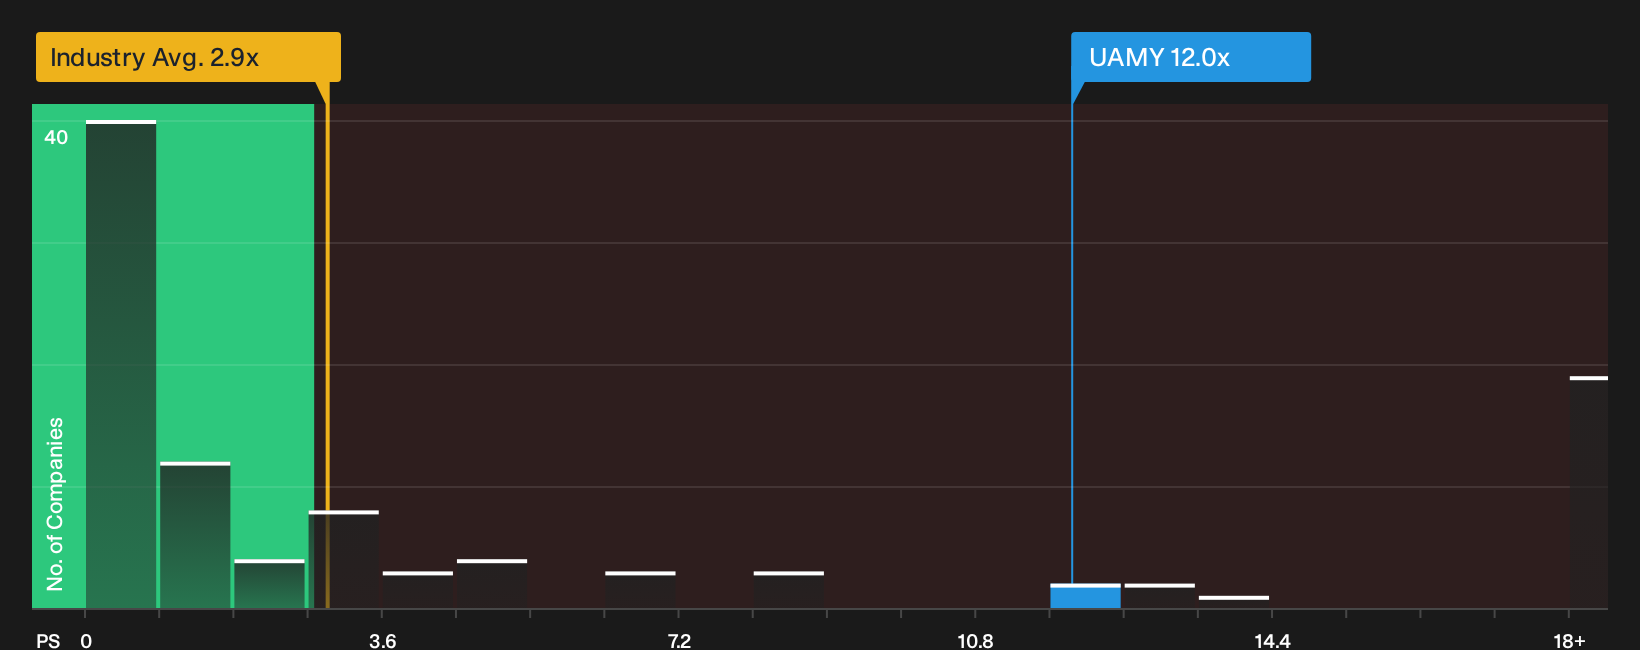
P/S is a useful lens for United States Antimony because investors are currently focused on revenue potential from contracts and new mining activity rather than current profits. The stock trades on a P/S of 12.0x, compared with a Metals and Mining industry average of about 2.9x and a peer group around 3.8x, so buyers today are paying a much higher price for each dollar of sales than is typical for the sector.
Because the fair P/S benchmark from the model sits far below the current level, it suggests the framework is heavily penalising United States Antimony for its loss profile and perceived execution risk rather than offering a precise target. Despite the recent Defense Logistics Agency contract activity and gold antimony bulk sample plans bringing more attention to the story, the valuation still screens as overvalued on this revenue multiple relative to what similar businesses trade on. Explore the numbers behind United States Antimony's P/S valuation.
The United States Antimony Narrative: What Would Justify Today's Price?
Narratives for United States Antimony pick up where the P/S puzzle leaves off and explain what kind of future path for growth, margins and earnings would need to occur for the share price to settle much higher or much lower than today. Instead of a single ratio or model output, they lay out the underlying story those figures rely on so you can watch how the real world lines up with that scenario over time on Simply Wall St's Community page.
One of the top narratives on United States Antimony: 73% undervalued
This Narrative is the analyst consensus Narrative on Simply Wall St, which compiles analysts' consensus price target and revenue and earnings forecasts, not one person's view.
"The main thing that has to go right is that United States Antimony turns its expanded mining, milling, smelting, and zeolite operations, along with government- and grant-backed projects, into consistently profitable and cash-generative volumes..."
Discover why this Narrative puts United States Antimony at 73% undervalued.
For United States Antimony, one last check sits outside the price tag
Valuation only tells part of the story for United States Antimony, since the broader review has already highlighted specific business concerns that deserve your attention before you lean on any single metric. Take a closer look at 2 warning signs before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com