
CONMED (CNMD) Stock May Still Be A Bargain On Earnings
CONMED has climbed back into focus after a mixed stretch, and the question now is whether the current US$50.48 share price is adequately supported by the earnings power of the business. For investors who care about what they are paying for each dollar of profit, the key issue is whether the recent rebound lines up with what the income statement can reasonably carry.
- Over the past 5 years the stock has fallen 63.1%, which puts the spotlight squarely on whether the earnings profile today justifies sticking with the story.
- As a medical device maker that depends heavily on consistent procedure volumes and product profitability, shifts in CONMED's margins and cash conversion can play a central role in how much investors are willing to pay for its earnings stream.
- There is a second opinion on CONMED worth weighing. See what analysts think CONMED's shares could be worth.
The stock's next move may depend on whether CONMED's current earnings level makes the recent share price look like a fair reflection of the underlying business or not.
If you want other ideas to compare with CONMED's recent earnings story, a focused starting point is our screener of 32 high quality undervalued stocks.
Is CONMED a Bargain on Earnings?
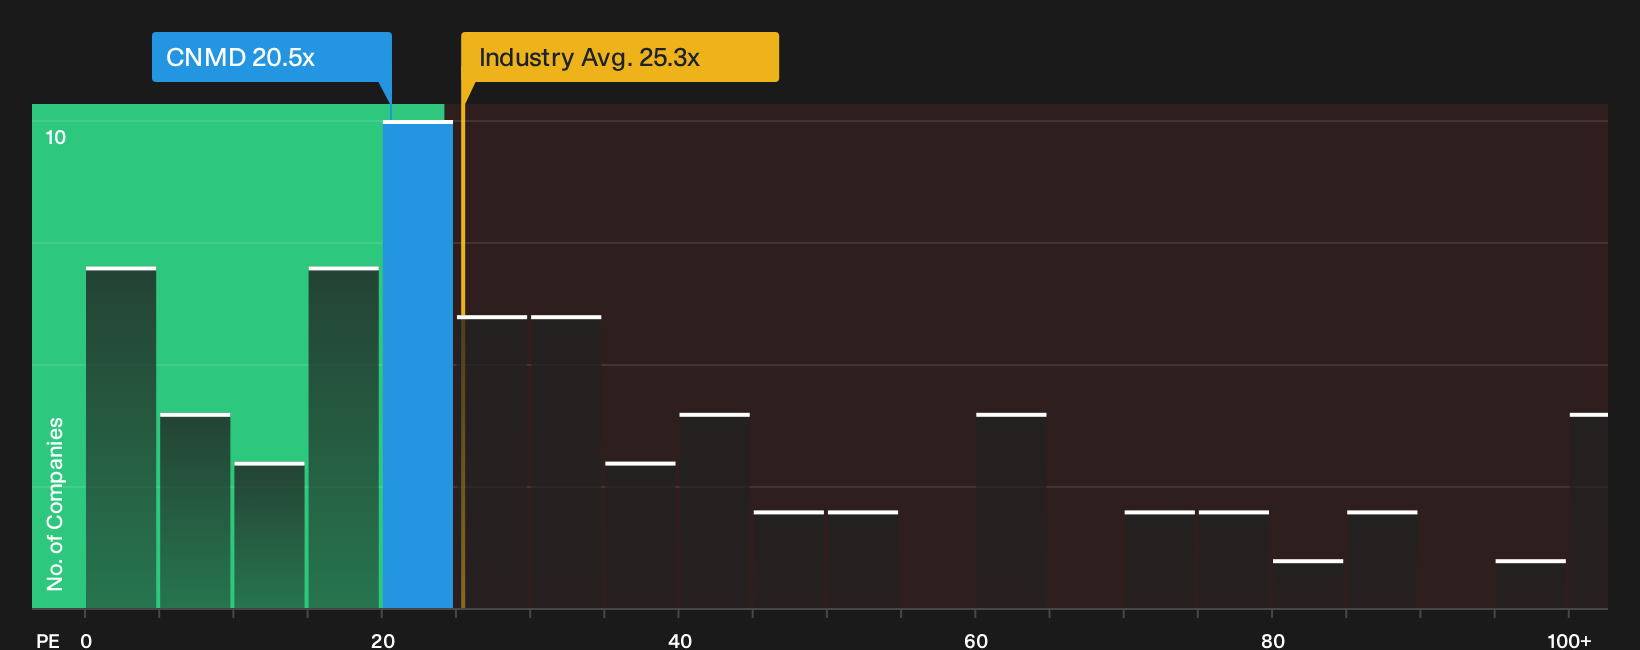
P/E fits CONMED because earnings are a central yardstick for most established medical equipment groups. On this measure, the stock trades at about 20.5x earnings, below the broader Medical Equipment industry around 25.3x and well under the peer group closer to 41.8x. For a reader comparing options inside the sector, that gap flags a more subdued price tag being applied to each dollar of CONMED's profit.
The fair multiple that blends the firm’s growth profile, profitability, size and risk points to a higher P/E than where the shares currently change hands. This suggests the market is pricing CONMED on the cautious side relative to those fundamentals. For anyone weighing whether the recent share price reset already reflects the earnings power of the business, the current discount on this P/E framework makes it worth checking how sustainable those profits look over the next few years. Explore the numbers behind CONMED's P/E valuation.
The CONMED Narrative: What Would Justify Today's Price?
Narratives pick up where the P/E puzzle leaves off for CONMED and explain which combinations of future growth, profitability and earnings paths would have to occur for the shares to look meaningfully higher or lower than today’s price. Each one links its number to a specific view on how CONMED's revenue potential, margin profile and risk picture might evolve, so you can return to that framing as new information becomes available. These narratives are available on Simply Wall St’s Community page.
One of the top narratives on CONMED: 11% overvalued
This Narrative is the analyst consensus Narrative on Simply Wall St, which compiles analysts' consensus price target and revenue and earnings forecasts, not one person's view.
"The numbers and current pricing together imply that CONMED’s share price already reflects a fair valuation with a bullish tilt rather than a deep discount or clear overvaluation..."
Discover why this Narrative puts CONMED at 11% overvalued.
One more CONMED check that belongs beside the earnings multiple
Price tags and profit figures only tell part of the story, because the people setting priorities, incentives and rewards can heavily influence how CONMED’s future value is built or eroded. See who runs CONMED and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com