
AZZ (AZZ) Could Be 22% Undervalued Following Its Earnings Setup
AZZ (AZZ) drew fresh attention after its stock closed at $134.22, a 1.31% move that outpaced broader indices, as investors positioned ahead of an earnings release.
AZZ’s recent 6.77% 7-day share price return, despite a 30-day decline of 2.5% and a 90-day drop of 11.32%, comes against a much stronger backdrop, with a 22.31% year-to-date share price gain and a 3-year total shareholder return of 178.46% that suggests long-term momentum remains solid.
Scan beyond AZZ and size up other industrials showing strong price action and earnings stories on our curated list of 43 power grid technology and infrastructure stocks.
After AZZ’s sharp run and a rich three year track record, the question is whether the meaningful upside sits ahead from here or if the easy money already moved.
Most Popular Narrative: 18% Undervalued
On the analyst consensus Narrative on Simply Wall St, AZZ is assigned a fair value of $164, which sits above the latest $134.22 close and frames the current share price as implying a discount to those long term assumptions.
The Washington, Missouri Precoat Metals facility is moving toward targeted utilization with its anchor container customer, and management is starting to commercialize the remaining capacity, which could add incremental revenue and improve segment margins as fixed costs are spread over higher volumes.
Ongoing deployment of AZZ's Digital Galvanizing System and CoilZone platforms across Metal Coatings and Precoat Metals, together with early work on using these data sets for AI driven pricing and efficiency gains, is aimed at raising throughput and reducing unit costs, which would support higher operating margins and earnings over time.
See why 5 investors see AZZ as 18% undervalued.
Result: Fair Value of $164 (UNDERVALUED)
Still, AZZ’s story can change quickly if winter weather again wipes out production days or if new facilities and bolt ons underperform integration plans.
Find out about the key risks to this AZZ narrative.
Another View: AZZ Through The P/E Lens
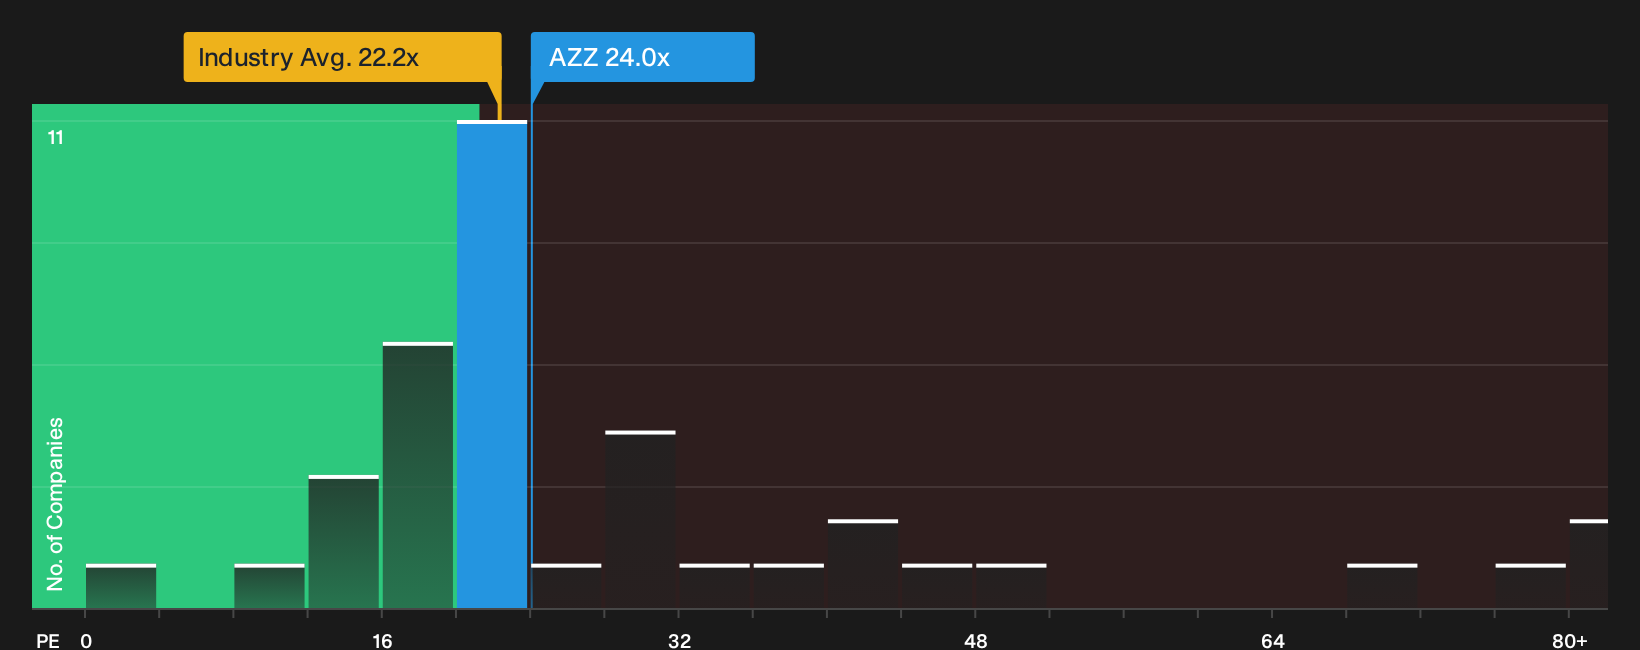
On simple multiples, AZZ looks expensive. The shares trade on a P/E of 24x, compared with 22.5x for the broader US Building industry and 17.9x for peers, while the fair ratio estimate sits at 19.5x. That gap points to valuation risk if sentiment cools.
For a closer look at how the current price lines up against these earnings multiples, and what the numbers imply for upside and downside, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around AZZ can be useful if you are prepared to move fast. Review both the potential upsides and the pressure points, then weigh the 3 key rewards and 2 important warning signs
Looking for more AZZ investment ideas?
If AZZ has your attention, do not stop here. Broaden your watchlist with fresh opportunities that match different risk, income, and quality goals.
- Target potential mispricing by scanning a 32 high quality undervalued stocks that lines up strong fundamentals with prices the market has not rewarded yet.
- Boost your income focus by reviewing 6 dividend fortresses that combine higher yields with an emphasis on resilience.
- Dial down risk by filtering for a 29 resilient stocks with low risk scores where balance sheets and volatility scores aim to keep surprises in check.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com