
GDS Holdings (GDS) Stock May Be A Bargain After AI Data Center News
GDS Holdings has seen its share price fall sharply this year, yet its role in some of the largest AI data centers in the world keeps expectations for its earnings firmly in focus. With that mix of weak recent returns and high profile infrastructure, the question is how much of the business's earnings power is already reflected in today's US$20.05 share price.
- Over the past 3 years the stock has gained 73.6%, which puts real weight on whether the current earnings base can support that kind of long haul move.
- The inclusion of GDS operated campuses among the world's biggest AI data centers may support expectations for more intensive capacity usage, which can shape how investors think about future profitability and the earnings multiple they are willing to pay.
- There is a second opinion on GDS Holdings worth weighing. See what analysts think GDS Holdings's shares could be worth.
For investors, the debate is whether GDS Holdings' current earnings and the price you pay for them line up with what the business is delivering today.
For a wider lens on AI infrastructure beyond GDS Holdings, a focused stock screen is a useful next step. It can be worth scanning 53 AI infrastructure stocks.
Does GDS Holdings Look Undervalued on Earnings?
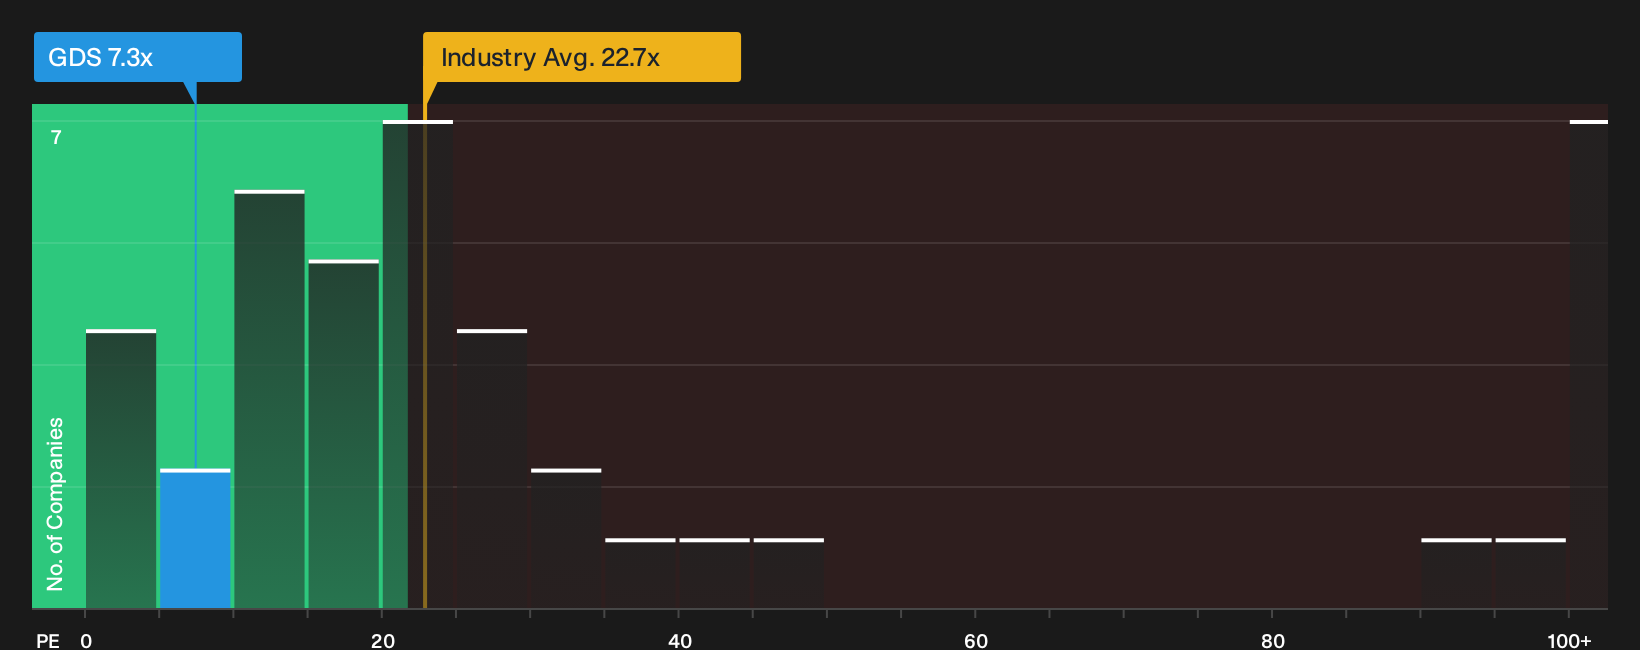
The P/E ratio is a clear way to compare GDS Holdings' share price with what it currently earns. On this measure, the stock trades on roughly 7.3x earnings, which is well below the IT sector average of about 22.7x and also beneath the broader peer group around 25.8x.
Because the fair P/E that would usually be expected for GDS Holdings, given its business profile, appears higher than the current multiple, the shares look undervalued on this yardstick. Despite the attention around its large AI data centers, the valuation still prices the business at a discount to where similar earnings streams often trade. That gap will matter most to you if you believe the present earnings base is durable and that the risks implied by this lower multiple are already reflected in the price. Explore the numbers behind GDS Holdings's P/E valuation.
The GDS Holdings Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the GDS Holdings valuation puzzle leaves off by explaining which growth, margin and earnings paths would need to occur for the stock to be worth materially more or materially less than today’s price. Each scenario links a fair value to a particular mix of potential catalysts and key risks, so you can track over time which story about GDS Holdings' future seems closest to reality on the Community page.
One of the top narratives on GDS Holdings: 58% undervalued
This narrative is the analyst consensus narrative on Simply Wall St, which compiles analysts' consensus price target and revenue and earnings forecasts, not one person's view.
"GDS Holdings is signing large AI focused, binding take or pay contracts, with 470MW of new capacity booked in the first half of 2026 and a full year sales target of 1GW…"
Discover why this Narrative puts GDS Holdings at 58% undervalued.
One more piece to weigh on GDS Holdings before you move on
There is a whole other lens you can use to sanity check today’s GDS Holdings valuation. You can look at how professional analysts see its earnings and revenue a few years ahead. Explore where analysts expect GDS Holdings to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com