
Will Raised 2026 Guidance Change TransMedics Group (TMDX) Narrative
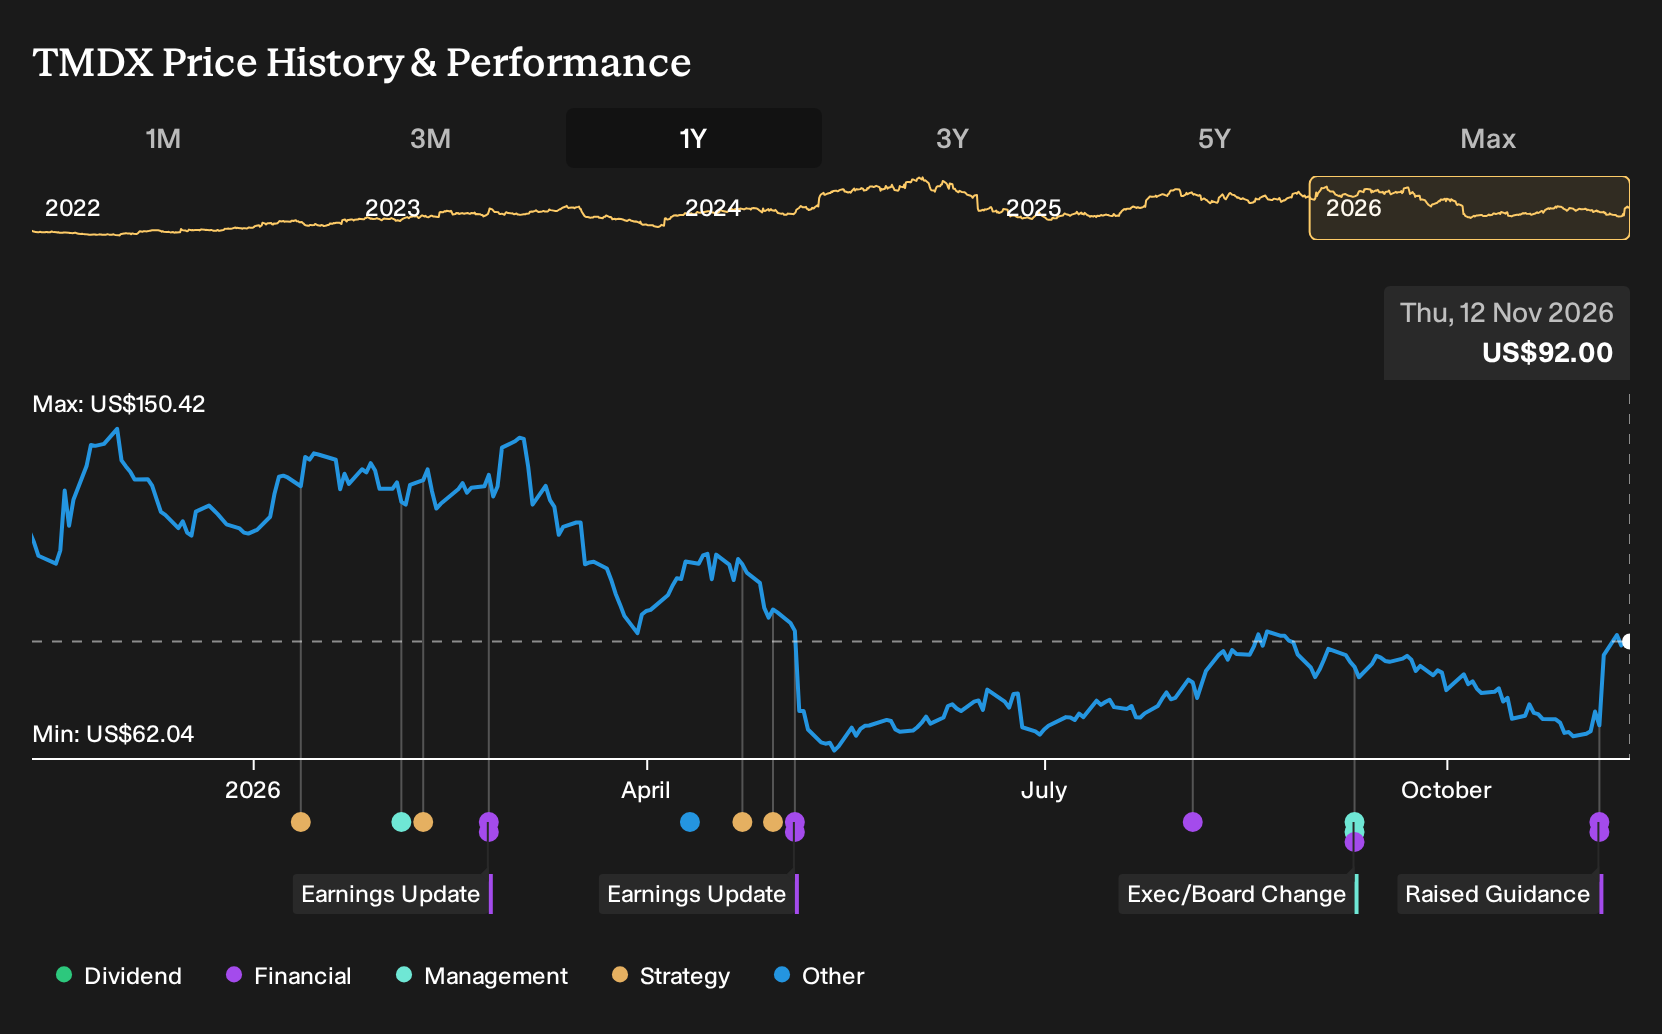
- TransMedics Group raised its full year 2026 revenue outlook in early November, lifting guidance to US$764 million to US$774 million, including about US$14 million from PAD Aviation, after reporting third quarter revenue of US$203.01 million.
- The higher forecast highlights management confidence despite pressure on profitability, with year to date revenue of US$566.89 million alongside lower net income and earnings per share versus the prior year period.
- This article examines how TransMedics Group's higher 2026 revenue guidance may reshape the investment narrative built around its transplant services platform.
TransMedics Group Investment Narrative Recap
To own TransMedics Group, you need to believe the transplant services platform can keep scaling across more organs and regions while controlling spending. The analyst consensus narrative on Simply Wall St already leans on that idea. The raised 2026 revenue outlook supports the view that procedure demand and service adoption are holding up, so the guidance change looks supportive rather than transformational.
The more immediate swing factor still sits in execution on OCS Kidney, Gen 3.0 and the European rollout, where higher operating expenses are already pressuring margins. The largest near term risk remains that this growth first spending does not translate into enough recurring procedures and service mix to offset lower net income and earnings per share.
The fresh 2026 revenue guidance is the clearest recent signal to focus on. Management now expects US$764 million to US$774 million, including about US$14 million from PAD Aviation. That range is higher than the prior US$737 million to US$757 million and assumes contributions from the existing platform rather than a late 2026 lift from new programs.
For you as an investor, the key link is to margins. The transplant engine is producing more top line, yet third quarter and year to date figures show lower net income and earnings per share than the prior year period. The guidance raise keeps the growth side of the thesis in view, but it also sharpens attention on whether TransMedics Group can turn that extra revenue into sustainable profitability rather than structurally weaker returns.
TransMedics Group's narrative projects US$1.1b revenue and US$229.5 million earnings by 2029. This implies 16.3% yearly revenue growth and an earnings increase of about US$85 million from US$144.5 million today.
Uncover why TransMedics Group's fair value indicates an 11% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One optimistic twist in the alternate TransMedics Group story is how bullish analysts framed revenue before this guidance hike. Some of them were already pencilling in about US$1.2b by 2029 and earnings of roughly US$185.1 million. Those views were set before this news, so you may want to see how their upside cases evolve.
Explore 7 other TransMedics Group fair value estimates, including one that suggests potential upside of up to 422% from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider trusting your own analysis.
- A great starting point for your TransMedics Group research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for TransMedics Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate TransMedics Group's overall financial health at a glance.
Looking For More Investment Ideas Beyond TransMedics Group?
If TransMedics Group has sharpened your focus on quality and risk, the next step is to widen your watchlist with other businesses that match your preferences on fundamentals, balance sheet strength, and potential income.
- For investors who want quality on sale, review a curated set of companies flagged as 32 high quality undervalued stocks that pair solid fundamentals with compressed valuations.
- If capital preservation comes first for you, scan a universe of stocks filtered for resilience through our 29 resilient stocks with low risk scores and see which ones suit your risk profile.
- For those hunting for quality that is still under the radar, expand your watchlist with a focused collection of 20 high quality undiscovered gems that score well on fundamentals but attract less market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com