
Sat Out Telkom SA SOC's Rally? Here Is What Holders Saw
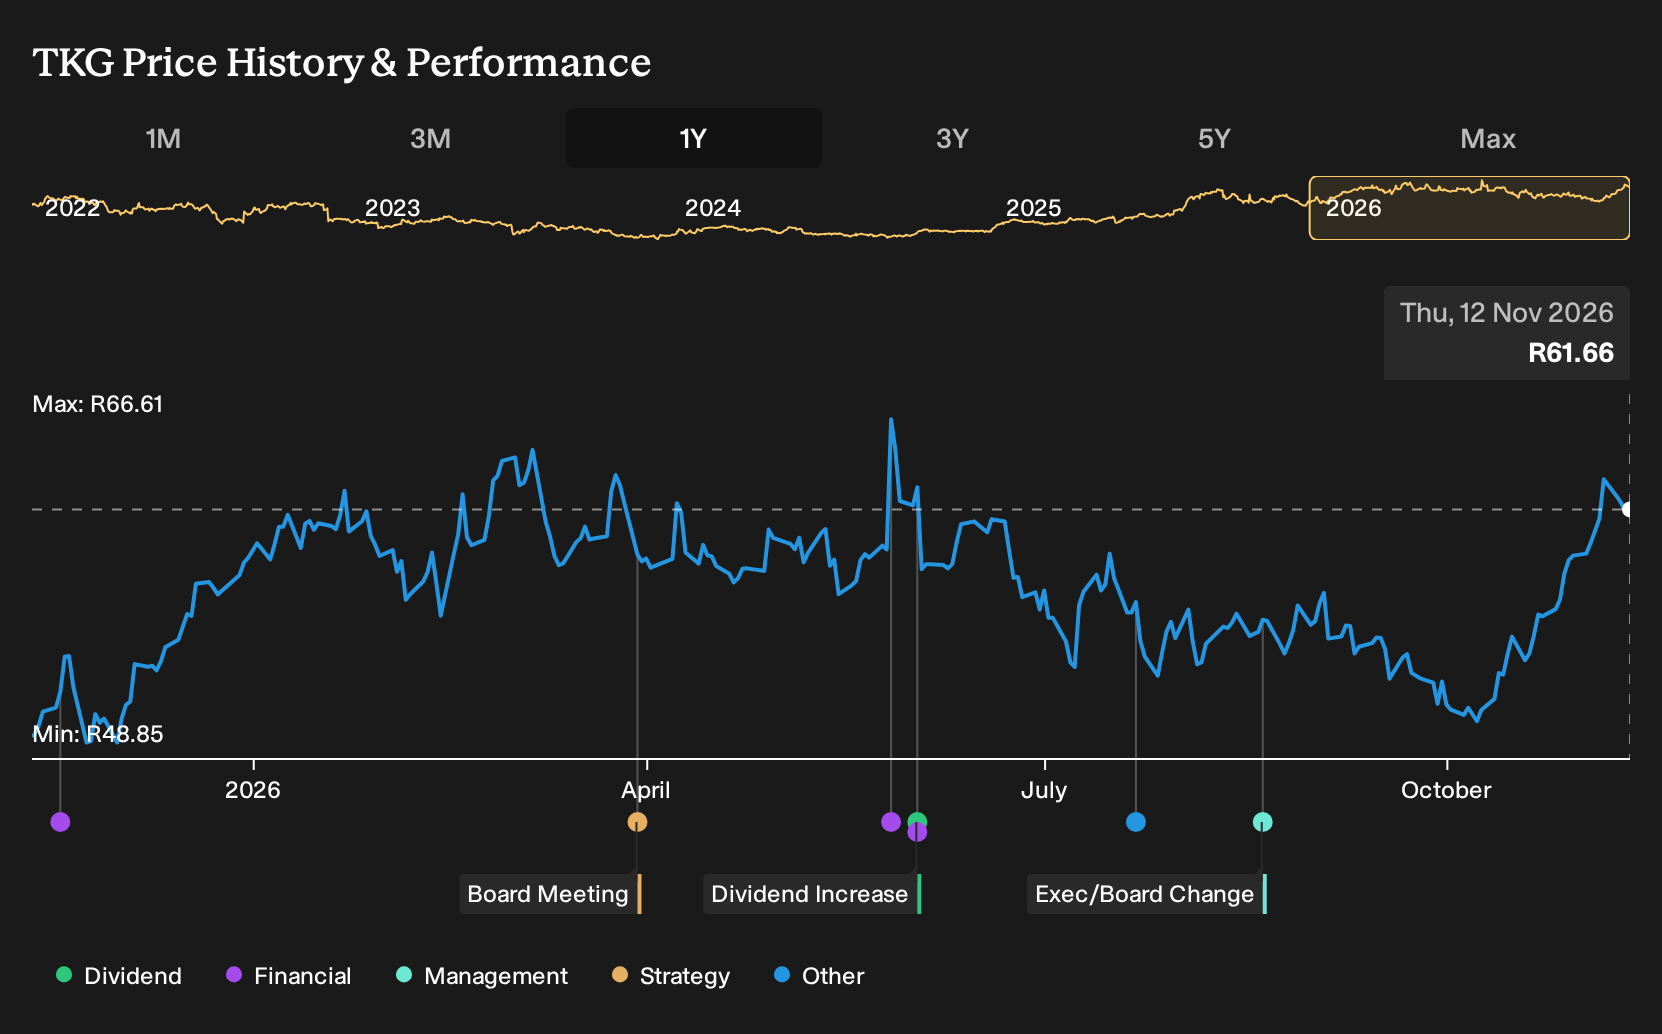
Fiber rollouts and cloud contracts grabbed headlines for Telkom SA SOC as management talked up digital platforms and legacy user migration. Investors who held Telkom SA SOC over the past year are up 29.8%, including dividends. If you had bought before that news flow, you would have needed a clear view on whether fixed-line decline, competition, and capital demands could coexist with rising net income and a slightly higher margin. What exactly made that belief reasonable at the start?
If the move has made Telkom SA SOC harder to judge, start where the gap is still open and scan 195 high quality undervalued stocks.
The Two Stories Telkom SA SOC Investors Were Weighing
The shares cost ZAR49.24 at the start of the period, and anyone looking at Telkom SA SOC had to decide which story felt more realistic.
The bullish narrative pointed to a Fair Value of ZAR63.92, essentially the price implied if expanding fiber networks, cloud platforms, and migration from millions of legacy users translated into resilient, high margin digital revenue.
The bearish view anchored on a Fair Value of ZAR45, arguing that shrinking fixed-line and ADSL income, along with intense mobile price competition from larger rivals, could keep pressure on group profitability.
What The Telkom SA SOC Results Actually Tested
The clearest fresh fact was the H2 2026 print. Telkom SA SOC reported revenue of ZAR22,212m against ZAR22,367m a year earlier, while net income inched up to ZAR1,940m and net margin edged to 8.7%. That combination of softer top line with slightly higher profitability cut both ways for the original bull and bear stories.
The useful lesson is simple. When a telecom pitch leans on margin resilience, you want to track net income and margin together against flat or falling revenue to see if the efficiency claim holds up.
What Telkom SA SOC's Current Price Is Asking You To Believe
Telkom SA SOC now trades at ZAR61.66. The bearish analyst Narrative on Simply Wall St puts its Fair Value below that level, arguing that the current quote already builds in confidence about cash returns and data-led momentum.
The Narrative’s core question is whether fibre, mobile and Openserve gains can comfortably outrun BCX softness. Anyone paying today’s price is effectively assuming enterprise weakness does not meaningfully cap future earnings power, so how does that sit against the pressure flagged in the source?
"Although Telkom SA SOC is growing group data revenue and lifting the share of data in total revenue, the 10.9% fall in BCX revenue in Q1 FY27, including a 30.1% drop in IT and software and 10.4% decline in fibre-related converged communications, points to ongoing pressure on enterprise demand that could cap future group revenue growth and weigh on earnings."
That disagreement has a full argument behind it. → Uncover the lower Fair Value this Narrative argues for
How Could You Get There Earlier?
By the time a rally makes headlines, you are reading about returns someone else has already earned. Why not go straight to the source and look for your own contrarian opportunity? These three companies trade below our estimated value.
- Company 1 - 38% below our estimate - helps clients address technical, safety and regulatory challenges via specialized consulting services.
- Company 2 - 40% below our estimate - develops dairy and nutrition offerings while extending into export-oriented consumer sales channels.
- Company 3 - 28% below our estimate - expands a fashion label's presence through boutiques reportedly recouping investment within a year.
Three companies from the same screener. Open all 200 companies with the balance sheet to back it up →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com