
Is Talen Energy (TLN) Fully Priced After Its New Capacity Deal?
Talen Energy has delivered a very large share price gain over the last three years, which puts a fresh spotlight on one basic question for you as a shareholder or prospective buyer: does the current valuation line up with the revenue the business is actually generating.
- Talen Energy's share price return over three years sits at a very large gain of 622.8%, which raises the stakes on whether the latest valuation still lines up with its sales base.
- The recently signed seven year 750 MW capacity agreement worth about US$100 million a year can support more predictable top line and contracted gross margin, which matters when you assess how much sales investors are paying for today.
- Your read on Talen Energy is one view; the desks covering it have another. See what analysts think Talen Energy's shares could be worth.
The issue now is whether Talen Energy's current share price near US$386.68 is justified by the level and quality of its sales.
If you want more options with a similar power and infrastructure angle, consider using a focused stock screen of 43 power grid technology and infrastructure stocks.
Where Does Talen Energy Sit on Sales?
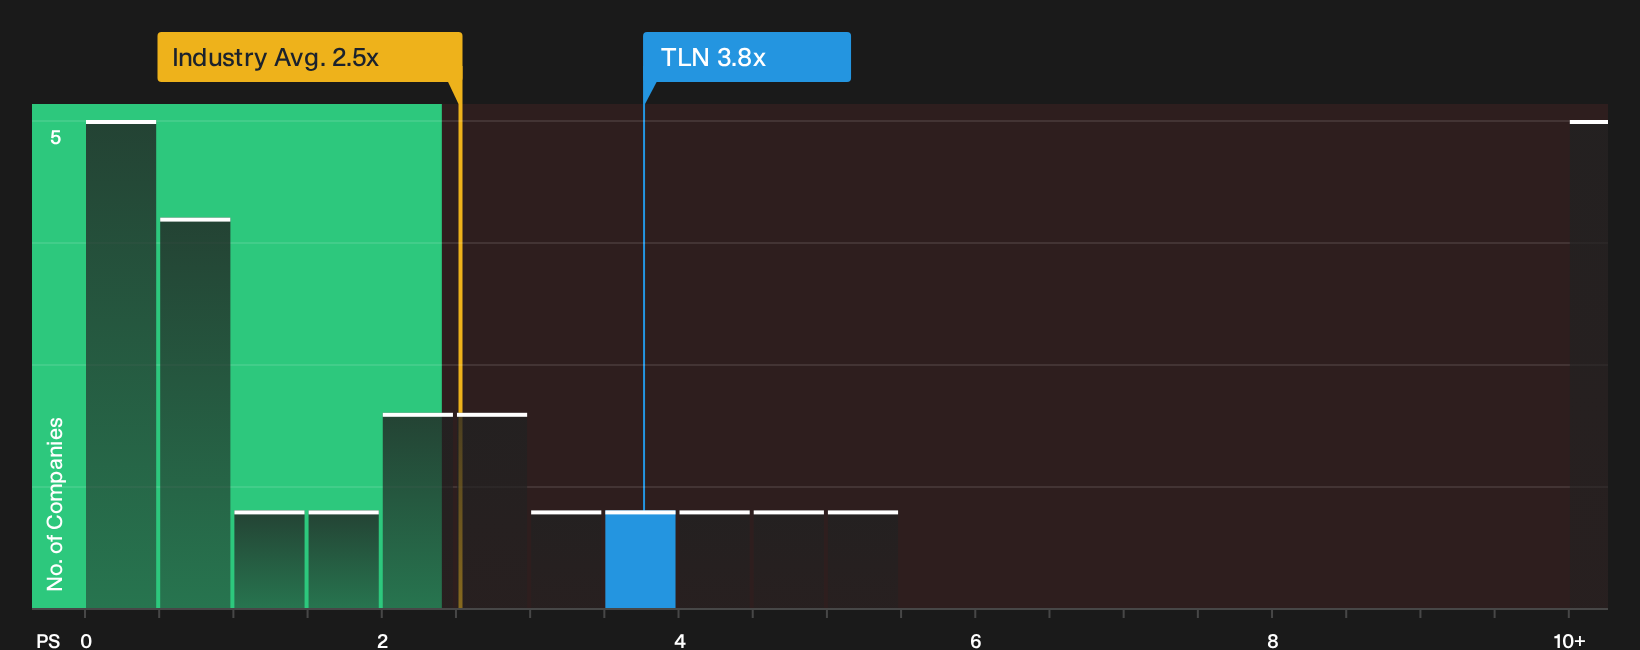
P/S works well for Talen Energy because investors are focused on contracted revenue and power capacity rather than current earnings. On this measure, the stock trades at about 3.8x sales, which is above both the Renewable Energy industry average of roughly 2.2x and a peer group nearer 1.7x. The tailored fair multiple from the model, which blends the company’s growth profile, margin structure, scale and risk, sits close enough to the current level that the ratio points to a price that is about right on this framework.
Because the seven year, US$100 million a year capacity deal locks in a chunk of future revenue, buyers are being asked to pay a richer P/S multiple for Talen Energy than for many power producers that have less contracted visibility. The key question for you is whether that higher sales multiple still feels acceptable once you weigh the quality and duration of these contracts against execution and regulatory risks. Explore the numbers behind Talen Energy's P/S valuation.
The Talen Energy Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Talen Energy pick up where this P/S puzzle leaves off by spelling out which future paths for growth, profitability and cash generation would need to occur for the stock to look materially stronger or weaker than today’s price. Each view ties its implied number to a clear stance on how Talen Energy's revenue mix, margins and risk profile might evolve, giving you a reference point to revisit as fresh information comes through.
Views on Talen Energy’s current price split sharply between those who see underpriced contracted cash flow and those who think optimism is already baked in.
Bull case: 16% undervalued
The analyst consensus Narrative on Simply Wall St leans on Talen Energy’s contract and cash flow story.
"The main requirement is continued execution on the flywheel strategy of pairing advantaged PJM baseload assets with multi gigawatt data center and C&I PPAs that lift contracted gross margin toward the higher mix management outlines and support long-term cash flow per share targets above $40..."
Discover why this Narrative puts Talen Energy at 16% undervalued.
Bear case: 17% overvalued
The bearish analyst Narrative on Simply Wall St focuses on policy risk and how much is already priced into Talen Energy.
"The numbers now in place, including guidance for roughly $4b of adjusted free cash flow from mid 2026 through 2028 and a plan to return at least 70% of this via buybacks, imply that the current share price already reflects a bullish and fairly valued view of Talen Energy’s cash generation potential..."
Explore why this Narrative puts Talen Energy at 17% overvalued.
One more piece of the Talen Energy puzzle to check
Valuation only tells part of the story for Talen Energy, because recent checks from our research also flag specific risk signals that could change how you frame the whole opportunity. Take a closer look at 1 major warning sign before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com