
Are Strong Earnings Altering The Investment Case For NRG Energy (NRG)?
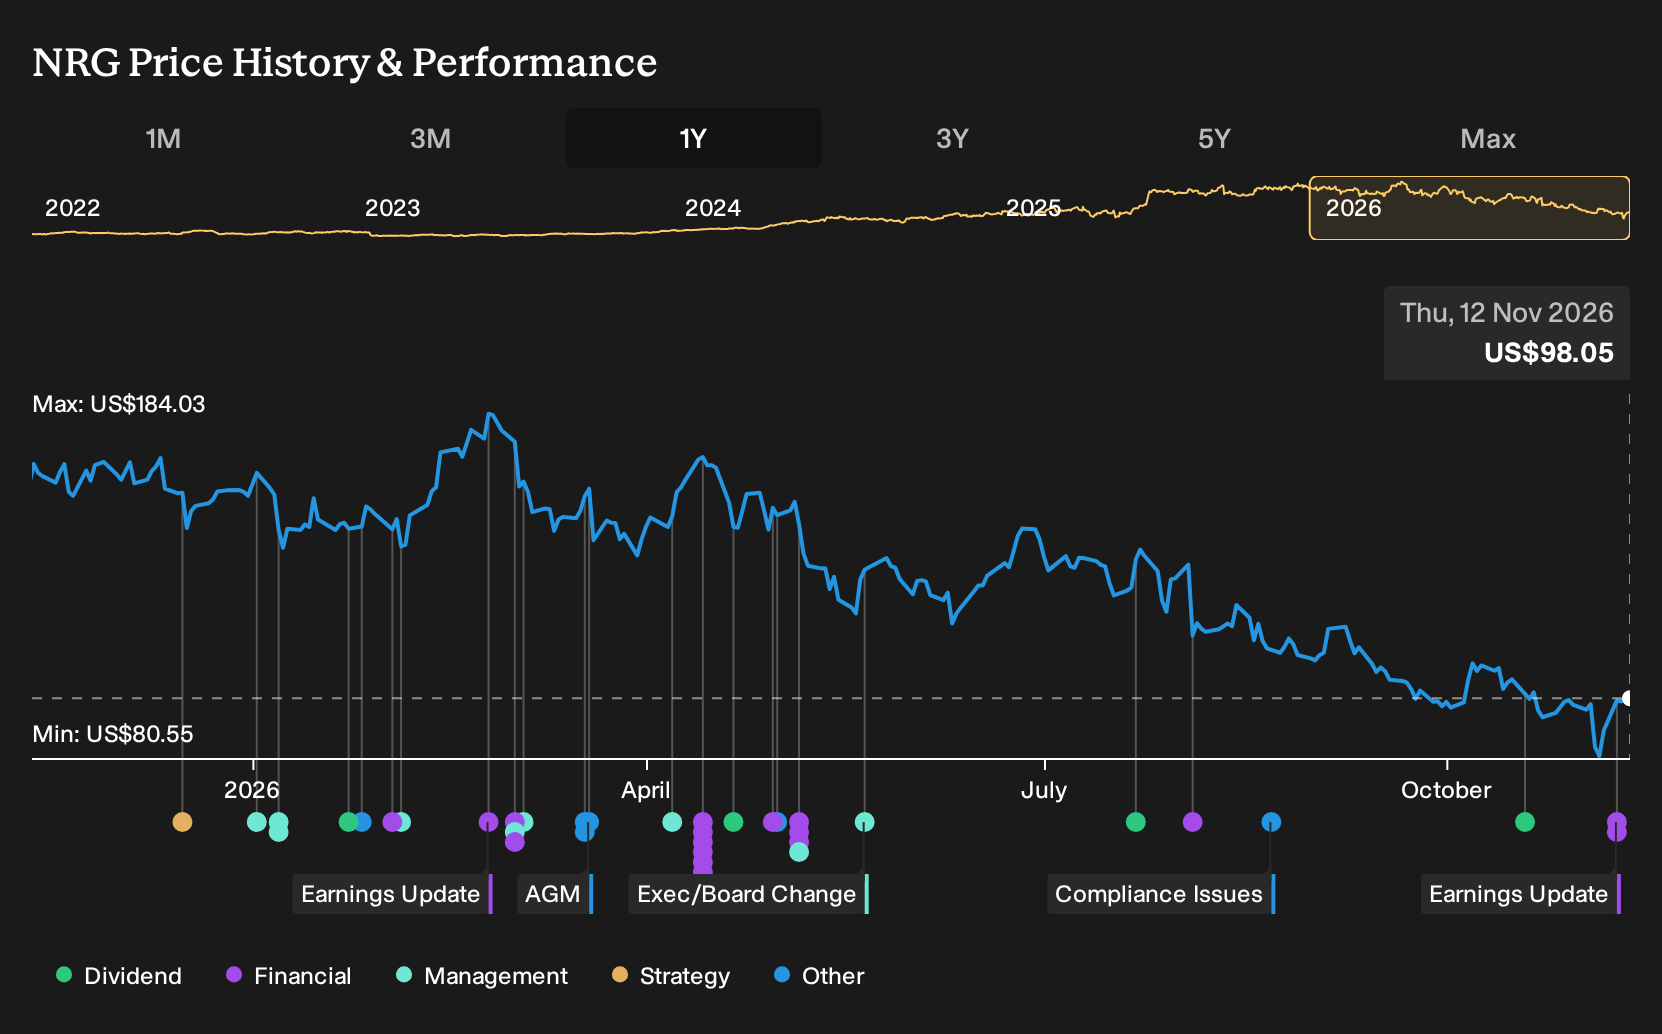
- NRG Energy reported third quarter 2026 sales of US$9,466 million and net income of US$561 million, reaffirmed full year 2026 guidance, issued 2027 guidance, updated its buyback progress, and declared a quarterly dividend of US$0.475 per share.
- The combination of higher reported earnings per share, continued net income guidance ranges, and ongoing capital returns clarifies how NRG Energy is balancing heavier leverage with cash generation and shareholder payouts.
- We will now look at how NRG Energy's stronger reported quarterly earnings reshape the earlier investment narrative around debt and cash flow.
Scan beyond NRG Energy and compare its earnings story with hand picked utilities and power producers in the 43 power grid technology and infrastructure stocks to see how other balance sheet heavy operators handle cash returns.
NRG Energy Investment Narrative Recap
To own NRG Energy right now, you need to believe that its larger, more leveraged platform can keep turning grid demand, data center load and home services into steady cash. According to John_Eric, an investor in the Simply Wall St Community who wrote the earlier narrative, the real question is whether those power plants and contracts earn enough to justify the debt attached to them.
The latest quarter delivers stronger reported earnings and confirms net income guidance ranges for 2026 and 2027, so the near term story hinges on execution rather than a reset. The key short term catalyst remains proof that higher earnings per share can coexist with heavy interest costs. The biggest risk is still that financing obligations limit flexibility if operating conditions soften.
The reaffirmed 2026 net income outlook of US$1,325 million to US$1,755 million, alongside fresh 2027 guidance of US$1,355 million to US$1,765 million, ties directly into that cash flow debate. John_Eric argues the acquisition driven build out turned NRG Energy into a test case for whether a highly geared power producer can convert grid tightness into durable free cash generation.
Keeping these guidance bands intact after a quarter with materially higher reported earnings per share gives investors a clearer hurdle. The business still needs to show that interest payments, which are flagged as not well covered by earnings in the risk summary, improve as integration progresses. If delivery tracks the ranges management has outlined, the guidance becomes a reference point for judging whether future capital returns and debt reduction stay realistic.
On John_Eric’s figures, that US$150.00 working fair value for NRG Energy comes from a model that couples 23.7% annual revenue growth with a 2.4% future profit margin. It then asks what equity value those economics might justify once debt, reinvestment needs, and capital allocation priorities are reflected.
Uncover why NRG Energy's fair value indicates a 53% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts frame the big catalyst very differently. They focus on NRG Energy’s build program, pointing to forecasts that revenue could reach about US$44.7b and earnings US$2.9b by around 2029, compared with US$782.0m previously. Those views predate this quarter’s update, so you may see them shift as new information sinks in.
Explore 5 other NRG Energy fair value estimates, including one that suggests as much as 382% potential increase from the current price.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your NRG Energy research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for NRG Energy. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate NRG Energy's overall financial health at a glance.
Looking for more NRG Energy style ideas?
If NRG Energy's mix of leverage, cash generation, and capital returns has your attention, it can help to line it up against other potential opportunities that fit different risk and return profiles.
- For investors willing to accept higher volatility in search of outsized gains, scan through 11 elite penny stocks with strong financials that already show solid fundamentals behind their small market values.
- If capital protection and resilience come first for you, focus on companies in the 29 resilient stocks with low risk scores that pair sturdier balance sheets with lower overall risk scores.
- When the goal is to find underfollowed opportunities with quality metrics, broaden your watchlist using our 20 high quality undiscovered gems and see which businesses warrant a deeper look.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com