
Brink's (BCO) Gets An Argus Upgrade, Is It Still Cheap?
Brink's (BCO) is back in focus after Argus raised its rating on the security services provider following third quarter results that paired higher sales with lower net income and fresh fourth quarter revenue guidance.
Recent trading reflects that shift in mood. Brink's shares have rallied, with a 14.62% 1 month share price return and a 6.10% 7 day move. A 6.00% 1 year total shareholder return and 86.09% 5 year total shareholder return suggest longer term holders have already seen meaningful gains as sentiment improves following the mixed earnings release and Argus upgrade.
Spot 20 high quality undiscovered gems that, like Brink's after the Argus upgrade, could see sentiment shift quickly as earnings news and guidance reset expectations.Bulls see Brink's recent share price jump and Argus upgrade as confirmation that the latest earnings wobble is temporary. Bears point to weaker net income. Which story fits the current valuation setup better?
Most Popular Narrative: 20.1% Undervalued
Brink's last closed at $116.97, while the analyst consensus Narrative on Simply Wall St anchors fair value at $146.33 using an 8.41% discount rate and detailed earnings and cash flow assumptions. That gap frames the current debate over whether recent earnings noise or the longer term free cash flow story should dominate your view.
The NCR Atleos acquisition is expected to roughly double Brink's scale to about US$10b of revenue and US$2b of adjusted EBITDA with US$200m of cost synergies and an indicated lift to EPS in the first year. This could reset how investors value the company once the combined EBITDA margin and free cash flow profile are reflected in reported results.
See why 5 investors see Brink's as 20% undervalued.
Result: Fair Value of $146.33 (UNDERVALUED)
Still, the Brink's narrative can break if the NCR Atleos integration stumbles or if weaker cash usage undercuts AMS and DRS economics.
Find out about the key risks to this Brink's narrative.
Another View: What Brink's P/E Is Telling You
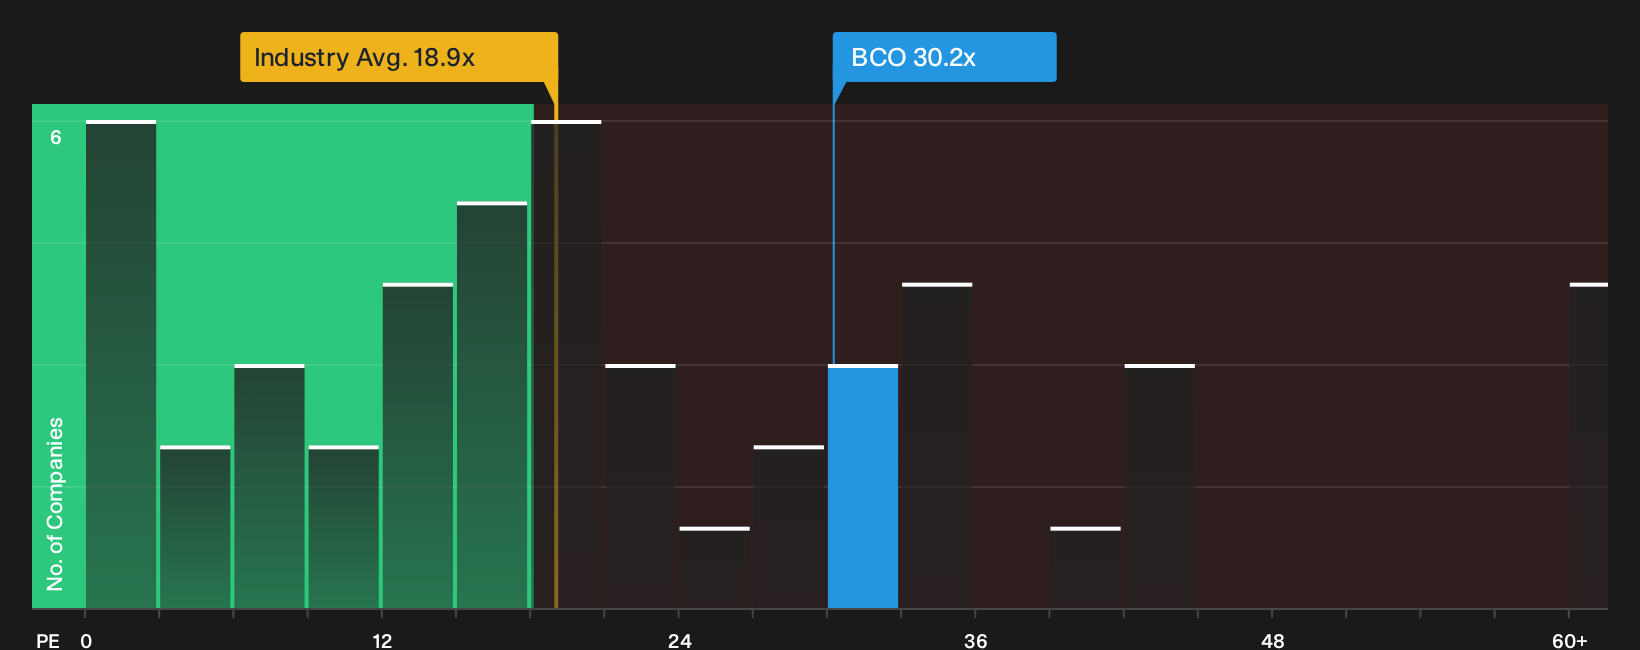
On the one hand, the Simply Wall St analyst narrative pegs Brink's fair value at $146.33, implying the shares look underpriced. On the other, the current P/E of 30.2x sits well above the US Commercial Services industry on 18.9x and peer average of 21.5x, even though the fair ratio points to 57.8x as a level the market could move toward. Is that gap a margin of safety or a sign that expectations already bake in a lot of the Atleos story?
For a closer look at how that comparison stacks up in practice, including where valuation risk might sit if sentiment cools, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed sentiment around Brink's is clear, with risks on one side and potential rewards on the other. Move quickly and stress test the numbers for yourself using the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Brink's?
If Brink's has sharpened your interest, do not stop here. Broader opportunities often emerge where strong balance sheets, reliable income and mispriced quality quietly line up.
- Target resilient potential by scanning companies with lower overall risk profiles through the 29 resilient stocks with low risk scores.
- Lock in income possibilities by reviewing businesses that clear the bar for generous, higher yielding payouts via the 6 dividend fortresses.
- Spot quality on sale by filtering for strong fundamentals that still look overlooked using the 32 high quality undervalued stocks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com