
iRhythm (IRTC) Stock May Look Reasonable Despite An Investor Investigation
iRhythm Holdings has seen its share price come under heavy pressure this year, and the slide has put fresh attention on whether the market is paying an appropriate price for the company’s sales. With the stock moving sharply while the business works through product and regulatory setbacks, the open question is how comfortably revenue supports the current valuation.
- The share price is down 46.6% year to date, which puts a spotlight on whether the current level of sales can justify where the stock now trades.
- Recent news around weaker top line performance, flat Zio AT product sales and a delayed device submission can shift expectations for future revenue growth and margins, which feeds directly into how much investors may be willing to pay for each dollar of iRhythm Holdings’ sales.
- The analysts covering iRhythm Holdings have run their own numbers. See what analysts think iRhythm Holdings's shares could be worth.
The issue now is whether iRhythm Holdings’ current share price is justified by its sales when measured against the Fair Ratio benchmark.
If you are weighing whether iRhythm Holdings’ current price fairly reflects its sales, it can help to compare that question across 32 high quality undervalued stocks.
Is iRhythm Holdings Still Cheap on Sales?
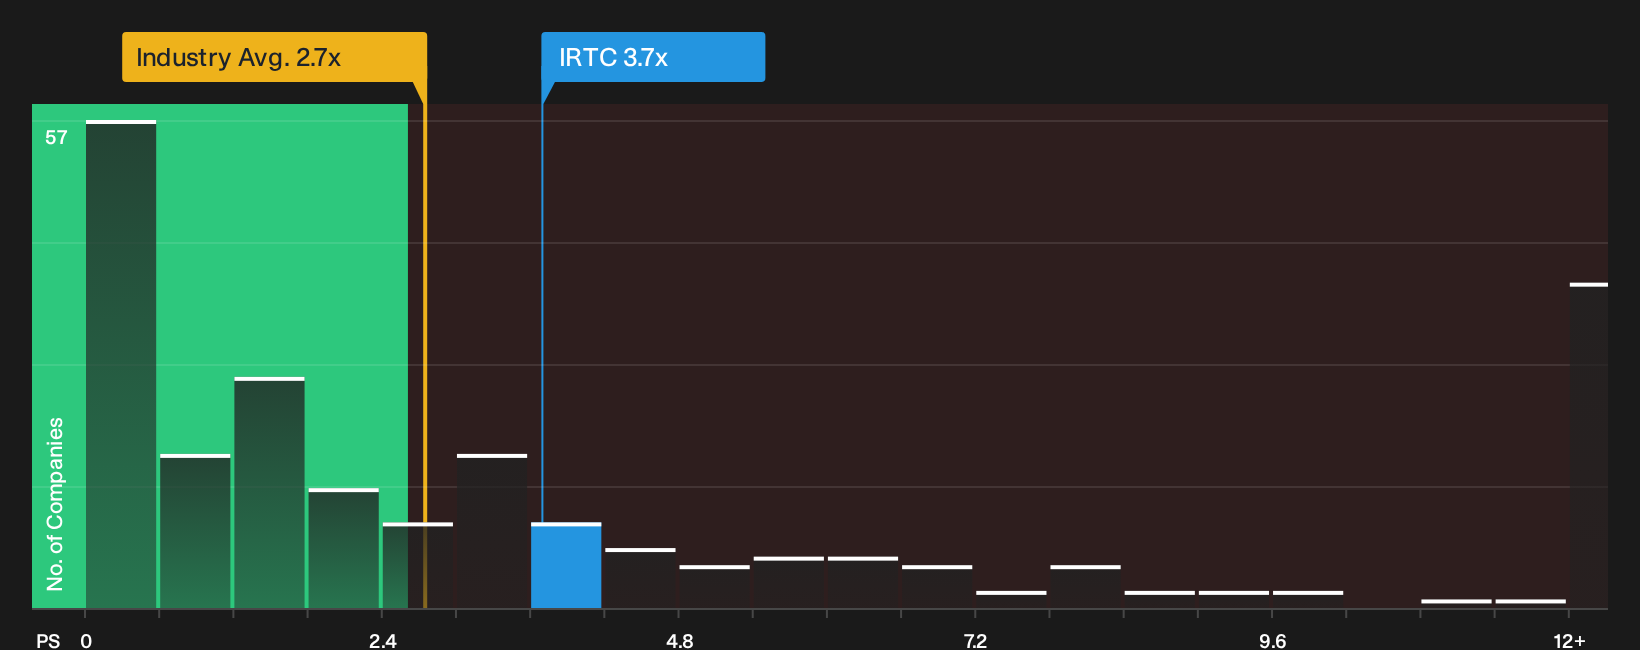
The P/S ratio works neatly for iRhythm Holdings because the focus is on commercial traction rather than current accounting profit. Right now the stock trades on a P/S of 3.7x, compared with a Medical Equipment industry average of 2.7x and a peer group near 4.9x. This means investors are paying more per dollar of revenue than the sector overall, but less than for similar companies already grouped around it.
The Fair Ratio model, which looks at growth prospects, margins, size and risk, suggests iRhythm Holdings trades below the multiple you might expect for those fundamentals. On that framework, this P/S level screens as undervalued. Because the Q3 revenue shortfall and delay to the next Zio MCT submission have already hit sentiment, the current discount on this sales multiple implies the recent news is priced in to a degree that could matter for anyone reassessing the story. Explore the numbers behind iRhythm Holdings's P/S valuation.
The iRhythm Holdings Narrative: What Would Justify Today's Price?
Narratives pick up where the valuation puzzle for iRhythm Holdings' P/S ratio leaves off, by spelling out which paths for growth, margins and earnings would need to unfold for the stock to look meaningfully higher or lower than today's price on Simply Wall St's Community page. Each scenario links a fair value estimate to a particular mix of potential catalysts and risks, which lets you track over time which version of events is getting closer to reality.
One of the top narratives on iRhythm Holdings: 44% undervalued
This Narrative is the analyst consensus Narrative on Simply Wall St, which compiles analysts' consensus price target and revenue and earnings forecasts, not one person's view.
"The main thing that has to go right is that iRhythm turns its high gross margins, AI driven workflow efficiencies, and VitalConnect integration into sustained operating leverage..."
Discover why this Narrative puts iRhythm Holdings at 44% undervalued.
One more thing about iRhythm Holdings that deserves a closer look
Price tags on sales tell only part of the story for iRhythm Holdings, because recent research checks have also flagged specific concerns that investors may want to weigh alongside the valuation. Take a closer look at 1 warning sign before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com