
Ellington Financial (EFC) Stock Still Looks Reasonable After Strong Q3 Results
Ellington Financial has delivered a 3 year gain that still looks solid on paper, even as the share price has been under pressure this year. That puts a sharper spotlight on whether the current valuation lines up with what its earnings can support. With fresh headlines around earnings strength and capital moves, the question for you is how much of that is already baked into the price.
- Over the past 3 years the stock has returned 23.6%, which makes it important to test whether that longer run up is still backed by the earnings power on offer today.
- Recent earnings reports highlighted a 36.92% one year EPS gain and stronger contributions from areas like Longbridge and LendSure, which can influence how durable investors judge Ellington Financial's profit engine to be.
- There is a second opinion on Ellington Financial worth weighing. See what analysts think Ellington Financial's shares could be worth.
The issue now is whether the current share price of Ellington Financial is justified by the earnings that the business is generating today.
If you want a broader watchlist while you assess whether Ellington Financial's earnings justify today's price, a focused screen of 32 high quality undervalued stocks can be a useful next step.
Is Ellington Financial Still Cheap on Earnings?
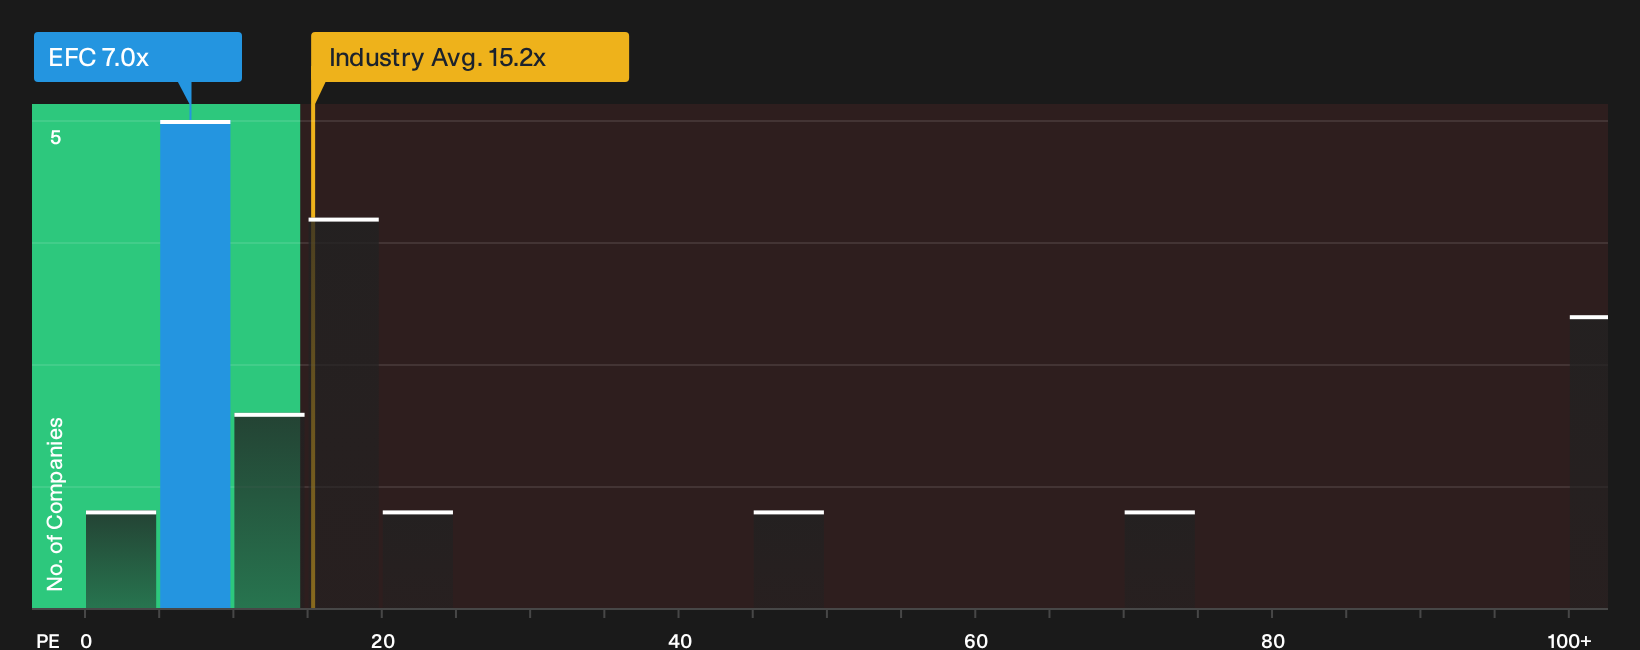
P/E makes sense for Ellington Financial because earnings are a key focus for mortgage REIT investors who care about what each dollar of profit costs them. On this yardstick, the stock trades at about 7.0x earnings, which is below both the mortgage REIT sector average of roughly 15.2x and a peer group closer to 10.8x. The gap suggests the market is applying a lower price tag to each dollar of Ellington Financial’s reported profit than to many rivals in the same corner of the market.
The Fair Ratio model, which adjusts the target multiple for Ellington Financial’s earnings profile, book value and risk, points to a higher P/E than the current 7.0x, so the shares screen as undervalued on this framework. Because the latest earnings report showed solid profit delivery alongside fresh capital issuance and a Statebridge acquisition, the discount also implies investors are still treating those developments cautiously rather than paying up for them. Explore the numbers behind Ellington Financial's P/E valuation.
The Ellington Financial Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where this valuation puzzle on Ellington Financial leaves off by spelling out the earnings, margin and growth paths that would need to hold for the stock to trade meaningfully higher or lower than today’s level. Each one lays out its own fair value assumptions in detail so you can weigh those inputs against Ellington Financial's actual results as they arrive on the Community page.
One of the top narratives on Ellington Financial: 26% undervalued
This Narrative is the analyst consensus Narrative on Simply Wall St, which compiles analysts' consensus price target and revenue and earnings forecasts, not one person's view.
"Active portfolio rotation and frequent securitizations, including about US$4.0 billion of unpaid principal balance securitized in the first half of 2026, show that Ellington Financial’s loan acquisition to securitization ecosystem is scaling..."
Discover why this Narrative puts Ellington Financial at 26% undervalued.
For Ellington Financial, the share price is only one decision point
Before you treat Ellington Financial’s valuation as the whole story, it is worth asking who is steering the portfolio and how their pay packets line up with your interests. See who runs Ellington Financial and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com