
Is Taiwan Semiconductor Manufacturing (TSM) Fully Valued As Record October Revenue Sparks A Rebound?
Taiwan Semiconductor Manufacturing (NYSE:TSM) is back in focus after reporting record October revenue of NT$586.89b, with the stock recently reacting to both the sales update and fresh ETF flow data.
At a US$405.49 share price, Taiwan Semiconductor Manufacturing has seen short term momentum surge, with a 7 day share price return of 14.84% coming after the stock fell 8.90% over the past month. A 44.86% 1 year total shareholder return and a very large 3 year total shareholder return of more than 3x suggest the recent reaction to record sales and mixed ETF flows is playing out against a backdrop of strong longer term gains and a shifting view on both its growth potential and risk profile.
Scan how other chip and AI infrastructure plays are reacting to this backdrop by comparing Taiwan Semiconductor Manufacturing with our curated list of 53 AI infrastructure stocks.
After a record revenue print, a sharp bounce in Taiwan Semiconductor Manufacturing and mixed ETF flow signals, the real tension now is simple. Does the current price still leave enough upside to justify the risk being taken on?
Most Popular Narrative: 7% Overvalued
Against a fair value estimate of $378.29 from the most followed narrative, Taiwan Semiconductor Manufacturing at $405.49 is framed as slightly expensive, and the gap matters once larger risks enter the picture according to tripledub, an investor in the Simply Wall St Community who wrote that narrative.
TSMC is the rarest of things: a monopoly whose dominance is rooted not in regulatory capture or historical accident, but in genuine technological supremacy. The company has spent decades perfecting the art of manipulating matter at atomic scales, and the cumulative knowledge embedded in its fabrication processes is essentially irreproducible.
See why 144 investors see Taiwan Semiconductor Manufacturing as 7% overvalued.
Result: Fair Value of $378.29 (OVERVALUED)
Still, investors following Taiwan Semiconductor Manufacturing need to keep an eye on any shift in AI accelerator demand or any meaningful loss of key foundry customers.
Find out about the key risks to this Taiwan Semiconductor Manufacturing narrative.
Another View On Taiwan Semiconductor Manufacturing’s Price Tag
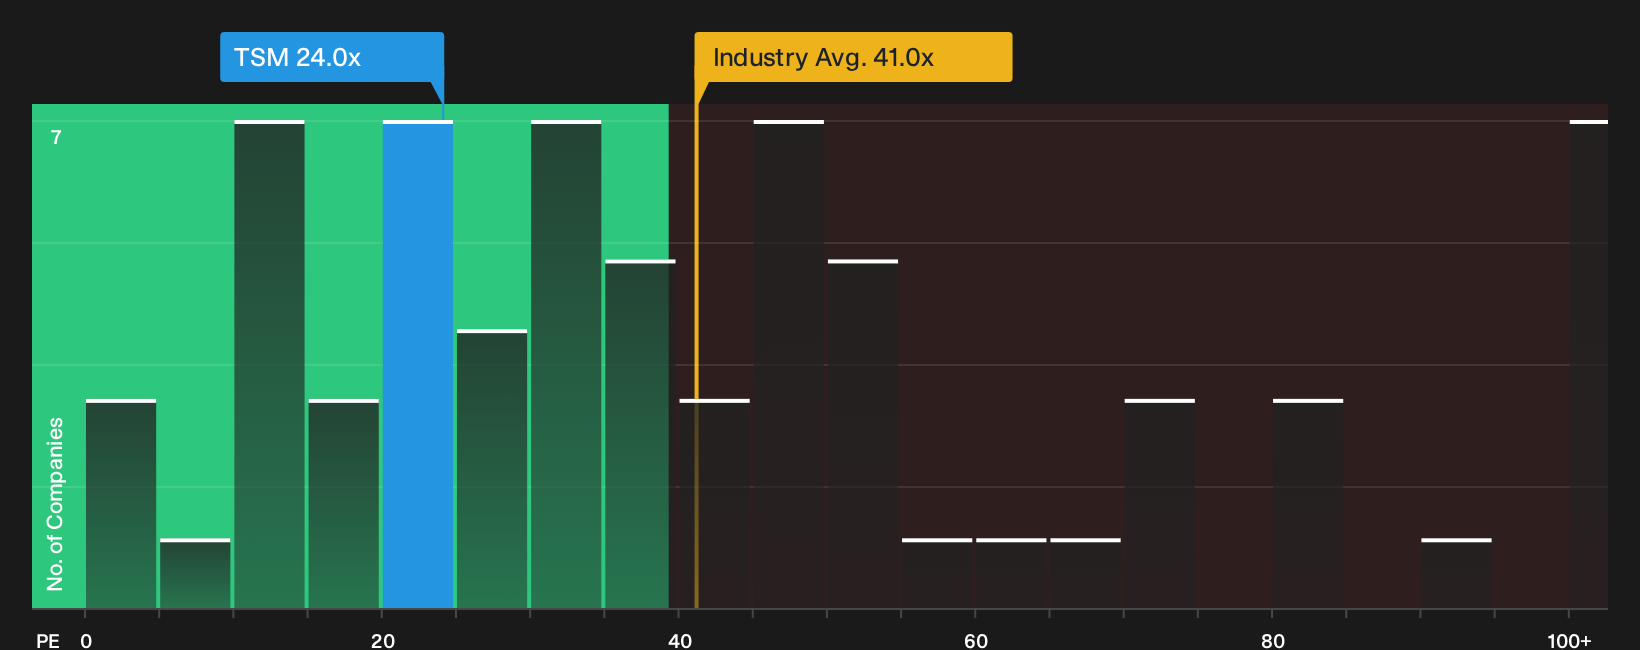
On simple P/E math, Taiwan Semiconductor Manufacturing looks far less stretched. At roughly 24x earnings versus about 41x for the US Semiconductor group and 50.3x for close peers, the share price lines up well below those yardsticks. Our fair ratio of 35.4x points to a market that could still re-rate this stock upward, which leaves you weighing valuation upside against the operational and geopolitical risks already on the table.
For investors comparing this P/E signal to the narrative fair value work, the next step is to stress test the earnings assumptions and see what the numbers imply if sentiment cools or the peer premium narrows, rather than assuming today’s discount will always hold, then See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals or clear story? Either way, you are better off reviewing the numbers yourself and weighing both sides through the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Taiwan Semiconductor Manufacturing?
If you stop with Taiwan Semiconductor Manufacturing, you only see part of the opportunity set. Widen your lens now and give your portfolio more options.
- Target steadier compounding by scanning a curated pool of resilient companies through our 29 resilient stocks with low risk scores.
- Hunt for mispriced quality by using the 32 high quality undervalued stocks that flags businesses with solid fundamentals at discounted valuations.
- Spot future leaders early by reviewing the 20 high quality undiscovered gems that highlights strong businesses still flying under most investors’ radar.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com