
Coherent (COHR) Stock Looks Fairly Valued Following Strong AI Demand
Coherent has been on a powerful multi year run in the market, and recent AI driven enthusiasm has pushed the conversation back to a basic question for investors. Do the company’s current earnings support where the stock trades today, or has sentiment moved faster than the profit line?
- Over the past 3 years the share price has risen by a very large amount, which puts extra focus on whether profit growth can ultimately support that kind of gain.
- Fresh demand from AI data centers for Coherent’s photonics and optical products, along with long term supply commitments, can shape how investors think about the durability and timing of future earnings streams.
- The analysts covering Coherent have run their own numbers. See what analysts think Coherent's shares could be worth.
The issue now is whether Coherent’s current share price is justified by the earnings it is generating today and what those profits suggest about the business over time.
If you are weighing Coherent against other AI infrastructure opportunities, a focused stock screen can be a clear next step, especially something like 53 AI infrastructure stocks.
Where Does Coherent Sit on Earnings?
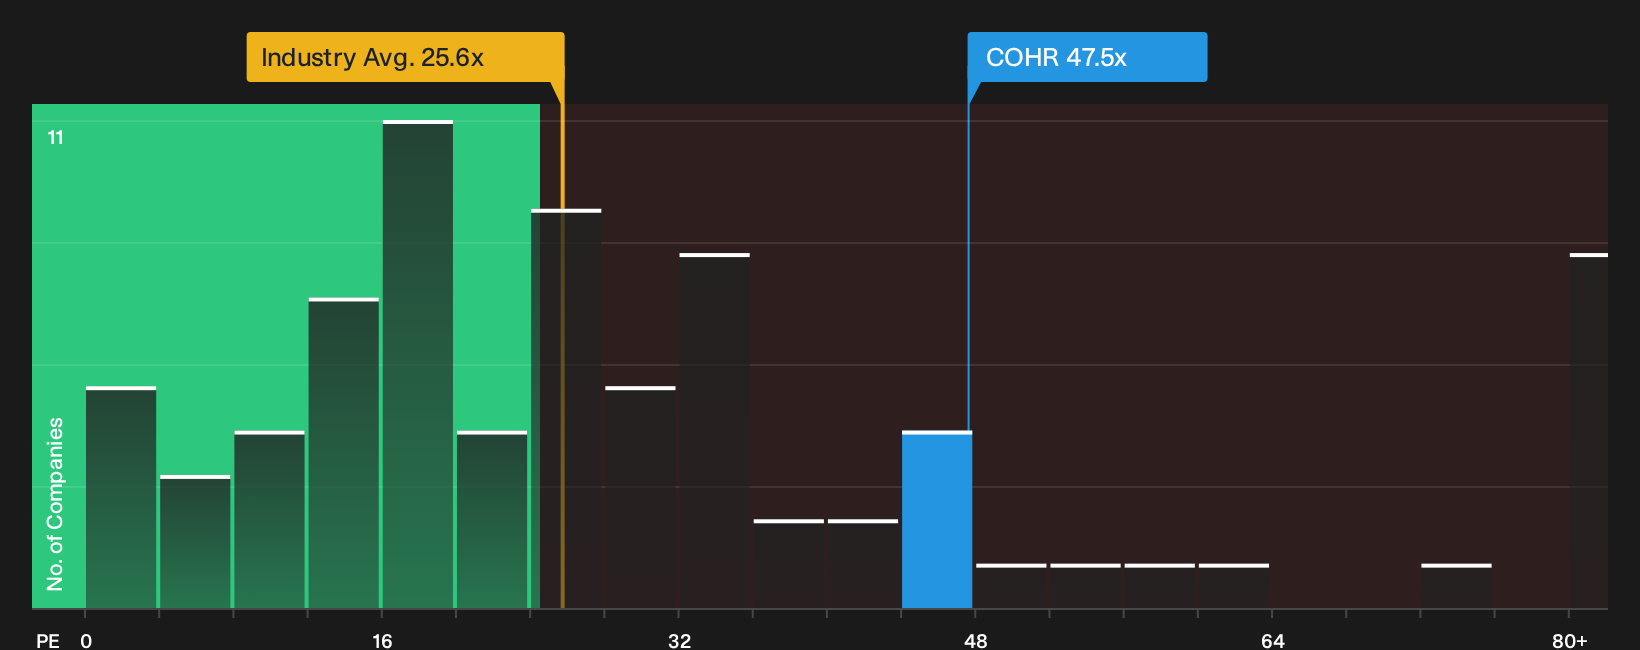
The P/E ratio suits Coherent because the story in this stock is now squarely about earnings power tied to AI optics. Coherent trades at about 47.5x earnings, above both the peer group near 35.4x and the broader electronic industry at about 25.6x. That puts a clear earnings premium on the shares compared with many other hardware and component makers.
Recent upside from strong fiscal 2027 guidance and AI data center demand has not pushed the valuation wildly away from the level suggested by a more tailored fair multiple, which sits close to where the stock now trades. The current P/E is only slightly above that fair marker, so the market is asking for some delivery on AI driven earnings without stretching into extreme territory. For an investor weighing Coherent against other AI infrastructure plays, the key question is whether that higher multiple feels justified by the durability of its optical demand story and margin ambitions over time. Explore the numbers behind Coherent's P/E valuation.
The Coherent Narrative: What Would Justify Today's Price?
Simply Wall St Narratives picks up where the P/E debate on Coherent leaves off and explains which combinations of growth, margins and earnings would need to occur for the stock to be worth materially more or materially less than today’s market price. Each scenario focuses less on a single multiple and more on the specific inputs behind its fair value view, so you can track those assumptions against Coherent’s reported results on the Community page over time.
One of the top narratives on Coherent: 40% undervalued
This Narrative is the analyst consensus Narrative on Simply Wall St, which compiles analysts' consensus price target and revenue and earnings forecasts, not one person's view.
"Internal manufacturing investments, business divestitures, and expanding services boost margins, support debt reduction, and deliver more stable, higher-quality recurring revenue..."
Discover why this Narrative puts Coherent at 40% undervalued.
One more check for Coherent before you close the tab
Price multiples tell you what the market asks of Coherent today, while the analyst models a few years out show what others think the business might realistically deliver next. Explore where analysts expect Coherent to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com