
Nvidia Shares Are Bleeding Red as Jensen Huang Resigns, But Analysts See Huge Runway for Rival AMD’s Stock
William Blair analysts believe Advanced Micro Devices (AMD) shares stand to benefit significantly from the recent Nvidia (AMD) fallout. The scandal that led to Nvidia CEO Jensen Huang’s resignation this week prompted the investment firm to upgrade AMD stock to “Outperform.”
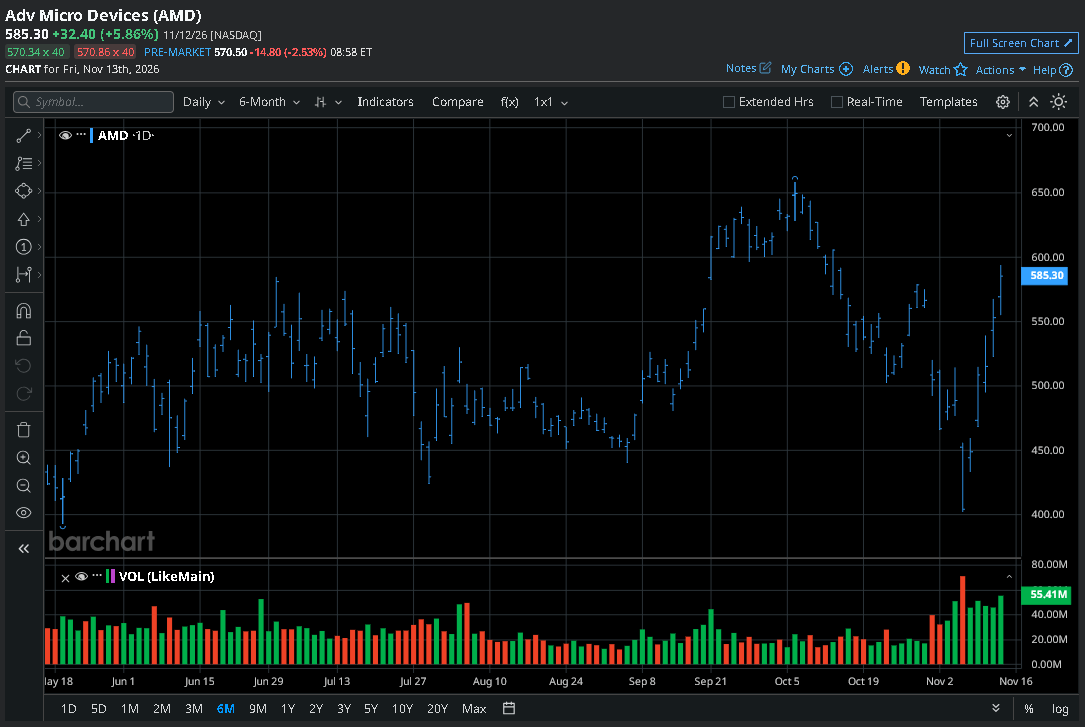
AMD has already been a blockbuster investment in 2026, currently trading at more than 2.5x its price at the start of this year.
William Blair’s Bullish View on AMD Stock
According to William Blair analysts, NVDA’s leadership crisis creates an immediate opening for chip buyers to diversify suppliers. As Nvidia navigates executive upheaval and regulatory scrutiny, Dr. Lisa Su’s team remains focused on execution, they told clients in a recent report.
Simultaneously, ongoing roadmap delays and supply bottlenecks for Intel’s Xeon processors leave AMD a full year ahead in addressing a server CPU market projected to reach $220 billion by 2030.
Although custom chips from Meta (META) and OpenAI pose competition to AMD’s Instinct accelerators, Naji expects those bespoke deployments to drive lucrative server CPU attachment rates.
Note that AMD shares currently sit above major moving averages (MAs), indicating bulls remain firmly in control across multiple timeframes.
AMD’s Financials Warrant Buying Stock
Other than highlighting a massive competitive opening following the recent Nvidia controversy, William Blair analysts cited AMD’s accelerating fundamental momentum for their bullish stance.
In its latest reported quarter, the company saw its data center revenue nearly double to $8.5 billion, and the investment firm expects that segment to eclipse its server CPU unit in the fourth quarter of 2026.
Backed by the multi-year ramp of rack-scale Helios AI systems and MI450 accelerators, William Blair forecasts AMD could deliver over 80% total revenue growth in 2027 — more than double its long-term financial model.
That said, a 74x forward earnings multiple makes AMD stock an expensive name to own.
How Wall Street Recommends Playing AMD
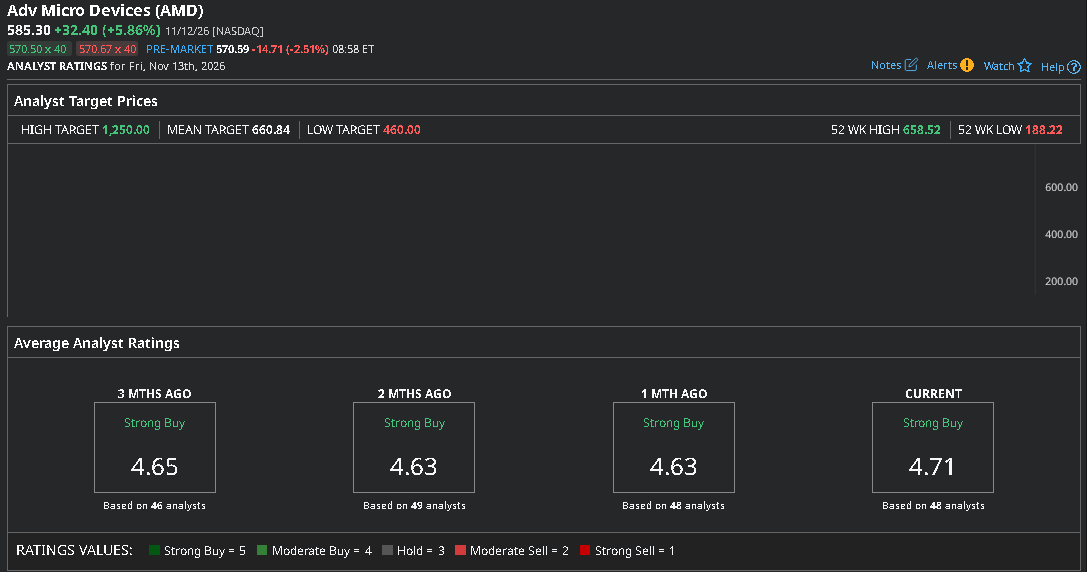
Other Wall Street analysts also remain convinced that Advanced Micro Devices is not out of upside room yet. The consensus rating on AMD shares sits at “Strong Buy,” with the mean price target of about $661 indicating potential for another 13% rally from current levels.
On the date of publication, Wajeeh Khan did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.