
Harrow (HROW) Stock Could Be Below Fair Value Despite Record Revenue
Harrow has swung sharply over recent years, leaving investors asking whether a stock at about US$28 and a mixed return pattern is properly backed by the revenue it now produces. With sales in focus and sentiment shifting quickly after recent updates, the open question is how much of that performance is already reflected in the price you see on screen.
- Harrow has delivered a 3 year share price gain of about 229.1%. That places significant attention on whether its current sales base can support that kind of rerating.
- Record recent revenue from branded ophthalmic products and fresh product launches, alongside higher spending on research and acquisitions, can reshape how investors think about future sales growth versus profitability and capital needs.
- Your read on Harrow is one view; the desks covering it have another. See what analysts think Harrow's shares could be worth.
The issue now is whether Harrow's current valuation is adequately supported by its sales, given the recent share price history and business developments.
If you are weighing Harrow against other opportunities tied to specific themes, a focused stock screen can be a useful second lens alongside this single ticker. A potential starting point is 35 healthcare AI stocks.
Is Harrow Still Cheap on Sales?
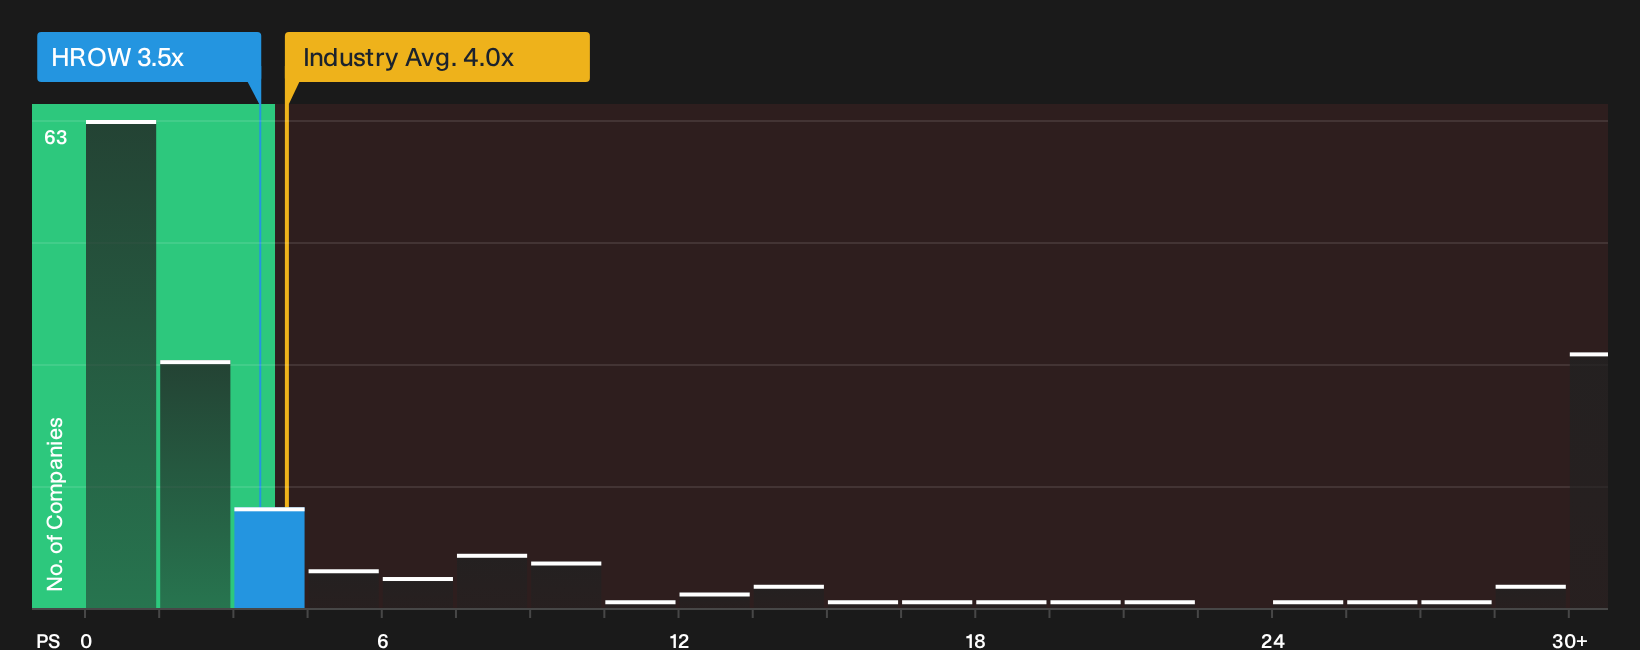
P/S works well for Harrow because investors are focused on how much revenue the business is generating from its ophthalmic portfolio. From this perspective, Harrow trades on a P/S of about 3.5x, compared with roughly 4.0x for the wider Pharmaceuticals industry and a peer average near 4.0x. That places the stock at a discount to both the sector yardstick and closer peers on a pure sales basis.
The tailored valuation model, which factors in Harrow's size, growth profile, profitability path and risk, points to a higher P/S than where the shares change hands today, so the current multiple screens undervalued against that benchmark. Because record Q3 2026 revenue and reaffirmed full year sales guidance have already reset expectations, the fact the P/S ratio still sits below this implied level suggests the market is not assigning a full premium to the existing top line yet. Explore the numbers behind Harrow's P/S valuation.
The Harrow Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where Harrow's P/S puzzle leaves off. They spell out which paths for revenue growth, margins and earnings would need to unfold for the stock to look meaningfully higher or lower than today. Each scenario links a fair value estimate to a clear storyline about Harrow's potential catalysts and key risks, so you can track over time which version of events is actually taking shape on the Community page.
One of the top narratives on Harrow: 37% undervalued
This Narrative is the bearish analyst Narrative on Simply Wall St, built on the most pessimistic analyst price target and forecasts, not one person's view.
"The numbers imply the share price already prices in meaningful success across Harrow’s dry eye, retina and procedural sedation franchises, so any stumble on product uptake..."
Discover why this Narrative puts Harrow at 37% undervalued.
Harrow’s valuation leaves one more crucial angle unexplored
Price multiples tell you what the market is willing to pay today, but the real test is how that stacks up against where professional forecasts expect Harrow to be in a few years. Explore where analysts expect Harrow to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com