
Did Phase 3 Eye Drug Results Just Shift Kodiak Sciences (KOD) Investment Narrative?
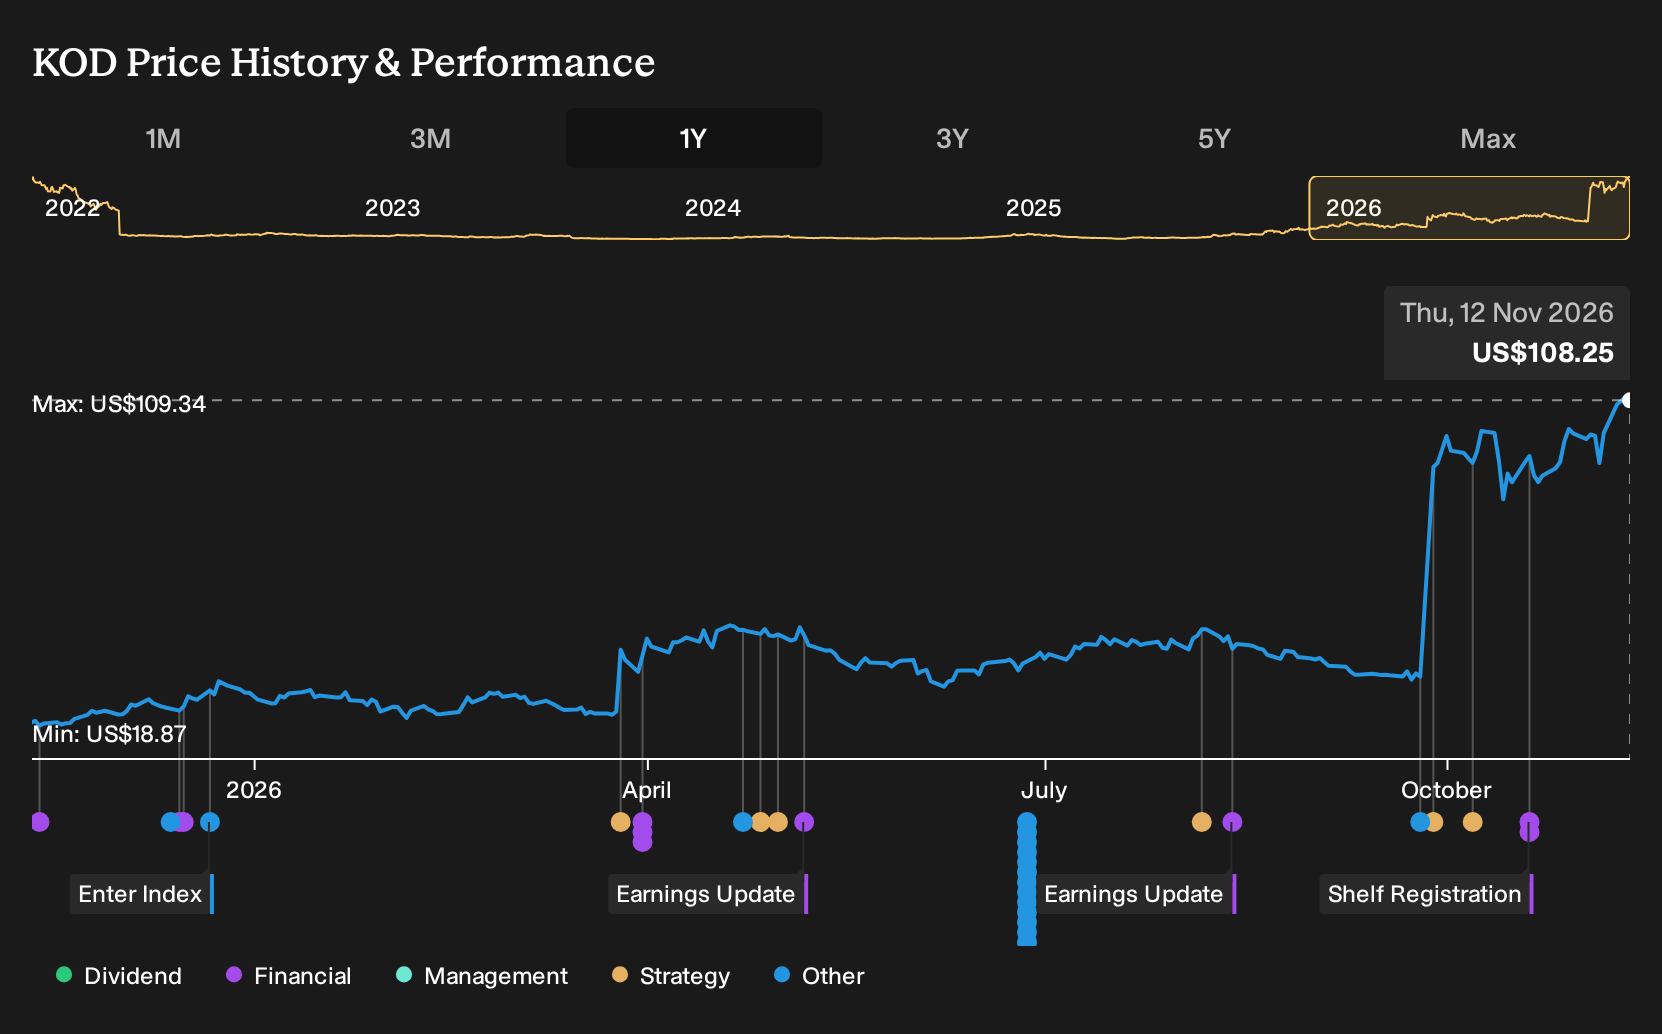
- Kodiak Sciences reported a third quarter 2026 net loss of US$66.22 million and a nine month loss of US$190.02 million while also highlighting positive Phase 3 data for retinal drug candidates Zenkuda and tabirafusp ted.
- The combination of widening losses and late stage trial success puts Kodiak Sciences at an inflection point, where clinical execution, regulatory filings and eventual commercial ramp need to justify ongoing heavy R&D spending.
- This article examines how Kodiak Sciences' investment narrative is shaped by the positive Phase 3 results for Zenkuda.
Compare Kodiak Sciences' high-cost R&D story with other late-stage biotech plays by scanning our curated list of 35 healthcare AI stocks, which are also pushing hard on next-generation therapies.
Kodiak Sciences Investment Narrative Recap
For Kodiak Sciences, the central belief is that a high burn rate today can eventually be supported by a multi drug retina franchise built around Zenkuda, tabirafusp ted and KSI 101. The latest quarterly loss of US$66.22 million reinforces that this is still a pre revenue, R&D heavy story. The main near term catalyst remains successful regulatory progress for Zenkuda and clear timelines on commercialization.
The biggest current risk is that operating expenses stay high while any revenue start is pushed out, which could mean continued heavy losses and potential reliance on external funding. The analyst consensus Narrative on Simply Wall St already highlights this funding and profitability uncertainty, so the latest earnings numbers mainly reinforce existing concerns rather than change them.
The multi indication BLA plan for Zenkuda, expected by the end of 2026, is the announcement that ties closest to the current earnings discussion. Positive Phase 3 data paired with that filing timeline keeps the focus on execution, because Kodiak Sciences needs to convert clinical success into regulatory milestones to justify ongoing spending.
Those filings, along with upcoming KSI 101 Phase 3 readouts, shape the operational outlook more than short term share price moves. If the business hits those clinical and regulatory dates on schedule, it could address the pre revenue risk that the analyst consensus Narrative on Simply Wall St flags. Missed timelines or mixed data would make the widening losses far harder for investors to accept.
Kodiak Sciences’ current analyst narrative points to forecast revenue of US$697.3 million and earnings of US$248.7 million by 2029. This implies a very large yearly step up from zero revenue today and an earnings swing of about US$490.7 million from a loss of US$242.0 million.
Uncover why Kodiak Sciences' fair value indicates a 12% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts frame Zenkuda’s multi indication BLA as the real swing factor for Kodiak Sciences, rather than the rising R&D losses you just saw. Before this news, the bullish camp was already sketching out about US$905.2 million of 2029 revenue and US$434.6 million of earnings. You can now judge whether today’s Phase 3 and earnings updates eventually push those narratives higher, lower, or in a completely different direction.
Explore another Kodiak Sciences fair value estimate, including one that suggests potential upside of up to 593% from the current price!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Kodiak Sciences research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Kodiak Sciences. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Kodiak Sciences' overall financial health at a glance.
Looking For More Investment Ideas Beyond Kodiak Sciences?
If the Kodiak Sciences story has you thinking about position sizing, risk and upside across your wider portfolio, it can help to line it up against other opportunities that fit different roles. The Simply Wall St Screener lets you quickly scan for shares that match clear, fundamentals based criteria so you can balance higher risk biotech exposure with steadier or more cash generative holdings.
- For investors who want potential upside but still care about balance sheet strength, check out our list of solid balance sheet and fundamentals (23 results) that can help you anchor a more resilient portfolio.
- If your priority is keeping overall risk in check while you take a swing on Kodiak Sciences, you can offset it with a 29 resilient stocks with low risk scores that focus on steadier business profiles.
- When you are hunting for fresh opportunities that the market may not be paying much attention to yet, scan the 20 high quality undiscovered gems that pair stronger fundamentals with lower visibility.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com