
Takara Holdings (TSE:2531) Faces A Valuation Test As ValueAct Pushes For A Board Overhaul
Takara Holdings (TSE:2531) has been pulled into the spotlight after activist investor ValueAct Japan Master Fund pushed for an Extraordinary General Meeting to replace three directors with its own nominees.
Takara Holdings' share price has climbed 72.53% year to date, with a 35.06% 90 day share price return and a 91.89% total shareholder return over the past year. The recent pullback over the last week suggests momentum is being tested as investors weigh the activist led EGM against that strong run up.
Scan how other alcohol, food and consumer stocks are reacting to similar activist pressure by reviewing the hand picked 20 resilient stocks with low risk scores alongside Takara Holdings.
After a 91.89% one year total return and an activist driven EGM on the way, Takara Holdings now forces a choice: do you pay up today or wait for a cooler entry before the valuation work starts?
Preferred P/E of 30.3x: Is it justified?
Tahara Holdings closed at ¥2,795, and the current P/E of 30.3x implies investors are willing to pay a premium relative to earnings compared with much of the Asian beverage space.
The P/E ratio compares the share price to earnings per share and helps you see how much the market is paying for each unit of profit. For a group like Takara Holdings that mixes alcohol, seasonings and biotech, P/E often becomes the shorthand for how much confidence investors have in the profit stream holding up.
Earnings quality is flagged as high and net profit margins of 4.2% are higher than the previous year at 3.4%. This can support a richer multiple in the near term. At the same time, earnings declined by 9.6% per year over the past 5 years even though profit grew 38.1% in the most recent year and exceeded the Beverage industry 0.8%, so the current valuation asks you to focus more on the recent turnaround than on the longer record.
Relative pricing is punchy. The 30.3x P/E is described as expensive versus the Asian Beverage industry average of 17.2x, yet viewed as good value against a much higher peer average of 62.6x. This suggests investors are paying more than the broader industry but not as much as for some closer comparables.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-earnings of 30.3x (OVERVALUED)
Still, activist pressure could fail to shift Takara Holdings' direction in a meaningful way, and any disappointment around profit trends or biotech execution would quickly challenge the current premium story.
Find out about the key risks to this Takara Holdings narrative.
Another view on Takara Holdings' valuation
On a P/E basis Takara Holdings looks expensive, yet the SWS DCF model paints an even starker picture. With the shares at ¥2,795 and an estimated future cash flow value of ¥764.3, the DCF output points to a stock that screens as overvalued. Which signal should serve as the anchor?
Look into how the SWS DCF model arrives at its fair value.
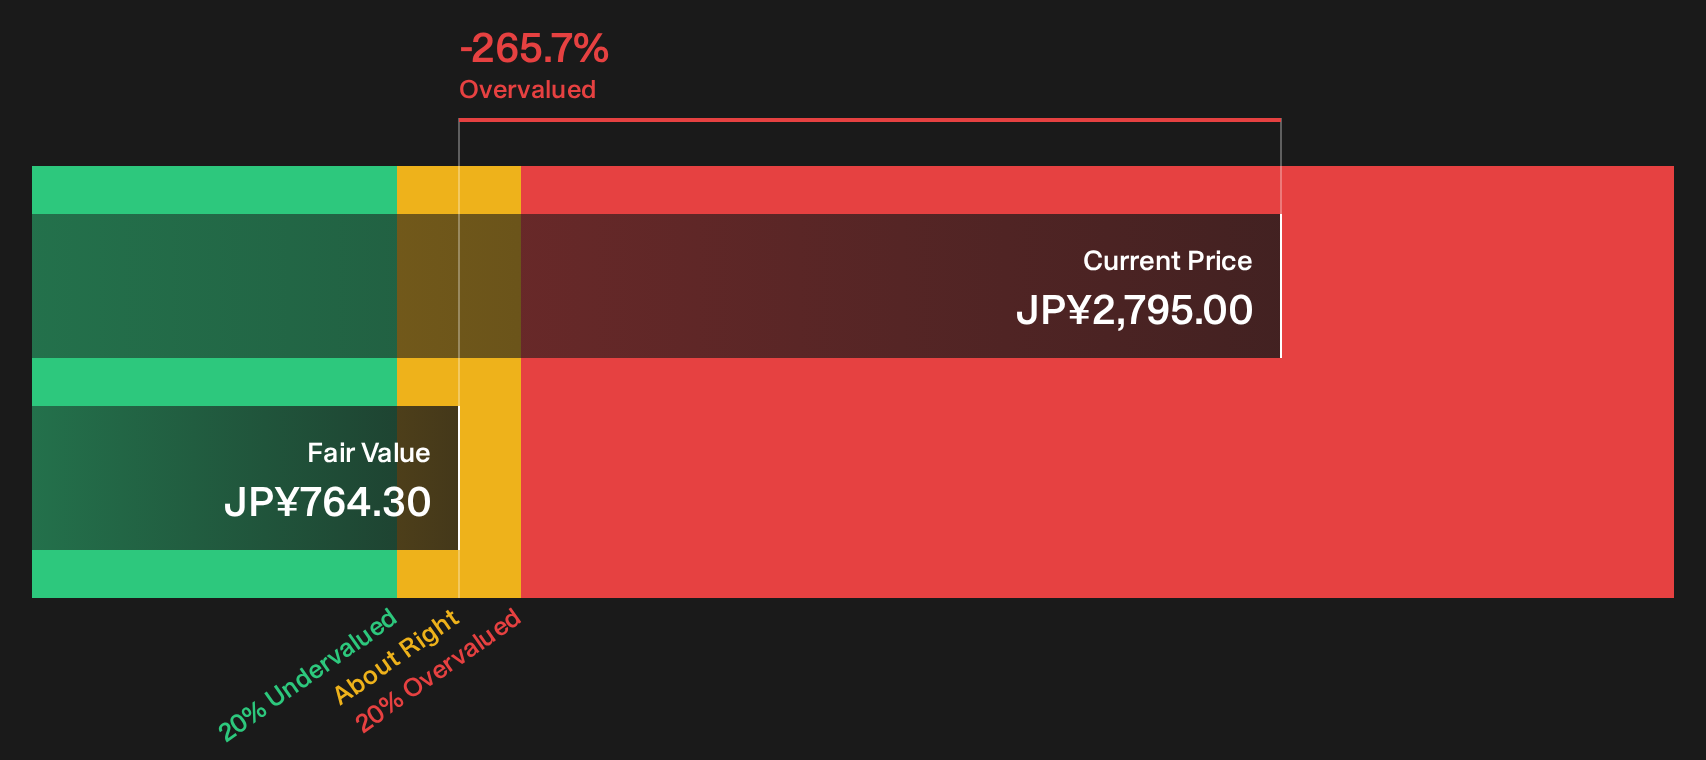
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Takara Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 19 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Takara Holdings can feel noisy, so move quickly to inspect the full risk and reward profile and shape your own view with the 1 key reward and 2 important warning signs.
Looking for more ideas beyond Takara Holdings?
You have seen how much hinges on valuation and expectations. Now widen the opportunity set and let data driven shortlists point you toward fresh prospects.
- Spot potential turnarounds before the crowd by scanning 72 high quality undiscovered gems that combine robust fundamentals with limited market attention.
- Focus on resilience and peace of mind through a list of solid balance sheet and fundamentals (24 results) that highlights companies with stronger financial footing.
- Target income focused opportunities using the 28 dividend fortresses to zero in on higher yielding payouts that might complement Takara Holdings in your portfolio.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com