
How Record Revenue At Ondas (ONDS) Has Changed Its Investment Story
- Ondas reported third quarter 2026 sales of US$167.49 million, compared with US$10.1 million a year earlier, alongside a wider quarterly net loss of US$62.57 million and basic loss per share from continuing operations of US$0.10.
- Across the first nine months of 2026, Ondas recorded sales of US$301.38 million and net income of US$212.14 million, supported by a backlog of about US$835 million and management guidance that now targets adjusted EBITDA profitability earlier than previously planned.
- The focus is now on how Ondas' record revenue and earlier adjusted EBITDA goals may reshape an investment narrative that had already appeared aggressive.
Scan how Ondas' surge in defense and autonomous systems contracts compares with other fast movers in the sector by reviewing our curated 86 robotics and automation stocks for your watchlist candidates.
Ondas Investment Narrative Recap
Owning Ondas means buying into a defense and autonomous systems platform that can turn its US$835 million backlog into consistent cash generation. According to DownUnder, an investor in the Simply Wall St Community, execution on integration and commercialization is the real test. Record Q3 and nine month revenue sharpen that focus. The key near term catalyst is management’s target for adjusted EBITDA profitability at the operating platform level, with the widened quarterly loss and production inefficiencies keeping margin execution firmly under the microscope.
The biggest immediate risk is operational strain from rapid scaling and acquisitions while shareholders have already experienced substantial dilution. Rising orders for ULTRA, IonStrike and other systems raise expectations but also execution pressure. If integration, production ramp and cost control fall behind the new revenue and profitability timelines, the investment case around Ondas’ platform ambitions weakens quickly.
The most relevant update is the Q3 2026 earnings release itself, where Ondas reported US$167.49 million in quarterly sales and US$301.38 million over nine months, alongside net income of US$212.14 million for that period and US$835 million in backlog. Management also pulled forward its company wide adjusted EBITDA profitability target to Q3 2027 and guided to at least US$550 million in 2026 revenue and US$1.1b in 2027.
For you as a shareholder or potential investor, that announcement tightens the link between contract wins and the main catalyst, which is proving Ondas can scale production and operations without further heavy dilution or persistent losses. The widened Q3 loss, lower recent share price performance and reliance on higher risk funding sources keep execution risk high. Progress against the adjusted EBITDA and delivery milestones is likely to drive how the Ondas story is viewed from here.
DownUnder assigns a fair value of US$7.89 per share for Ondas based on a scenario in which revenue expands 80.0% a year and the business ultimately achieves a 20.0% profit margin, together supporting a materially higher level of future earnings power in the narrative model.
Discover how Ondas' fair value indicates a 53% potential upside to its current price that may not last much longer.
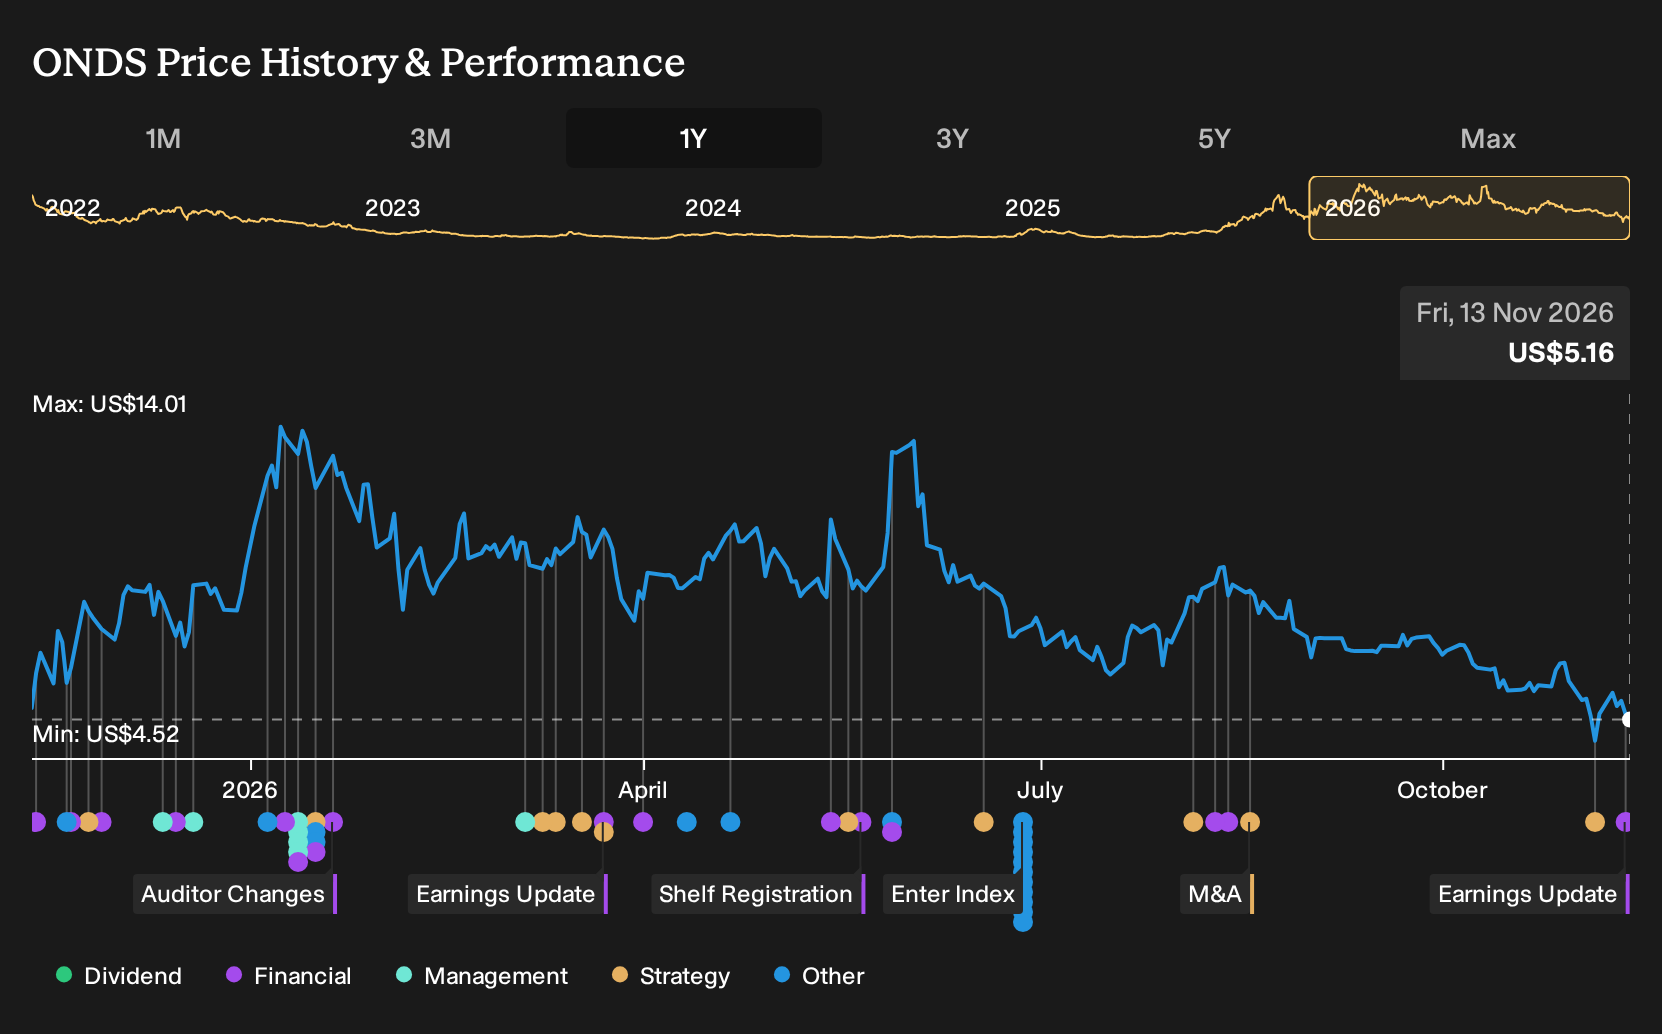
Exploring Other Perspectives
For Ondas, the biggest contrast comes from how bullish analysts treated the multi year backlog and more than US$11b pipeline as the main catalyst. Before this earnings release, some of them were pencilling in revenue of about US$2.2b and earnings near US$242.3m by 2029. Use this result as a fresh data point and explore how those views might shift.
Explore 8 other Ondas fair value estimates, including one that suggests a potential 396% increase from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own analysis carefully.
- A great starting point for your Ondas research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Ondas. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to evaluate Ondas' overall financial health at a glance.
Looking for more investment ideas beyond Ondas?
If the Ondas story has sharpened your focus on where risk, balance sheet strength and future potential intersect, you can use that same lens across the wider market with a few targeted screeners.
- If capital protection sits high on your list, you may wish to start with lower volatility candidates by reviewing a curated 29 resilient stocks with low risk scores that could better match your risk tolerance.
- If financial resilience matters most, you can filter for sturdier balance sheets through the list of solid balance sheet and fundamentals (23 results) to see which businesses pair stronger funding profiles with consistent fundamentals.
- If you want ideas the crowd may not be watching closely, you can broaden your watchlist with a focused 20 high quality undiscovered gems that highlights underfollowed companies with stronger underlying metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com