
U.S. Bancorp (USB) Has Investors Asking A Bigger Question
U.S. Bancorp (USB) has been busy on the funding side, repeatedly tapping debt markets with senior unsecured notes across a range of maturities and coupons. These bond moves give equity investors fresh information on balance sheet funding and capital planning.
Recent pricing shows some momentum rebuilding in U.S. Bancorp, with a 1-day share price return of 0.86%, a 7-day gain of 2.59% and a 30-day increase of 8.41%, even though the 90-day move is still down 6.77%.
That near term rebound sits on top of a 13.09% year to date share price return and a 1-year total shareholder return of 34.47%. Longer horizons remain meaningful, with 3-year and 5-year total shareholder returns of 84.11% and 31.94% respectively.
Against that backdrop, the recent wave of senior unsecured bond issuance, the acquisition of BTIG LLC to deepen capital markets capabilities, and expansion of the Middle Market banking team give investors more context for how U.S. Bancorp is funding growth initiatives and fee based revenue streams as sentiment improves.
Scan how U.S. Bancorp compares with other large financial institutions actively raising capital and reshaping fee income by running the list of solid balance sheet and fundamentals (24 results).
After a 34.47% 1 year total return and a fresh rebound off the recent 90 day pullback, the question for U.S. Bancorp now is whether meaningful upside still lies ahead, or if most of the easy money is already behind the stock as valuation comes into focus.
Most Popular Narrative: 11% Undervalued
U.S. Bancorp's most followed valuation narrative on Simply Wall St puts fair value at $68.50 compared with the recent $60.99 close, which points to upside according to the analyst consensus Narrative on Simply Wall St that blends Street forecasts with a discounted cash flow framework using a 7.56% discount rate.
U.S. Bancorp's earlier focus on payments volumes, trust and investment management fees is now supported by fee income at 44% of total revenue in 2Q26 and low teens fee growth year over year, including about 10% excluding BTIG. This points to a larger and more durable fee base that can support revenue and earnings mix over time.
See why 101 investors see U.S. Bancorp as 11% undervalued.
Result: Fair Value of $68.50 (UNDERVALUED)
Still, U.S. Bancorp’s story can break if fintech rivals chip away at payments fee pools or if commercial real estate credit losses rise faster than analysts expect.
Find out about the key risks to this U.S. Bancorp narrative.
Another View On U.S. Bancorp Valuation
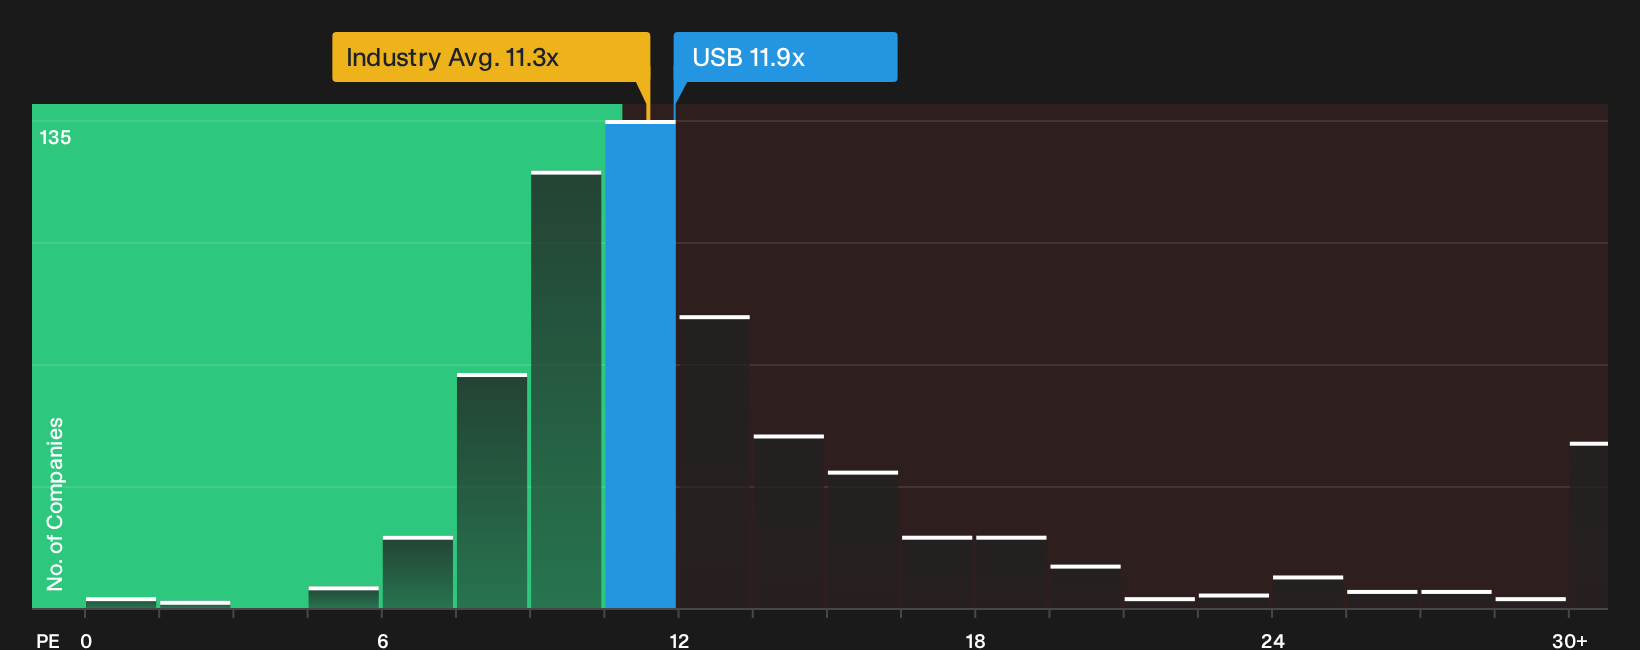
The first narrative leans on future earnings and a fair value of $68.50, yet the current P/E of 11.9x tells a more mixed story. U.S. Bancorp trades slightly richer than the US Banks industry at 11.3x, but cheaper than a 14x peer average and the 13.8x fair ratio. That mix points to some valuation risk if sentiment cools, and potential upside if the market edges closer to the fair ratio. Which side of that trade do you think dominates?
To pressure test that view against hard numbers, it helps to see how the price multiple compares in a fuller valuation breakdown, including the fair ratio gap and industry context, inside the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Curious whether the tone of this U.S. Bancorp story matches your own read of the numbers and recent moves? Move quickly, review the upside signals for yourself, and pressure test the optimism with the 4 key rewards.
Looking for more U.S. Bancorp style investment ideas?
If U.S. Bancorp has sharpened your appetite for fresh opportunities, do not stop here. Broaden your watchlist now and give yourself more options for the next move.
- Target potential mispricing and hunt for quality opportunities trading below intrinsic value with the 32 high quality undervalued stocks.
- Build a cash flow focused portfolio and zero in on income ideas with the 6 dividend fortresses.
- Reduce portfolio stress and concentrate on resilience by scanning our 31 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com