
AtkinsRéalis Group (TSX:ATRL) Could Be 22% Undervalued After Turkey Nuclear Agreement
Why the new Turkish nuclear agreement matters for AtkinsRéalis investors
Candu Energy's fresh memorandum of agreement with Turkey's national nuclear utility puts AtkinsRéalis Group (TSX:ATRL) at the center of a planned expansion of Turkey's reactor fleet and supporting supply chain.
The accord covers a feasibility study on deploying multiple CANDU units and building local manufacturing capacity, which ties directly into AtkinsRéalis Group's growing nuclear revenues and existing backlog monetization across its dedicated Nuclear segment.
Recent trading has been quietly positive for AtkinsRéalis Group, with a 1-day share price return of 1.33% and a 30-day share price return of 6.37%, helped by fresh contract wins like the Denver airport North Terminal program and a recently priced CA$400 million debenture issue that refines its funding mix. While the 1-year total shareholder return is almost flat at 0.14%, the 3-year total shareholder return of about 110% and 5-year total shareholder return of about 180% point to momentum that has built over time rather than faded. The CA$91.23 share price now reflects a market weighing new nuclear agreements against recent earnings and buyback activity.
Scan beyond AtkinsRéalis Group and compare this nuclear momentum with 16 nuclear energy infrastructure stocks.
AtkinsRéalis Group has a busy order book, rising nuclear exposure and fresh debt priced in at 4.062%. The real tension for investors now is simple: Does CA$91.23 still leave enough value on the table?
Most Popular Narrative: 22% Undervalued
AtkinsRéalis Group last traded at CA$91.23, while the most followed narrative on Simply Wall St pegs fair value at CA$117.29, using a discount rate of 8.24%. According to kapirey, an investor in the Simply Wall St Community who wrote that narrative, the appeal rests on a reshaped business mix and the role nuclear could play in future earnings power.
AtkinsRéalis represents a successful industrial transformation story, evolving from a higher-risk EPC contractor into a global, high-quality engineering and nuclear platform.
Structurally well-positioned, improved earnings quality and resilience, however: 👉 Increasing scrutiny on valuation and execution📌 Bottom Line: A high-quality company with strong long-term tailwinds, currently undergoing valuation consolidation. Attractive opportunity, particularly on pullbacks or with improved visibility on execution.
Find out how 5 investors see AtkinsRéalis Group as 22% undervalued.
Result: Fair Value of CA$117.29 (UNDERVALUED)
Still, the AtkinsRéalis story can break if execution slips on large projects or if government backed nuclear and infrastructure spending slows materially from current expectations.
Find out about the key risks to this AtkinsRéalis Group narrative.
Another view on AtkinsRéalis valuation
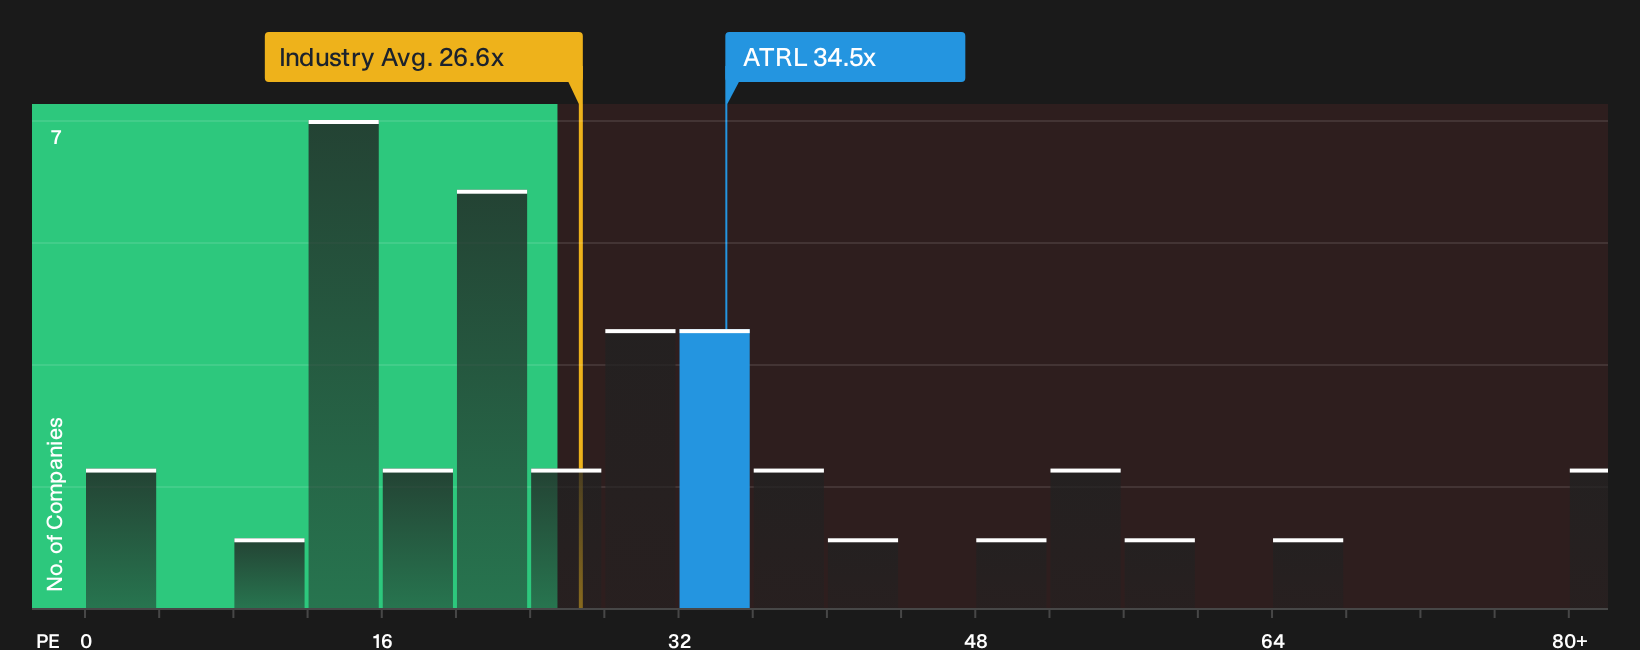
The community memo and analyst targets point to upside for AtkinsRéalis Group, yet the current P/E of 34.5x tells a different story. That ratio is higher than the North American Construction industry at 26.6x, peers at 33.9x, and even the 34.4x fair ratio our model suggests the market could gravitate toward. For investors, that gap looks less like a clear bargain and more like a question about how much future execution is already priced in.
If you want to see how that valuation stacks up in more detail, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the AtkinsRéalis story so far. If you want to move quickly and form your own view, start with the balance of 3 key rewards and 2 important warning signs
Looking for more investment ideas beyond AtkinsRéalis Group?
If AtkinsRéalis has sharpened your appetite for quality stories, do not stop here. Broader opportunity often hides where fewer investors are already looking.
- Target stronger balance sheets and steadier funding profiles by scanning a list of solid balance sheet and fundamentals (6 results). This can highlight companies that may be better positioned to handle tougher conditions without relying on hope.
- Hunt for mispriced opportunities and compare AtkinsRéalis against a 6 high quality undervalued stocks. This screens for quality with support from both cash flows and balance sheets.
- Prioritise resilience first and filter out fragile tickers by focusing on a 9 resilient stocks with low risk scores. This keeps potential downside on your radar before you commit.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com