
What Interparfums (IPAR)'s Raised Sales Outlook Means For Shareholders
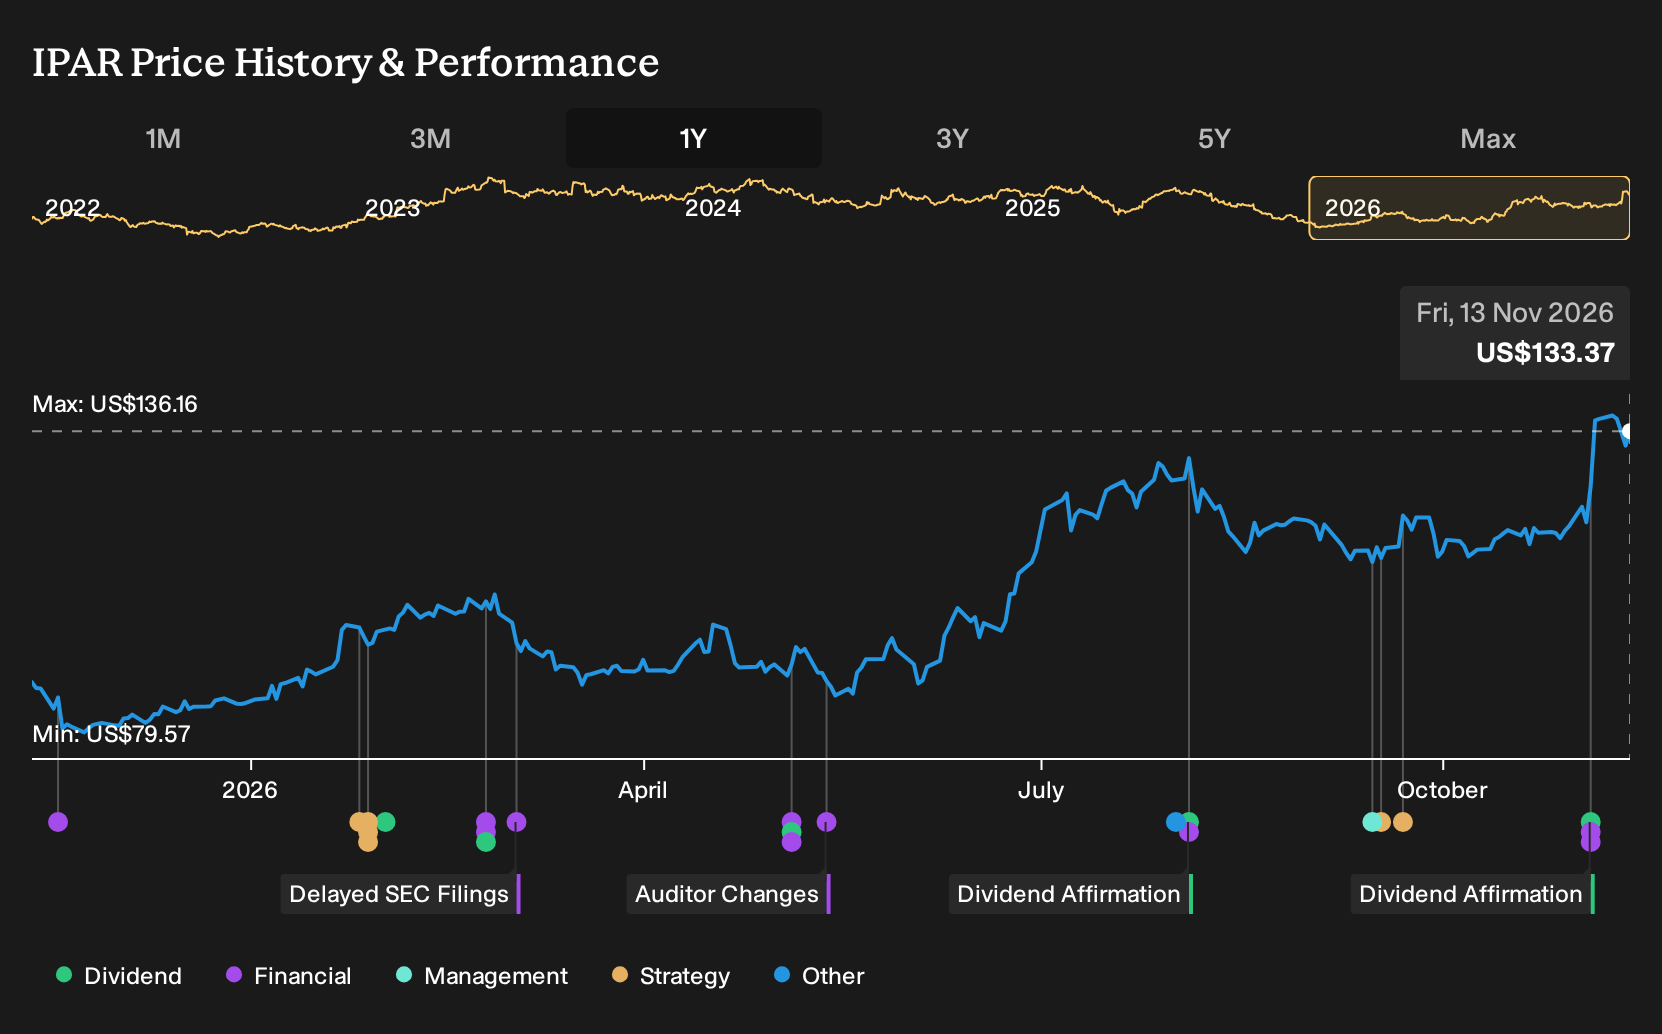
- Interparfums reported third quarter 2026 sales of US$429.51 million and net income of US$68.2 million, with earnings per share of US$2.13 and a confirmed US$0.80 quarterly dividend payable on December 31, 2026.
- The company lifted its 2026 sales outlook to US$1.49b while keeping EPS guidance unchanged, reflecting management’s confidence in demand and cost discipline despite higher spending and past regional pressures.
- The focus now turns to how Interparfums' higher 2026 sales guidance may influence the investment narrative around its margins and growth.
Interparfums Investment Narrative Recap
To own Interparfums, you need to believe that its portfolio of licensed prestige fragrances can keep pulling in steady demand while heavier advertising and logistics spending is kept under control. The latest quarter fits that picture. Sales and earnings per share were broadly in line with last year, which keeps the near term product cycle and margin story largely intact.
The analyst consensus narrative on Simply Wall St leans on higher digital and e commerce exposure, plus an off cycle 2026 ahead of planned blockbuster launches. The key short term swing factor remains whether elevated SG&A starts to compress profitability. Regional weakness linked to conflict exposed markets is still a live risk that this quarter did not resolve.
The most relevant update for that thesis is Interparfums’ decision to lift its 2026 sales outlook to US$1.49b while holding EPS guidance at US$4.85. That combination points to management planning for more volume but not baking in margin expansion yet, partly because guidance already reflects tariff refunds of about US$17.7 million.
For you as a shareholder, the catalyst to watch is whether upcoming product extensions and digital marketing can turn that higher top line ambition into firmer operating leverage. If advertising, royalties and logistics costs keep absorbing much of the revenue benefit, the risk flagged earlier that profitability stays pressured would remain front of mind.
Interparfums' narrative projects US$1.8b revenue and US$184.4 million earnings by 2029. This assumes revenue growth of 5.7% per year and an earnings increase of about US$16.6 million from current earnings of US$167.8 million.
Uncover why Interparfums' fair value indicates a 5% potential downside to its current price, suggesting a premium that may not be sustainable.
Exploring Other Perspectives
Some of the most optimistic analysts framed the key catalyst differently for Interparfums. They focused on the 7.3% revenue growth path they were using before this report and the US$209.8 million earnings estimate for 2029. You now get to decide whether the new sales guidance supports that upbeat story or pushes you to weigh alternative views.
Explore 4 other Interparfums fair value estimates, including one that suggests up to 49% upside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Interparfums research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Interparfums. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Interparfums' overall financial health at a glance.
Looking For More Investment Ideas Beyond Interparfums?
If the Interparfums story has sharpened your thinking about earnings quality, balance sheets and income streams, it can be useful to line it up against a wider set of candidates. The Simply Wall St Screener lets you quickly filter for traits you care about so you can build a watchlist that really matches your goals.
- For investors who care most about financial resilience and low volatility, start by scanning a 31 resilient stocks with low risk scores that can help you stress test your current ideas.
- If value is your main focus, compare Interparfums with a 32 high quality undervalued stocks that already combine quality fundamentals with pricing that may look appealing.
- For those leaning toward earlier stage opportunities, broaden your research with a 13 elite penny stocks with strong financials that filters for stronger balance sheets within the higher risk end of the market.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com