
Premium Brands Holdings (TSX:PBH) Stock Could Still Be A Bargain On Record Q3 Earnings
Premium Brands Holdings has seen its share price fall over a multi year stretch while still posting record earnings in recent updates, which raises a simple question for investors who follow the stock closely. Is the current price around $77.22 per share in line with what the company is actually earning today?
- Over the past 5 years the share price has fallen about 29.2%. This puts the spotlight on whether the current valuation still lines up with the company’s earnings profile.
- Recent record earnings, a fresh dividend declaration and a new share buyback program can support the idea that management expects its profit base and cash generation to carry more weight in how the stock is priced.
- Your read on Premium Brands Holdings is one view; the desks covering it have another. See what analysts think Premium Brands Holdings's shares could be worth.
The issue now is whether Premium Brands Holdings’ current share price is justified by its earnings when judged against the Fair Ratio benchmark.
If you want more than a single case study in how the market prices earnings, a focused screen of 6 high quality undervalued stocks can be a useful second starting point for your research.
Is Premium Brands Holdings Still Cheap on Earnings?
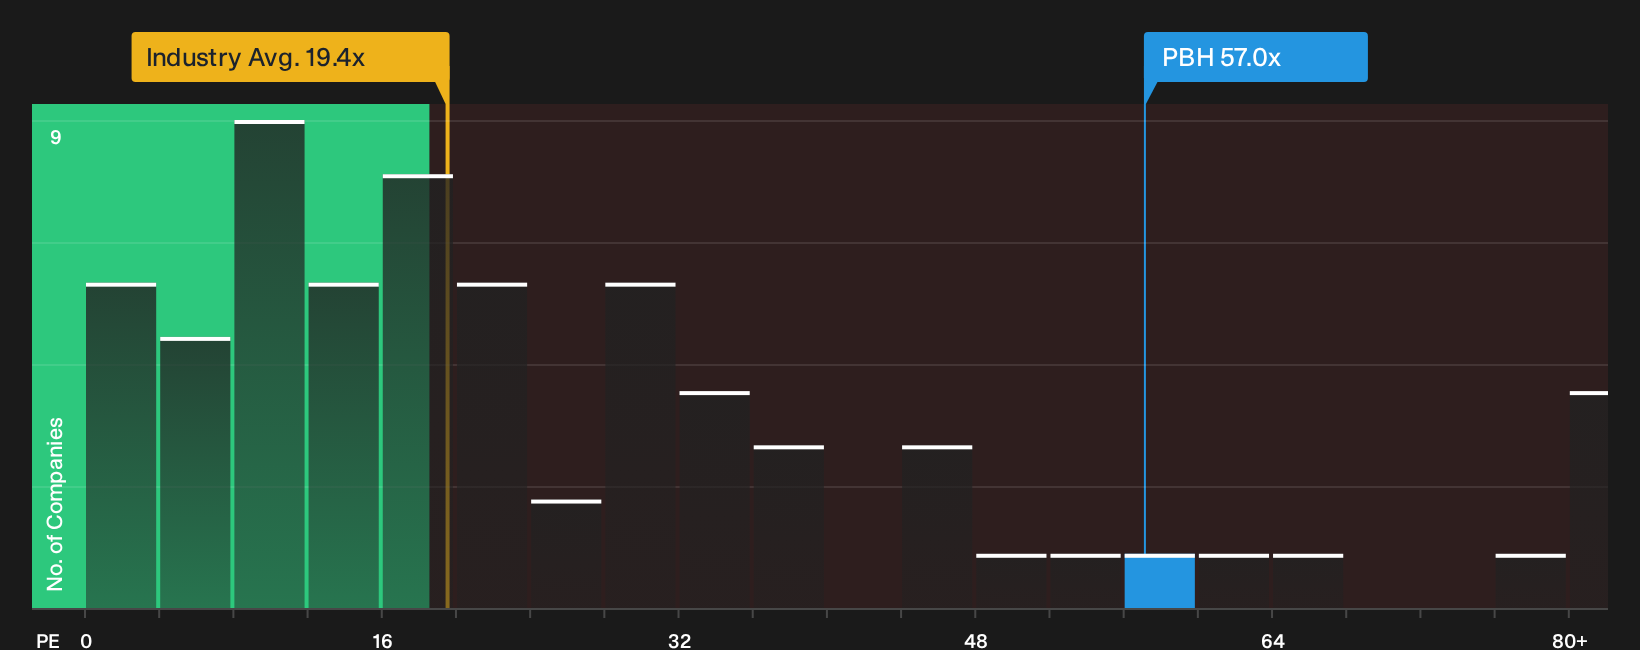
The P/E ratio fits Premium Brands Holdings well because earnings sit at the centre of how investors are currently judging it. On this measure, the stock trades on roughly 57.0x earnings, which is much higher than the Food industry average of about 14.7x and also above the broader peer group near 23.1x. That kind of gap indicates the market is willing to pay a rich price for each dollar of profit.
Record Q3 earnings and the new share buyback have helped reset sentiment, yet Premium Brands Holdings still trades below the multiple suggested by a Fair Ratio that blends its growth outlook, profitability, sector and risk profile. The current P/E sits under that tailored benchmark, which suggests the shares appear undervalued on this earnings lens once those fundamentals are taken into account. Explore the numbers behind Premium Brands Holdings's P/E valuation.
The Premium Brands Holdings Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Premium Brands Holdings pick up where the valuation puzzle leaves off by explaining which growth, margin and earnings paths would need to occur for the stock to be worth materially more or meaningfully less than it is today. Each narrative links a specific fair value estimate to a clear storyline about the company’s possible catalysts and key risks, so you can monitor over time which version of events is actually unfolding on the Community page.
One of the top narratives on Premium Brands Holdings: 28% undervalued
This Narrative is the analyst consensus Narrative on Simply Wall St, which compiles analysts' consensus price target and revenue and earnings forecasts, not one person's view.
"The main thing that has to go right is that Premium Brands Holdings successfully fills the more than $2b of added sales capacity with profitable volume..."
Discover why this Narrative puts Premium Brands Holdings at 28% undervalued.
Premium Brands Holdings has one more piece of the puzzle to check
Before you lean too heavily on what the current P/E and narratives suggest, it is worth pausing on the specific concerns our checks have picked up and weighing how they fit your own risk tolerance. Take a closer look at 4 warning signs (1 major) before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com