
First Solar (FSLR) Stock Looks Cheap Even After A 58% Gain
First Solar has seen its share price fall sharply this year, yet over a longer stretch holders are still sitting on sizeable gains. This puts a spotlight on one question for you as an investor: Is the current US$171.39 price tag adequately grounded in what the business earns today and what its profits may support over time?
- The stock is up 58.2% over 5 years, which raises the issue of how much of that gain can be explained by the company’s earnings power rather than changing sentiment alone.
- Recent political support for clean energy, including expectations for favorable tax credits and domestic manufacturing incentives, can influence how reliable and long lived First Solar’s future earnings stream may be.
- Your read on First Solar is one view; the desks covering it have another. See what analysts think First Solar's shares could be worth.
The stock’s next move may depend on whether today’s valuation is fully justified by First Solar’s earnings profile.
If you want a wider lens on renewable energy alongside First Solar, consider using a focused stock screen of 43 power grid technology and infrastructure stocks.
Is First Solar Still Cheap on Earnings?
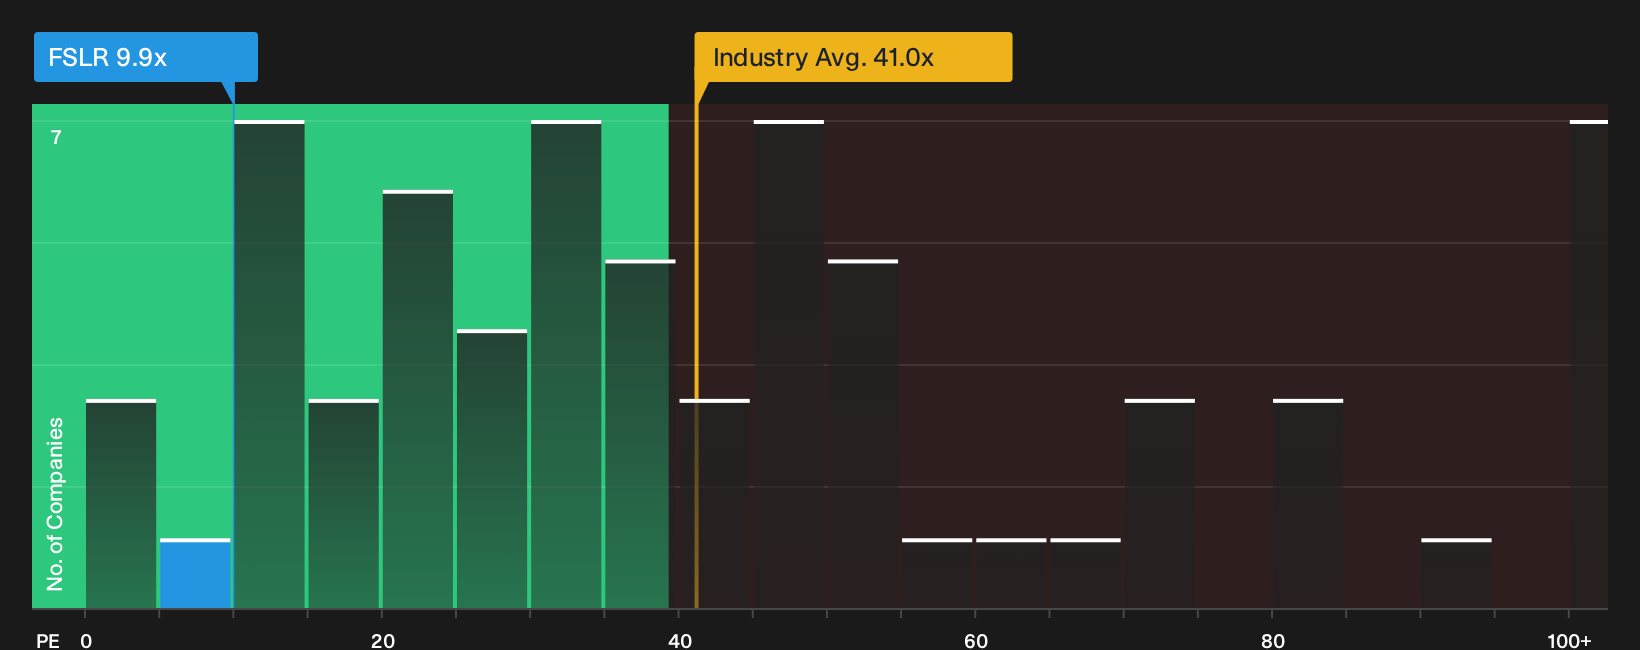
The P/E ratio suits First Solar because earnings anchor directly to what you are paying for each dollar of profit. At about 9.9x, the stock trades far below the broader Semiconductor group on roughly 41.0x and also below the peer average near 64.4x. Because the current multiple sits under the tailored fair P/E that factors in First Solar’s margins, growth profile, size and risk, the shares screen as undervalued on this lens.
Because the Democratic election sweep previously lifted sentiment around clean energy policy support, it is striking that First Solar still changes hands on a P/E that implies a discount to many semiconductor peers. That gap leaves you asking whether the political tailwinds and contracted backlog are fully recognised in the current price or whether investors remain cautious about how consistently future earnings will convert into cash flows. Explore the numbers behind First Solar's P/E valuation.
The First Solar Narrative: What Would Justify Today's Price?
First Solar Narratives on Simply Wall St pick up where the P/E puzzle leaves off. They spell out which paths for growth, profitability and earnings would need to hold for the stock to justify a meaningfully higher or lower price than today. Each one also frames a fair value as a thesis about the business that you can track over time on the Community page to see how it holds up against new information.
One of the top narratives on First Solar: 33% undervalued
This analyst consensus Narrative on Simply Wall St compiles Wall Street price targets plus revenue and earnings forecasts into a single storyline for First Solar.
"The main thing that has to go right is that First Solar converts its large U.S. centric backlog and CuRe and perovskite technology roadmap into profitable long term production…"
Discover why this Narrative puts First Solar at 33% undervalued.
One more First Solar check that sits beside the current share price
Price multiples and narratives tell you what is baked in today. Yet one missing piece is how professional analysts currently map First Solar’s profits a few years out compared with this market tag. Explore where analysts expect First Solar to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com