
Patrick Industries (PATK) Lifts Capital Returns As The Undervalued Case Stays In Focus
Patrick Industries (PATK) just raised its regular quarterly cash dividend to US$0.52 per share and refreshed its share repurchase authorization to US$200 million, moves that spotlight management’s current capital return priorities.
The recent capital return announcement comes after a sharp 30-day share price gain of 27.45%. However, the stock is still down 26.93% on a year-to-date share price basis, and the 1-year total shareholder return is down 17.79%, while the 5-year total shareholder return stands at 67.42%. This suggests renewed momentum but a mixed experience for long-term holders.
Spot emerging capital return stories like Patrick Industries by scanning our hand-picked 6 dividend fortresses that pair income with robust fundamentals.Patrick Industries has already rewarded traders who caught the recent swing, yet the richer dividend and fresh buyback authorization hint that the debate is not over. Is most of the upside already priced in, or is there still value on the table?
Most Popular Patrick Industries Narrative: 20% Undervalued
The analyst consensus Narrative on Simply Wall St points to a fair value of about $100.82 for Patrick Industries, which sits well above the recent $80.69 close, so the current debate centers on whether the market is underestimating the long term effect of diversification and the LCI merger.
Expansion of Patrick Industries into Marine, Powersports and Housing, where recent growth has helped offset weaker RV revenue while RV and Marine wholesale shipments remain more than 20% below 2019 levels, supports the case for a larger and more resilient revenue base as these end markets continue to contribute a greater share of sales and earnings.
See why 2 investors see Patrick Industries as 20% undervalued.
Result: Fair Value of $100.82 (UNDERVALUED)
Still, the Patrick Industries story can break if RV demand stays soft for longer, or if the LCI merger synergies and margin lift prove harder to capture.
Find out about the key risks to this Patrick Industries narrative.
Another View: Patrick Industries On Earnings Multiples
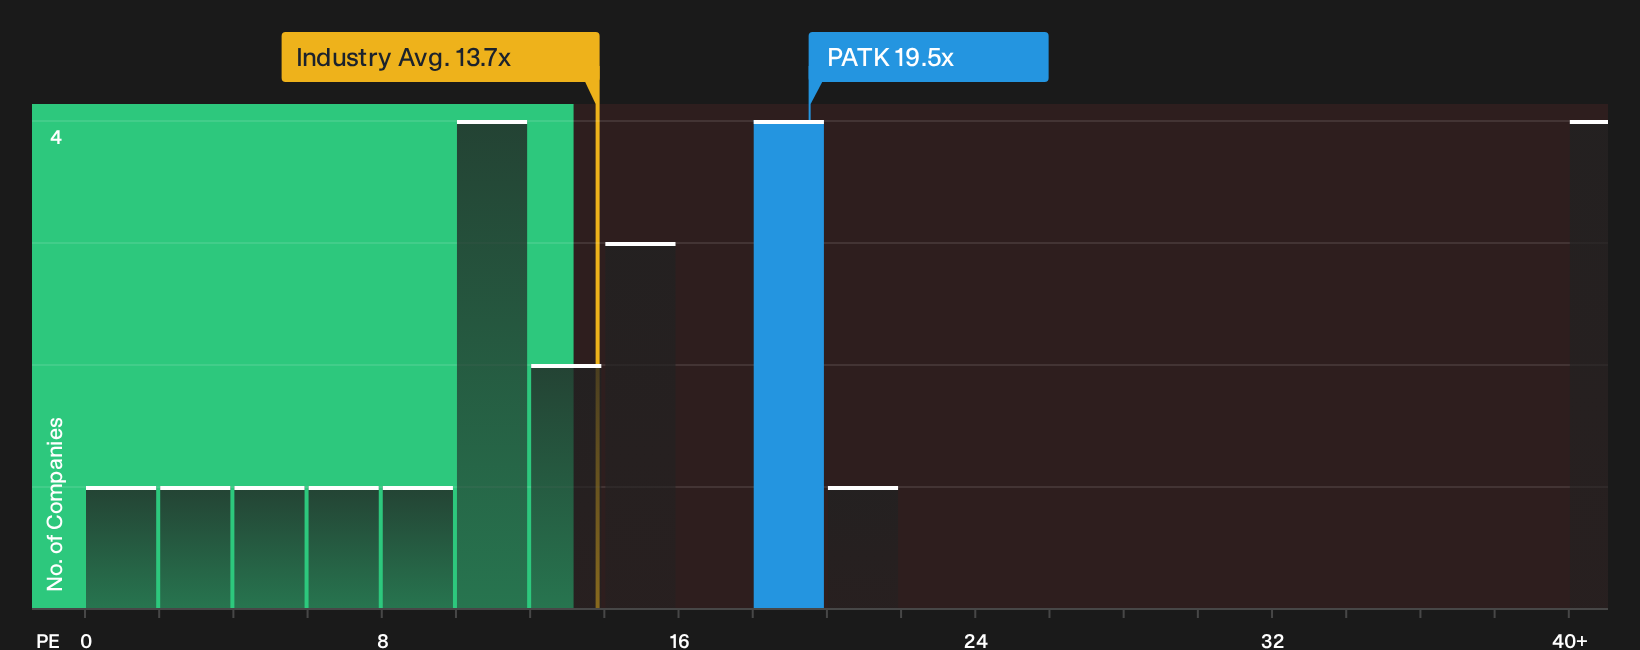
The DCF workup points to Patrick Industries trading well below an estimated future cash flow value, yet the earnings multiple paints a tougher picture. The stock changes hands at about 19.5x P/E, compared with 13.7x for the North American Auto Components group and a fair ratio of 14.7x, which suggests investors are already paying a premium that could limit upside if growth or margins disappoint.
Put differently, the SWS fair ratio implies the market could drift toward a lower P/E over time, which would pressure returns unless earnings keep pace. For anyone weighing up that trade off, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals like these can leave Patrick Industries looking either appealing or risky depending on what you focus on. Act while the information is fresh and weigh both sides of the argument by reviewing the 4 key rewards and 1 important warning sign
Looking for more investment ideas beyond Patrick Industries?
If Patrick Industries has sharpened your focus, do not stop here. Broader idea hunting often reveals opportunities that line up even better with your goals.
- Target steadier compounding potential by scanning a 31 resilient stocks with low risk scores that screens for businesses with resilient profiles.
- Hunt for mispriced quality by reviewing a 20 high quality undiscovered gems that highlights under-the-radar companies with strong fundamentals.
- Build a more defensive income stream by checking a list of solid balance sheet and fundamentals (24 results) that filters for companies combining financial strength with dependable operations.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com