
Valaris (VAL) Could Be 21% Above Fair Value After Softer Quarterly Earnings
Valaris (VAL) just posted third quarter results that showed revenue of US$593.6 million and net income of US$46.1 million, with earnings per share from continuing operations at US$0.66.
The softer third quarter earnings landed against a backdrop where Valaris has still delivered a strong year to date, with a 61.34% year to date share price return and a 47.54% one year total shareholder return. However, recent 30 and 90 day share price returns show momentum easing after that strong run.
Compare Valaris's recent pullback after softer earnings with other hand picked opportunities in offshore energy and resources by scanning the 32 high quality undervalued stocks for potential value ideas in the same broader space.
Valaris has cooled off after a strong run, and softer earnings have taken some heat out of the share price. Is that pullback already reflecting the risk, or is patience for a better entry still worth considering?
Most Popular Narrative: 21% Overvalued
On the analyst consensus Narrative on Simply Wall St, Valaris has an implied fair value of $69.71 compared with a last close of $84.14. This frames the recent pullback as only a partial reset against earlier optimism. That perspective leans heavily on how much of the Transocean deal upside is already embedded in today's valuation and what actually needs to happen operationally to justify it.
The all stock merger with Transocean is being sold as transformational, with more than US$200 million of annual cost synergies, a pro forma backlog above US$10b and a targeted leverage ratio of about 1.5x within 24 months of closing. However, the stock already prices in substantial value from those integration benefits that are still to be realised in future margins, earnings and cash flow.
See why 31 investors see Valaris as 21% overvalued.
Result: Fair Value of $69.71 (OVERVALUED)
Still, a faster than expected pickup in offshore project awards, or smoother progress on the Transocean merger, could challenge the idea that Valaris is meaningfully overvalued.
Find out about the key risks to this Valaris narrative.
Another View: What Valaris Looks Like On Earnings Multiples
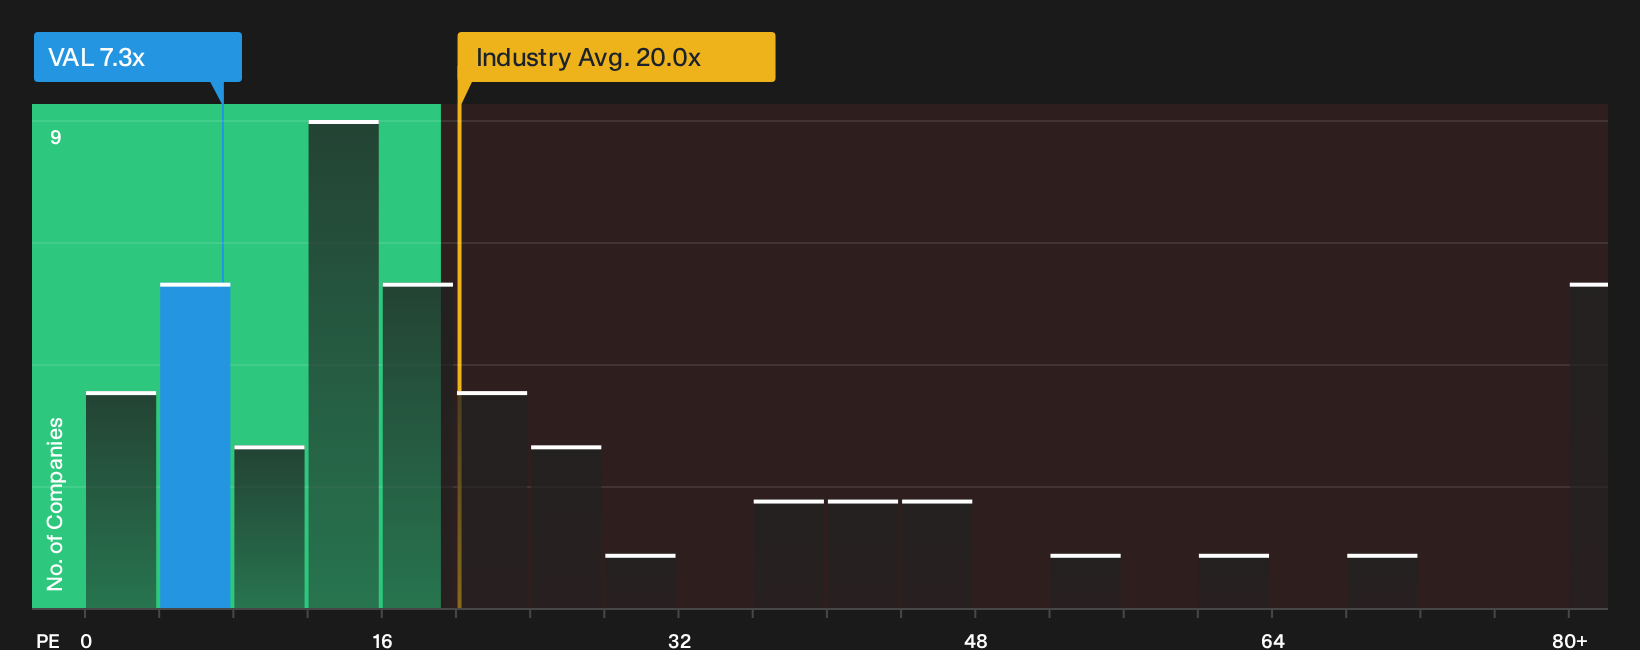
Analyst targets suggest Valaris trades above fair value, yet the current P/E of 7.3x tells a different story. The broader US Energy Services group sits at roughly 20x, while a fair ratio of 7x implies only a small premium over that benchmark risk. Is the crowd overstating the downside?
Our P/E work compares Valaris with both peers and that fair ratio. This helps you judge whether today’s pricing feels stretched or still leaves room for a rerating. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Opinion on Valaris appears divided following these results. If you want to move past the headline reactions, consider the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Valaris?
Do not stop your research with Valaris. Fresh opportunities often show up where pricing, quality and risk look different to the story you just read.
- Target steadier opportunities by scanning a 31 resilient stocks with low risk scores that aims to keep volatility and balance sheet stress in check.
- Hunt for stronger fundamentals with a list of solid balance sheet and fundamentals (24 results) that can help you focus on financial resilience instead of headlines.
- Spot potential future leaders early by checking a 20 high quality undiscovered gems before wider market attention arrives.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com