
Pfizer (PFE) Stock Looks Above Fair Value As Shares Rebound
Pfizer has climbed back this year after a difficult five year stretch, which raises a simple question for anyone looking at the ticker today. Is the current share price properly supported by the earnings power of the business.
- The stock is down 25.5% over five years, which puts extra weight on whether the current earnings justify even a partial rebuild in investor confidence.
- The recent obesity partnership with Blackstone Life Sciences, which can shift development spending and future cash flows for Pfizer, may support a different trajectory for profit generation than investors have been used to.
- Your read on Pfizer is one view; the desks covering it have another. See what analysts think Pfizer's shares could be worth.
The issue now is whether the earnings that Pfizer generates today, and what analysts expect it to produce over time, are strong enough to support where the shares currently trade.
If you are weighing Pfizer against other opportunities tied to healthcare breakthroughs, a focused stock screen of 36 healthcare AI stocks is a clean way to widen your research starting point.
Does Pfizer Look Pricey on Earnings?
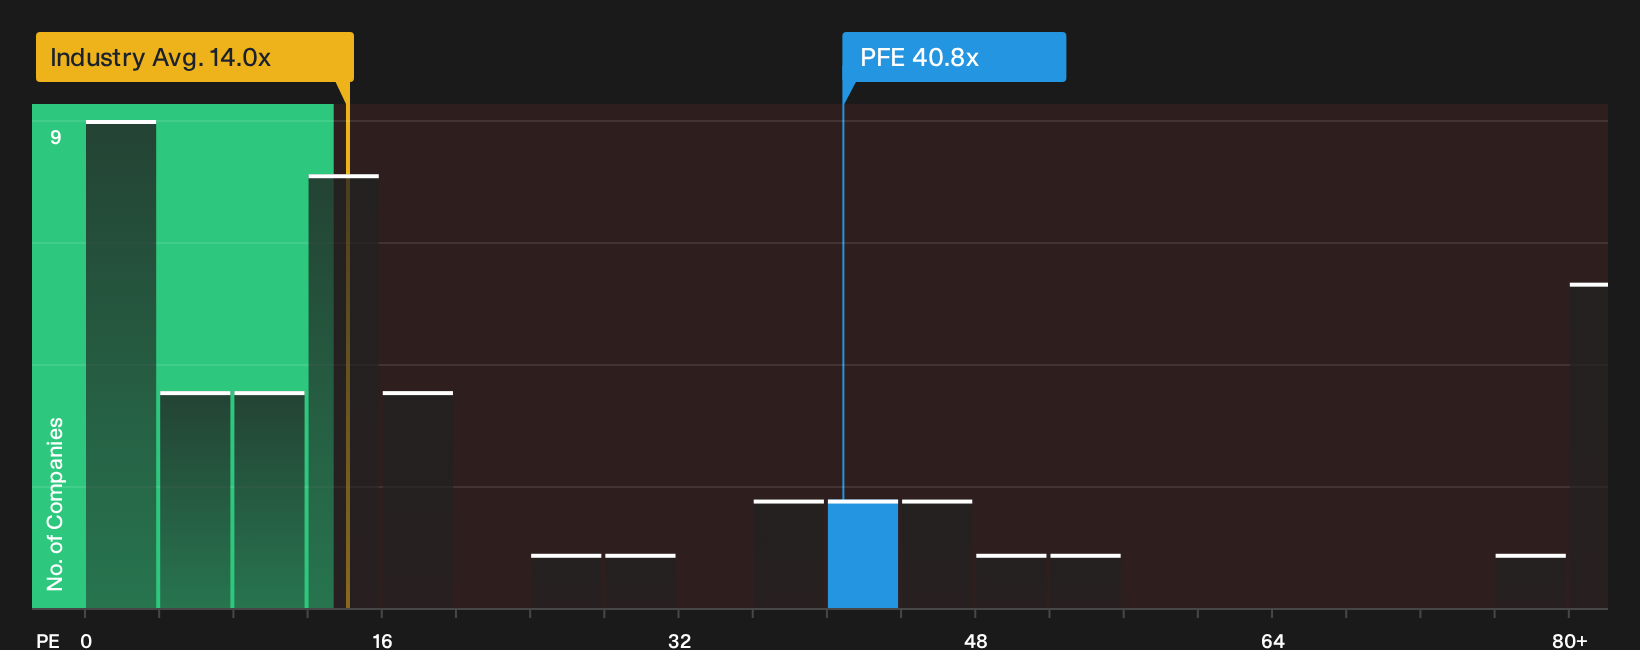
For Pfizer, the P/E ratio is the cleanest way to see what investors are paying for each dollar of current earnings. The stock trades around 40.8x, which is far above the Pharmaceuticals sector average of about 14.0x and also well below a peer group average that sits closer to 77.0x. That mix indicates the market assigns a rich earnings tag versus the broader industry, but not the highest rating in its immediate large cap peer set.
Within this framework, a tailored fair P/E that blends Pfizer’s risk profile, margins and scale screens lower than the present 40.8x, so the shares appear overvalued on earnings using this lens. Because the recent obesity partnership with Blackstone Life Sciences channels external capital into a key pipeline project, the market may be comfortable paying a premium multiple for Pfizer’s profit stream. Explore the numbers behind Pfizer's P/E valuation.
The Pfizer Narrative: What Would Justify Today's Price?
Pfizer’s Simply Wall St Narratives pick up where the valuation puzzle leaves off. They spell out which paths for future growth, profitability and earnings would need to play out for the stock to look meaningfully under or over priced relative to today’s P/E. Each narrative links its number to a specific view on how Pfizer’s growth, margins and risk profile could evolve, giving you something concrete to revisit as fresh information comes through.
Bulls see more long term earnings power in Pfizer than bears, who focus on execution risks and the transition away from COVID cash flows.
Bull case: roughly fairly valued
The analyst consensus Narrative on Simply Wall St ties its constructive view on Pfizer to execution on cost savings and new therapy launches.
"Execution on large scale productivity and manufacturing programs, now expected to deliver about US$9.7b in net savings through 2029 after already removing US$7.2b from the cost base…"
Discover why this Narrative puts Pfizer at roughly fairly valued.
Bear case: roughly fairly valued
According to Valrodmon, an investor in the Simply Wall St Community, the risk hinges on how Pfizer handles COVID revenue decline and the patent cliff.
"O 'patent cliff' maior se concentra entre 2026-2030, com até US$ 17-18 bilhões em receitas anuais em risco de drogas como Eliquis, Vyndaqel, Prevnar, Ibrance e Xtandi enfrentando genéricos…"
Explore why this Narrative puts Pfizer at roughly fairly valued.
Pfizer’s valuation still leaves one crucial loose end
Price and earnings only tell part of the story for Pfizer, because our broader checks have flagged specific risk indicators that deserve a closer look before you form a view on the stock. Take a closer look at 4 warning signs before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com