
Learn Why The Bull Case For Colliers International Group Stock Could Change Following Lowered Revenue Outlook
- Colliers International Group reported Q3 2026 results with sales of US$1,637.64 million and net income of US$6.96 million, alongside lower earnings per share versus the prior year.
- The company paired higher year to date revenue of US$4,523.61 million with much thinner profitability and reduced full year 2026 revenue growth guidance to the low teens.
- This article will now explore how Colliers International Group's thinner profitability and trimmed revenue outlook could reshape its broader investment narrative.
Stress test your thesis on Colliers International Group by comparing it with 6 high quality undervalued stocks, which pairs revenue growth with stronger profitability profiles.
Colliers International Group Investment Narrative Recap
To own Colliers International Group you need to be comfortable with a story where higher sales do not automatically translate into healthy earnings. The recent quarter showed US$1,637.64 million of revenue but only US$6.96 million of net income and lower earnings per share than a year ago. That thinner profitability, combined with debt that is not well covered by operating cash flow, keeps balance sheet risk near the front of the investment case.
The trimmed full year 2026 revenue outlook to low teens growth also matters for near term sentiment. The analyst consensus Narrative on Simply Wall St leans on earnings expansion from diversification, digital efficiency and acquisitions. The obvious short term catalyst is any sign that margins stabilize while industrial leasing and investment management fundraising stop dragging. The biggest risk is that weaker leasing and ongoing fundraising pressure keep profit margins under strain for longer.
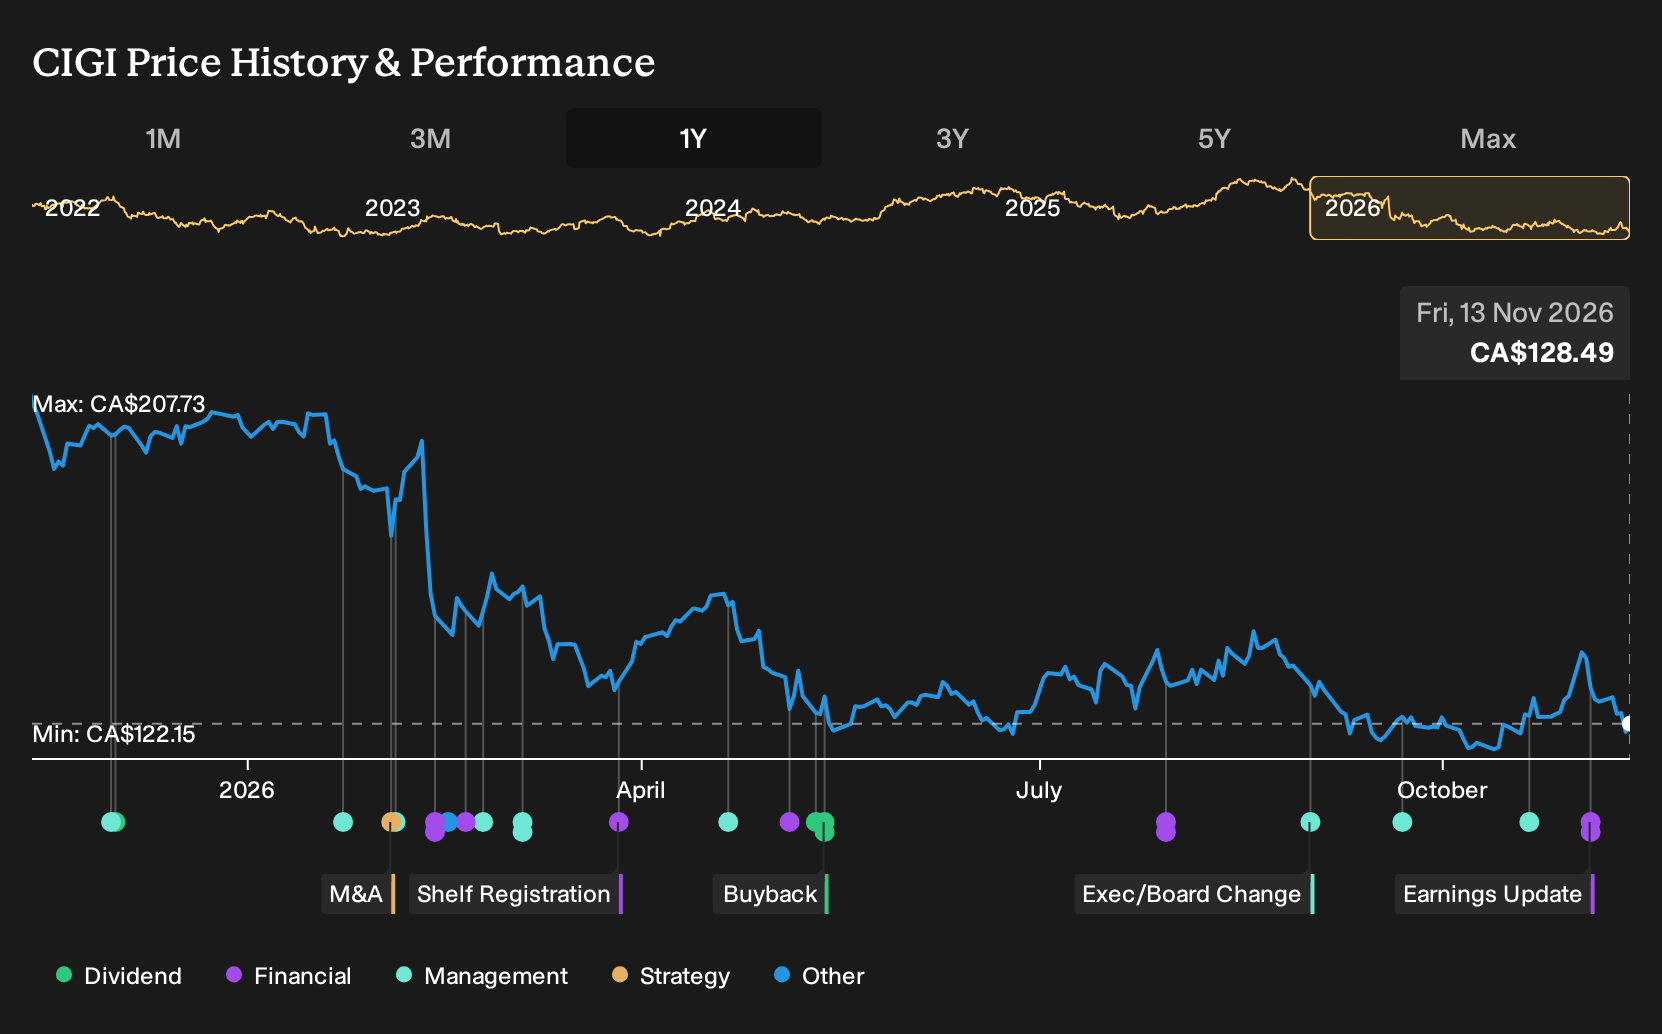
The guidance cut on 4 November 2026 is the announcement that ties everything together. Management shifted expected 2026 revenue growth from mid teens to low teens on the same day Colliers International Group reported sharply thinner earnings despite higher year to date sales of US$4,523.61 million. That combination pulls investor focus toward execution quality rather than headline growth.
For a shareholder, this update directly interacts with the catalysts in the analyst consensus Narrative on Simply Wall St. That story leans on recurring fees from investment management, engineering backlogs and outsourcing services to support margin improvement over time. With profit margins already down from 2.1% to 1.2% and leverage flagged as a risk, the revised outlook raises the bar on how cleanly Colliers converts every incremental dollar of revenue into sustainable cash generation.
Colliers International Group's current earnings sit at $107.8 million, with analyst consensus pointing to $185.4 million of earnings and $7.7 billion of revenue by 2029. That profile implies 8.7% yearly revenue growth and an earnings increase of about $77.6 million from today's level to the 2029 forecast.
Uncover why Colliers International Group's fair value indicates a 66% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
You can read Colliers International Group through a different lens if you focus on the bearish concern that outsourcing contracts remain highly price driven. The most pessimistic analysts were already assuming a cooler 7.2% yearly revenue path toward about US$7.5b and US$198.7 million of earnings by 2029. This earnings miss and softer guidance could push those expectations and your own narrative even lower, so it is worth comparing how your view lines up with both the cautious and optimistic ends of the range.
Explore 3 other Colliers International Group fair value estimates, including one that suggests it could be worth just CA$158.94!
The Verdict Is Yours
Don't just follow the ticker, dig into the data and build a conviction that's truly your own.
- A great starting point for your Colliers International Group research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Colliers International Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Colliers International Group's overall financial health at a glance.
Looking For More Investment Ideas Beyond Colliers International Group?
If this Colliers International Group update has sharpened your thinking, you can use that same lens to scan a wider field of opportunities. The Simply Wall St Screener can help you quickly filter for businesses that better match your risk tolerance, income needs or balance sheet preferences.
- If capital preservation is your priority, you could start with sturdier balance sheets and filter for companies in the 9 resilient stocks with low risk scores to see which ones align with your comfort level.
- Income focused investors can tune their shortlist toward cash returns by checking out the 3 dividend fortresses that combine higher yields with supporting fundamentals.
- For those hunting earlier stage potential, you might cast a wider net across the market and see what turns up in the 19 elite penny stocks with strong financials with stronger financial profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com