
Avantor (AVTR) Rebound Keeps Fair Value In Focus
Avantor (AVTR) has drawn fresh attention after recent share price moves, with the stock closing at US$15.54. Investors are reassessing what the current valuation implies for this global lab supplies and biopharma services provider.
Short term momentum in Avantor has cooled slightly, with a modest pullback over the past month after a solid 90 day share price return of 13.76% and a strong year to date share price gain of 35.60%. The 1 year total shareholder return of 36.56% contrasts with weaker total shareholder returns over three and five years, which may indicate that recent optimism is tied to changing expectations for the business rather than a long running trend.
Compare Avantor's rebound with other lab and healthcare suppliers that screen for strong fundamentals using the hand picked list of solid balance sheet and fundamentals (24 results) as a starting point.
Avantor has already bounced hard, yet the stock still trades at a reported 47% discount to one intrinsic value estimate. Is the bigger opportunity now ahead of shareholders, or already in the rear view mirror?
Most Popular Narrative: 10% Undervalued
Avantor's analyst consensus Narrative on Simply Wall St points to a fair value of $17.35, compared with the recent close at $15.54. This frames the stock as modestly undervalued based on those long term cash flow and earnings assumptions.
The numbers and current valuation together imply a stock price that already reflects a fair outcome where Avantor delivers on its multi-year turnaround and free cash flow targets without needing a sharp re-rating from here.
See why 10 investors see Avantor as 10% undervalued.
Result: Fair Value of $17.35 (UNDERVALUED)
Still, the Avantor story relies on the Revival turnaround delivering, despite competitive pressure in lab distribution and ongoing margin headwinds from inflation and planned reinvestment.
Find out about the key risks to this Avantor narrative.
Another View: What Avantor’s P/E Ratio Is Saying
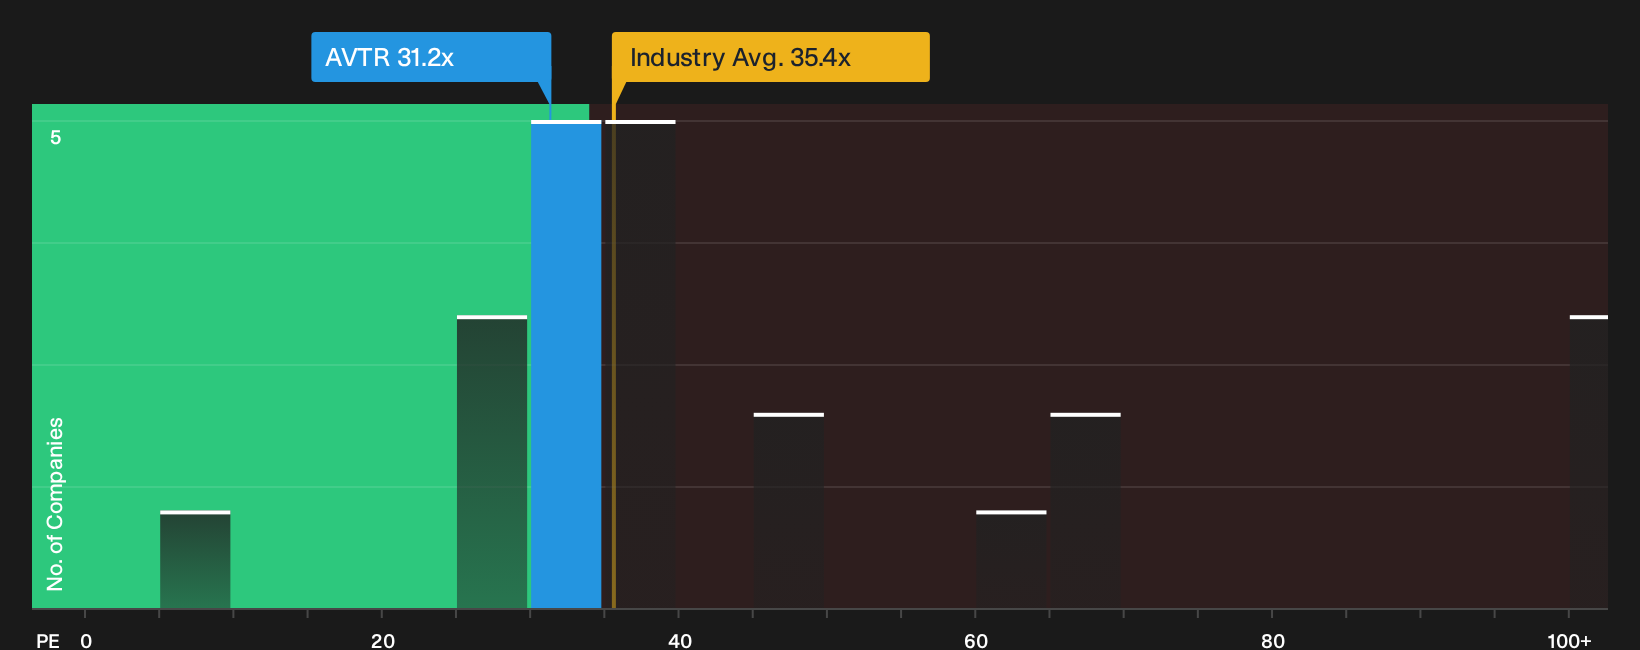
The DCF workup presents Avantor as undervalued, but the earnings multiple sends a tougher message. At a P/E of 31.2x versus a fair ratio of 19.8x, the stock trades at a rich premium to where that model suggests the market could drift over time.
Avantor also sits below the Global Life Sciences industry average P/E of 35.4x and under the 34.1x peer average, yet above its own fair ratio. That combination points to a tension between relative appeal and absolute valuation risk. Which side of that trade off matters more to you right now: the discount to peers or the gap to the fair ratio?
See what the numbers say about this price in our valuation breakdown, then compare Avantor with other companies using the same lens See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Avantor so far. If you want your view to be grounded in the full picture rather than the headline metrics, it is worth weighing both the bright spots and the pressure points by checking the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Avantor?
If Avantor has sharpened your focus, now may be a good time to widen your opportunity set with a few targeted screens that highlight very different types of potential candidates.
- Explore potential mispricings by scanning companies that combine quality with attractive entry points using the 32 high quality undervalued stocks.
- Prioritise resilience by filtering for businesses with robust finances through the 31 resilient stocks with low risk scores.
- Identify early stage potential by reviewing smaller companies with strong fundamentals via the 20 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com