
Did Third Quarter Results Just Shift Crescent Energy's (CRGY) Investment Narrative?
- Crescent Energy reported third quarter 2026 revenue of US$1,351.21 million and a small net loss of US$2.17 million, alongside higher production volumes, and affirmed a US$0.12 per share cash dividend payable on November 30, 2026.
- The mix of larger reported sales, higher daily production across oil, gas and NGLs, and a maintained dividend indicates Crescent Energy is relying on operating scale and capital returns even as headline earnings remain modest.
- Attention now turns to how Crescent Energy's investment narrative holds up in light of this revenue increase and production performance.
Scan how Crescent Energy's scale and dividend approach line up against peers by reviewing our handpicked list of solid balance sheet and fundamentals (24 results) for comparison ideas in the same space.
Crescent Energy Investment Narrative Recap
The big picture for Crescent Energy is still about scaling production efficiently, integrating acquired assets and turning that into consistent free cash flow. The analyst consensus Narrative on Simply Wall St focuses on successful execution of the Devon Eagle Ford acquisition, royalty growth and balance sheet improvement. The latest quarter showed higher revenue and production but only a very small loss, so the core integration and efficiency thesis remains unproven in the short term.
For a shareholder, the key near term catalyst is whether Crescent Energy can translate its larger production base into cleaner profitability while managing interest costs and leverage. The main risk remains execution on large deals and the impact any weaker than expected cash generation could have on dividends, debt reduction and appetite for further equity dilution.
The most relevant fresh data point is Crescent Energy’s third quarter earnings and operating update. Management reported US$1,351.21 million of quarterly revenue, a small net loss of US$2.17 million and daily net sales volumes of 134 MBoe/d, with production of 328 MBoe/d across oil, gas and NGLs. That mix shows a bigger operational footprint with only marginal headline losses.
For catalysts, those figures give a current read on how the enlarged portfolio from deals like Devon Eagle Ford is functioning day to day. Investors weighing the analyst consensus Narrative on Simply Wall St can now compare those expectations to actual production, net income and the affirmed US$0.12 dividend, and decide whether the balance between growth, leverage and payouts matches their risk tolerance.
Crescent Energy's narrative projects US$6.1b revenue and US$1.5b earnings by 2029. That outlook assumes 12.3% yearly revenue growth and an earnings increase of about US$1.45b from US$54.8m today.
Uncover how Crescent Energy's fair value indicates a 49% potential upside to its current price before the discount to Crescent Energy's market value narrows.
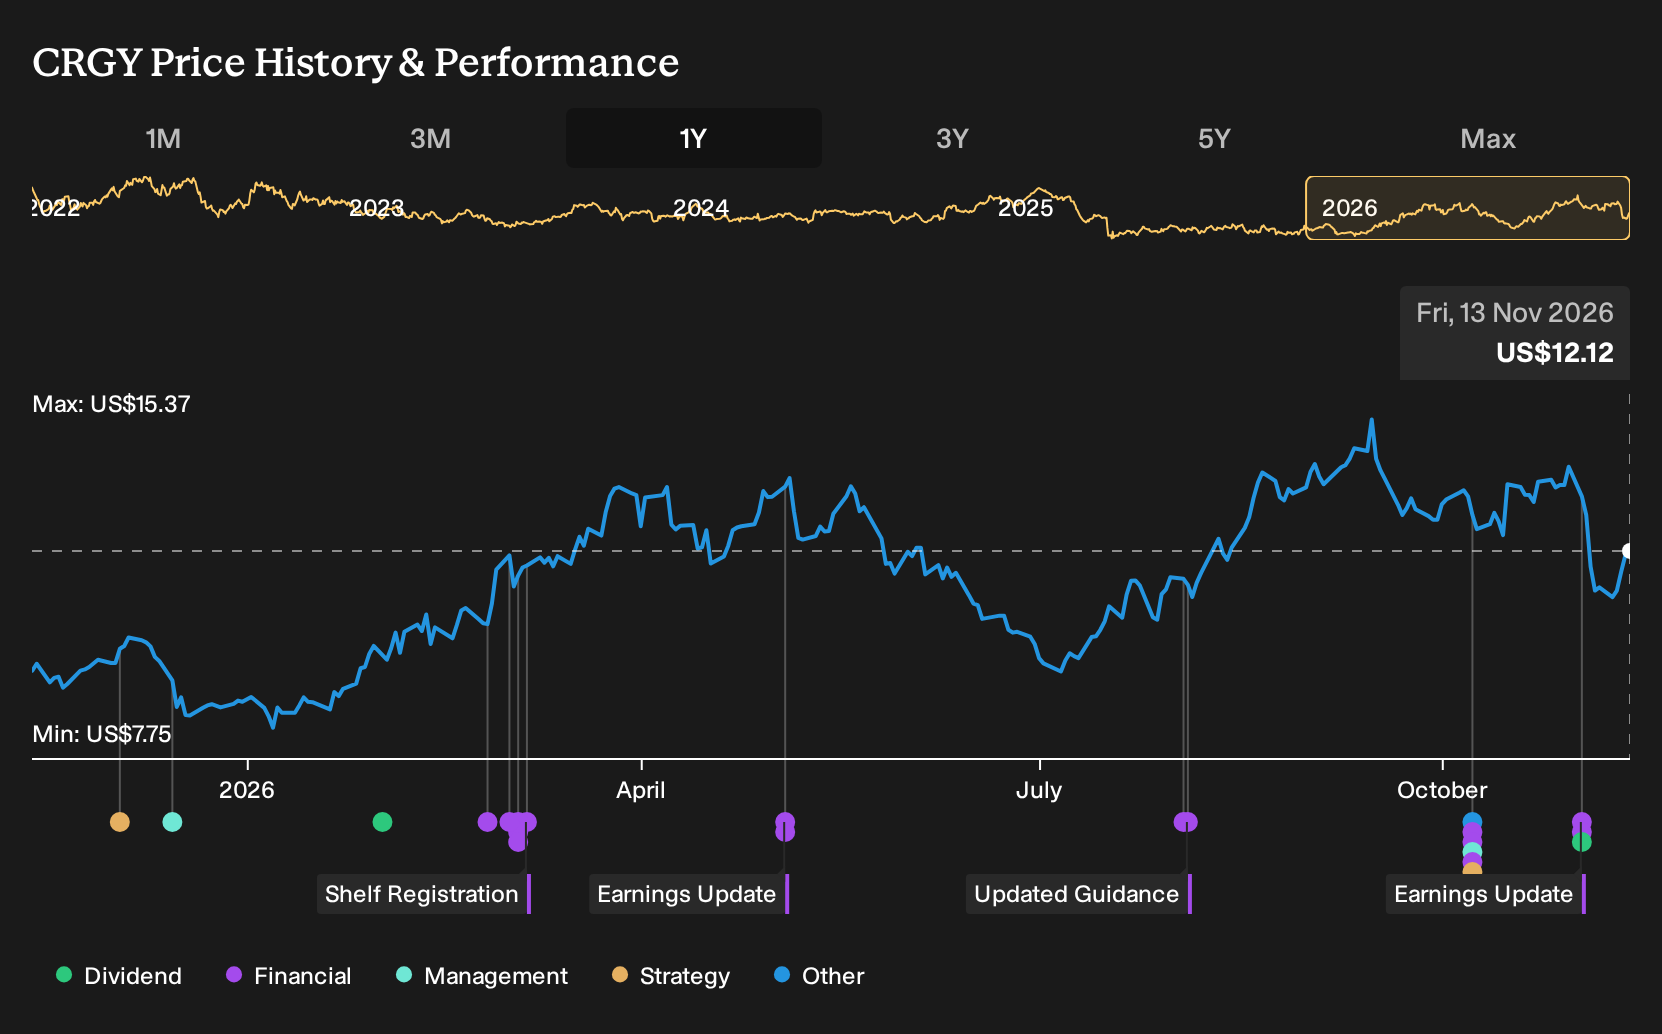
Exploring Other Perspectives
Some of the most optimistic analysts frame Crescent Energy’s dividend as the real catalyst. Before this quarter’s report, they were pencilling in about US$6.4b of revenue and US$1.8b of earnings by 2029, which is far above the baseline view. You can treat this quarter’s results as a fresh test of those upbeat expectations.
Explore 4 other Crescent Energy fair value estimates, including one that suggests potential upside of up to 339% from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Crescent Energy research is our analysis highlighting 4 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Crescent Energy. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Crescent Energy's overall financial health at a glance.
Looking for more Crescent Energy investment ideas?
If this Crescent Energy update has sharpened your thinking and you want to widen the opportunity set, the Simply Wall St Screener can help you quickly surface other stocks that fit different risk and income profiles.
- If resilience matters most to you, start with a filter focused on balance sheet strength and steady fundamentals through the 31 resilient stocks with low risk scores.
- For investors hunting for mispriced quality, use our tool to pinpoint businesses that combine robust cash flows with appealing valuations via the 32 high quality undervalued stocks.
- Income focused readers who want yield backed by underlying fundamentals can scan a curated 6 dividend fortresses to see which companies align with their payout preferences.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com