
Snap (SNAP) Stock May Trade At A Discount As Lawsuit Scrutiny Grows
Snap Inc. is trading around US$5.26 after a difficult stretch, and the question now is whether that price still makes sense when you line it up against the social media group's sales base.
- The share price has fallen about 89.8% over the past 5 years, which puts a sharp spotlight on whether the revenue Snap generates can credibly support even the current reduced valuation.
- Recent legal actions and user safety concerns around Snapchat's design features may influence how investors think about future revenue quality and the sales growth that might be required to justify today's price tag.
- The analysts covering Snap have run their own numbers. See what analysts think Snap's shares could be worth.
The stock's next move may depend on whether Snap's current market value can be squared with the level and trajectory of its sales.
Given the pressure on Snap's share price and the questions around whether its sales can justify that US$5.26 tag, it can be helpful to compare this setup with a focused list of our screener containing 20 high quality undiscovered gems.
Is Snap Still Cheap on Sales?
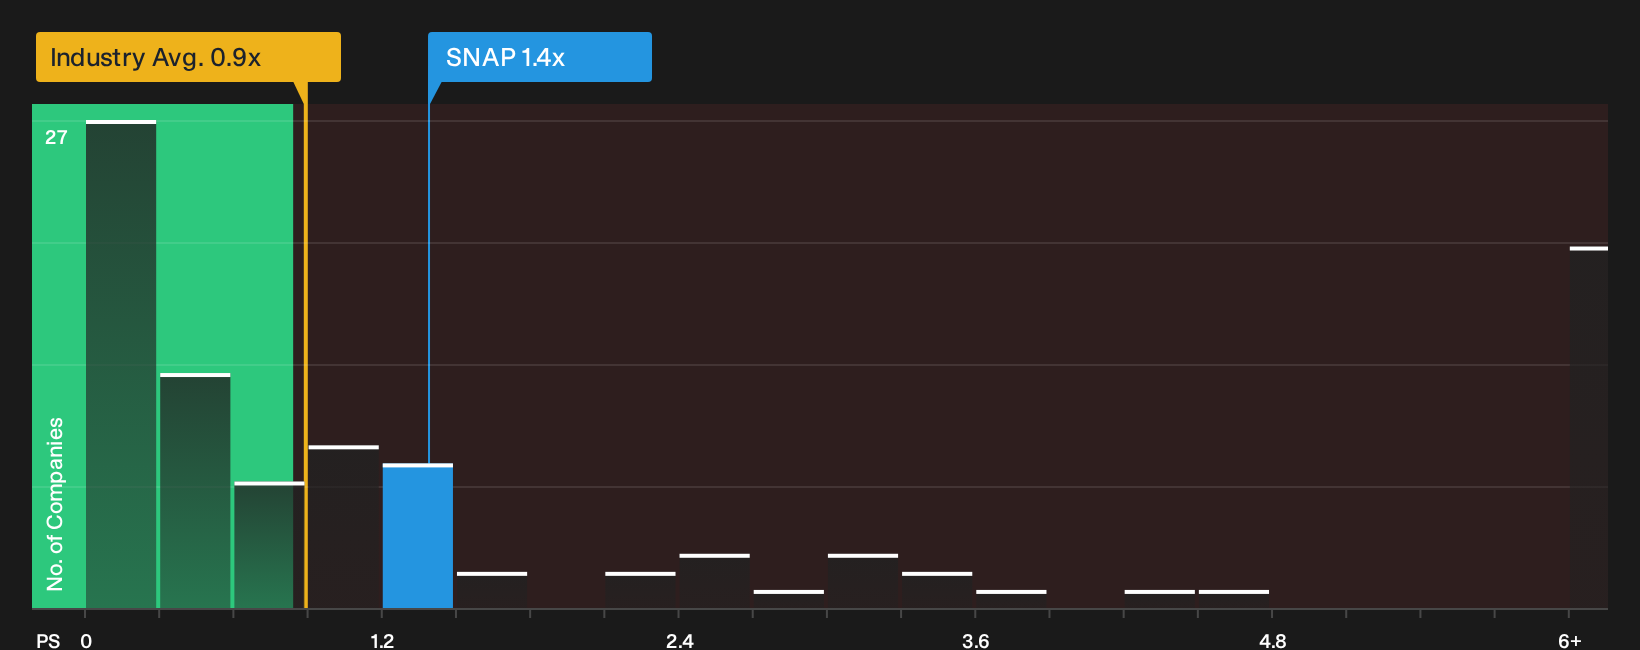
P/S suits Snap because revenue remains the clearest yardstick for a business that is still working to translate its user base into consistent profits. On this metric, Snap trades on a P/S of about 1.4x, which is below both the broader interactive media industry at roughly 0.9x and a tighter peer group closer to 2.0x.
That gap to the tailored fair P/S level points to the stock screening as undervalued on this measure, given the mix of its current margins, growth profile, size and risk. Because the recent lawsuit headlines and concerns about Snapchat’s safety features put extra question marks over future revenue quality, the fact that the P/S multiple still sits below what the model suggests can be helpful context if you are weighing whether sentiment has swung too far. Explore the numbers behind Snap's P/S valuation.
The Snap Narrative: What Would Justify Today's Price?
Snap Narratives on Simply Wall St pick up where the P/S puzzle leaves off by spelling out what path for revenue, profitability and earnings would need to play out for the stock to be worth materially more or less than it is today, all housed on the Community page. Each scenario links its number to a clear view on how Snap's growth, margin profile and key risks might evolve, giving you something concrete to test as fresh information comes through.
Bulls and bears are looking at the same Snap story but reaching very different conclusions about what the current valuation implies.
Bull case: 26% undervalued
The analyst consensus Narrative on Simply Wall St sketches a turnaround built around new products and stronger monetization.
"Monetization progress in subscription products such as Snapchat+ and Lens+, alongside growing engagement with Spotlight and creator-driven content, is diversifying Snap's revenue base and improving net margin potential by capturing higher-margin direct-to-consumer and content revenue streams…"
Discover why this Narrative puts Snap at 26% undervalued.
Bear case: 17% overvalued
The bearish analyst Narrative on Simply Wall St focuses on youth risk, regulation and execution as the pressure points.
"Bearish analysts expect Snap to remain structurally exposed to youth-focused usage and regulatory pressure, which could constrain engagement and the effectiveness of its ad and subscription growth efforts…"
Explore why this Narrative puts Snap at 17% overvalued.
One more Snap check sits outside the current price debate
Before you leave Snap at a simple comparison of P/S and narratives, it is worth seeing where professional forecasts place this business a few years out and how that picture lines up with today. Explore where analysts expect Snap to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com