
Where Does Fermi (FRMI) Value Sit After Board Turmoil And Lease Changes?
Fermi has seen its share price move sharply over the past year, and with the business now trading at a much lower level than it did 12 months ago, the question is whether the current US$2.61 quote makes sense when set against its book value.
- Over the past 12 months, the stock has fallen 85.7%, which puts the focus squarely on whether the balance sheet can still support even this reduced valuation.
- Project Matador and the shift from a terminated lease toward new hyperscaler agreements may change how investors think about future capital needs and how much weight to put on existing equity capital on the books.
- Your read on Fermi is one view; the desks covering it have another. See what analysts think Fermi's shares could be worth.
For investors, the debate is whether Fermi's current market value lines up with the book value underpinning the business after this mix of sharp price moves and project updates.
If you want to stress test this kind of book value question beyond Fermi, run the same filter across 32 high quality undervalued stocks.
Is Fermi Fairly Priced on Book Value?
Price to book fits Fermi because the business is being weighed heavily on its asset base and financing needs for Project Matador.
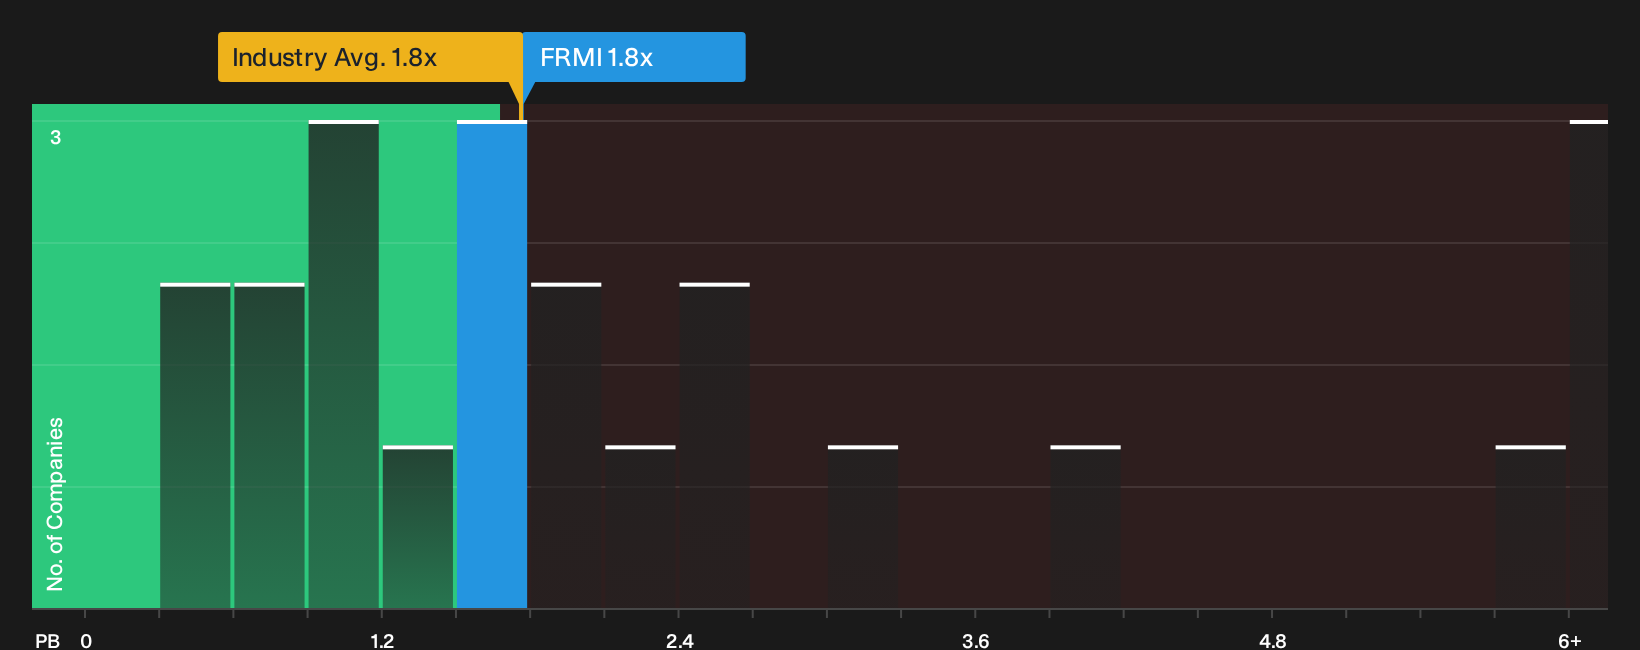
On this lens, Fermi trades on a P/B of about 1.8x, which is very close to the Specialized REITs industry average of roughly 1.8x and below the peer group around 2.9x. Despite the pressure created by the boardroom dispute and calls for a sale from co founder Toby Neugebauer, the multiple still values the shares broadly in line with the wider sector on book value.
This leaves the current P/B sending a fairly neutral signal. Investors need to decide whether the mix of terminated leases, new hyperscaler commitments and the associated capital demands justify paying roughly an industry level multiple for Fermi's equity base. Explore the numbers behind Fermi's P/B valuation.
The Fermi Narrative: What Would Justify Today's Price?
Fermi's Simply Wall St Narratives pick up right where this valuation puzzle leaves off, explaining what kind of growth, margin profile and earnings path would need to occur for the share price to sit meaningfully above or below today's level. Each narrative anchors its implied number to a specific view on where Fermi's expansion, profitability and risk profile could go next, which gives you something concrete to revisit as fresh information becomes available.
One of the top narratives on Fermi: 93% undervalued
This Narrative is the bullish analyst Narrative on Simply Wall St, built on the most optimistic analyst price target and forecasts, not one person's view.
"The numbers imply that if Fermi fills its planned multi-gigawatt capacity on terms similar to disclosed long-term agreements, the current share price treats that outcome as far from fully reflected…"
Discover why this Narrative puts Fermi at 93% undervalued.
Before you move on Fermi, there is one more piece to check
Valuation only tells part of the story, and Fermi also carries a set of flagged risk checks that could change how you feel about the whole setup once you review them. Take a closer look at 4 warning signs (3 major) before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com