
Valero (VLO) Stock May Be Undervalued As Earnings Face Scrutiny
Valero Energy has delivered a very long run for shareholders, and the question now is whether the current price really lines up with what its earnings can support. For anyone looking at the stock today, the issue is less about momentum and more about what the underlying profit stream actually justifies.
- Over the past 5 years the share price has risen by about 7x, which puts a lot of focus on whether the present valuation is still anchored to the refinery group’s earnings power.
- The business still leans heavily on converting refining capacity into cash, so long term returns on the current price may depend on how consistently Valero Energy can turn its complex assets and cost base into reliable profits.
- Your read on Valero Energy is one view; the desks covering it have another. See what analysts think Valero Energy's shares could be worth.
The stock's next move may depend on whether the current earnings based valuation looks well supported by how much profit Valero Energy is generating today.
If you are weighing whether Valero Energy’s earnings still justify this kind of share price run, it can help to compare it with a wider set of companies that meet clear, earnings based criteria through 32 high quality undervalued stocks
Is Valero Energy a Bargain on Earnings?
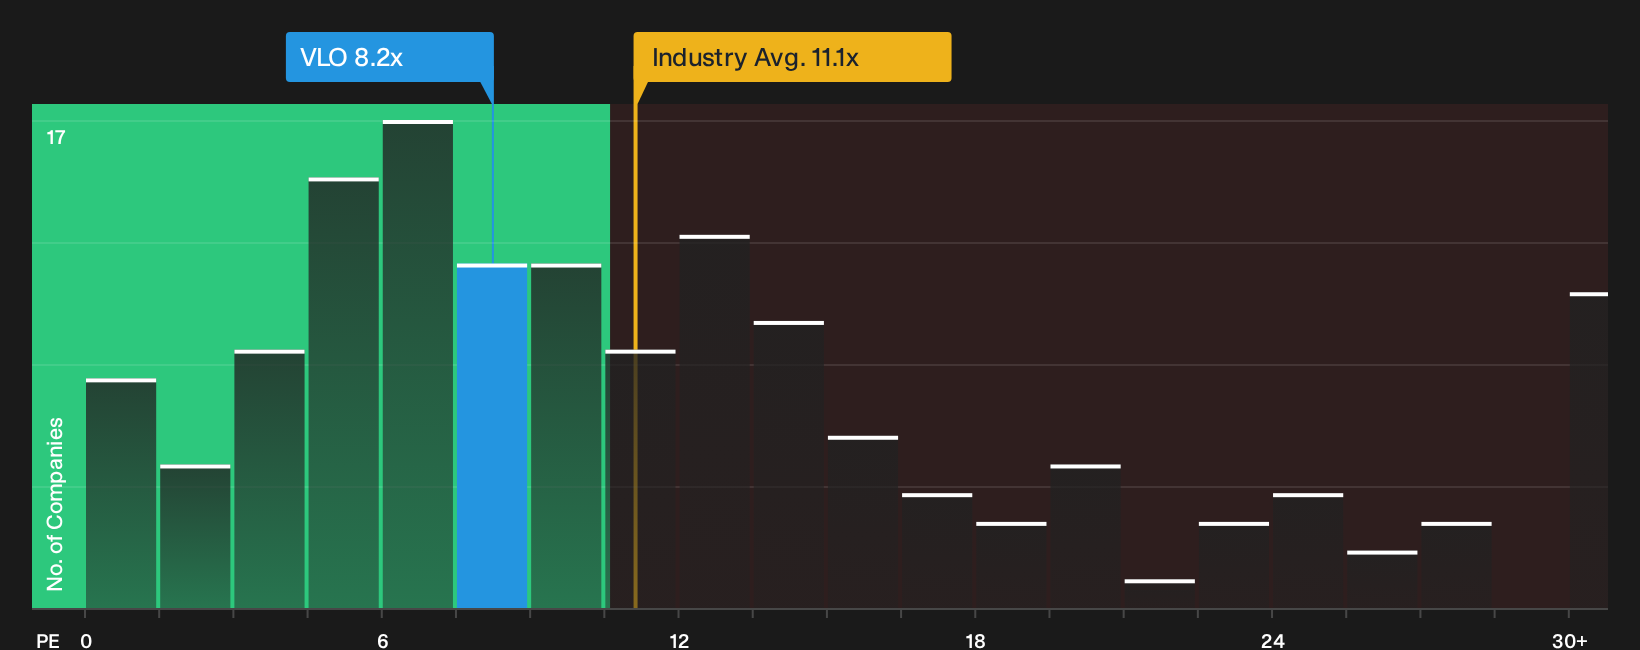
The P/E ratio suits Valero Energy because earnings are still a central reference point for how the market prices large refiners. The stock trades on a P/E of about 8.2x, which is higher than the peer group average of roughly 6.0x but below the wider Oil and Gas sector on about 11.1x. That leaves the shares priced at a premium to closer refinery comparables yet at a discount to the broader industry that includes more diversified energy groups.
The Fair Ratio model, which adjusts the yardstick for factors like profitability profile, size and risk, points to a higher P/E than where Valero Energy trades today. That gap suggests the current earnings multiple screens as undervalued on this framework, even though the peer snapshot shows the shares already valued more fully than many direct competitors. For any holder or potential buyer, the key question is whether Valero Energy’s earnings quality and cash generation justify leaning more on the tailored Fair Ratio signal rather than on the simpler peer comparison. Explore the numbers behind Valero Energy's P/E valuation.
The Valero Energy Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Valero Energy pick up where the valuation puzzle leaves off by spelling out which paths for the company’s growth, margins and earnings would need to play out for the stock to look meaningfully cheaper or more expensive than it does today. Each one ties its number to a clear view on how Valero Energy's profitability profile and risk mix might shift, giving you a reference point you can revisit as new information comes through.
Bulls and bears are looking at the same Valero Energy earnings engine and reaching very different conclusions about how much is already baked into the price.
Bull case: 11% undervalued
This view from the analyst consensus Narrative on Simply Wall St leans on sustained profitability and disciplined capital returns.
"The main thing that has to go right is that Valero maintains strong refining and low carbon fuel profitability while keeping capital discipline and high shareholder payouts…"
Discover why this Narrative puts Valero Energy at 11% undervalued.
Bear case: 35% overvalued
The bearish analyst Narrative on Simply Wall St stresses how sensitive Valero Energy could be to margin pressure.
"Any meaningful crude price increase could compress crack spreads and pull future refining revenue and net margins below what current earnings imply…"
Explore why this Narrative puts Valero Energy at 35% overvalued.
One more angle on Valero Energy that could shift the picture
Price tags and profit streams only tell part of the story, because the people setting Valero Energy’s priorities and how they are rewarded can tilt future outcomes in ways the current numbers do not show. See who runs Valero Energy and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com