
C.H. Robinson Worldwide (CHRW) Extends Credit Facility, Is The Stock Still 26% Undervalued?
C.H. Robinson Worldwide (CHRW) has reworked its core borrowing arrangements, extending its revolving credit facility to 2031 and expanding available commitments to support its planned RXO acquisition and broader logistics operations.
For investors tracking the bigger picture, C.H. Robinson Worldwide’s short-term share price momentum has been mixed, with a 7.28% gain over the past week, a decline of 3.58% over 30 days, and a year-to-date fall of 17.87%. In contrast, the 3-year total shareholder return of 74.15% and 5-year total shareholder return of 56.41% point to a very different long-term experience.
Compare C.H. Robinson Worldwide’s latest funding move with other logistics and freight players by scanning our handpicked list of solid balance sheet and fundamentals (24 results), which may offer different risk and return trade-offs.
C.H. Robinson Worldwide now trades between a history of mixed recent returns and analyst estimates that sit far higher than today’s price. Does that gap reflect an opportunity, or a reset in what this business is worth?
Most Popular Narrative: 26% Undervalued
On the analyst consensus Narrative on Simply Wall St, C.H. Robinson Worldwide’s fair value of $182.78 sits well above the last close at $134.46. This puts the current funding moves and RXO plans under a brighter spotlight.
Acceleration in AI driven automation across the full lifecycle of shipments continues to show more than 60% productivity gains in businesses like NAST and Global Forwarding, which supports further decoupling of headcount from volume and can lift operating margins and earnings as additional volume runs through this model.
See why 8 investors see C.H. Robinson Worldwide as 26% undervalued.
Result: Fair Value of $182.78 (UNDERVALUED)
Still, the recent US$604m jury award over accident liability and concerns about tighter broker margins could undermine the bullish C.H. Robinson Worldwide narrative if these pressures intensify.
Find out about the key risks to this C.H. Robinson Worldwide narrative.
Another View: What C.H. Robinson Worldwide’s P/E Is Telling You
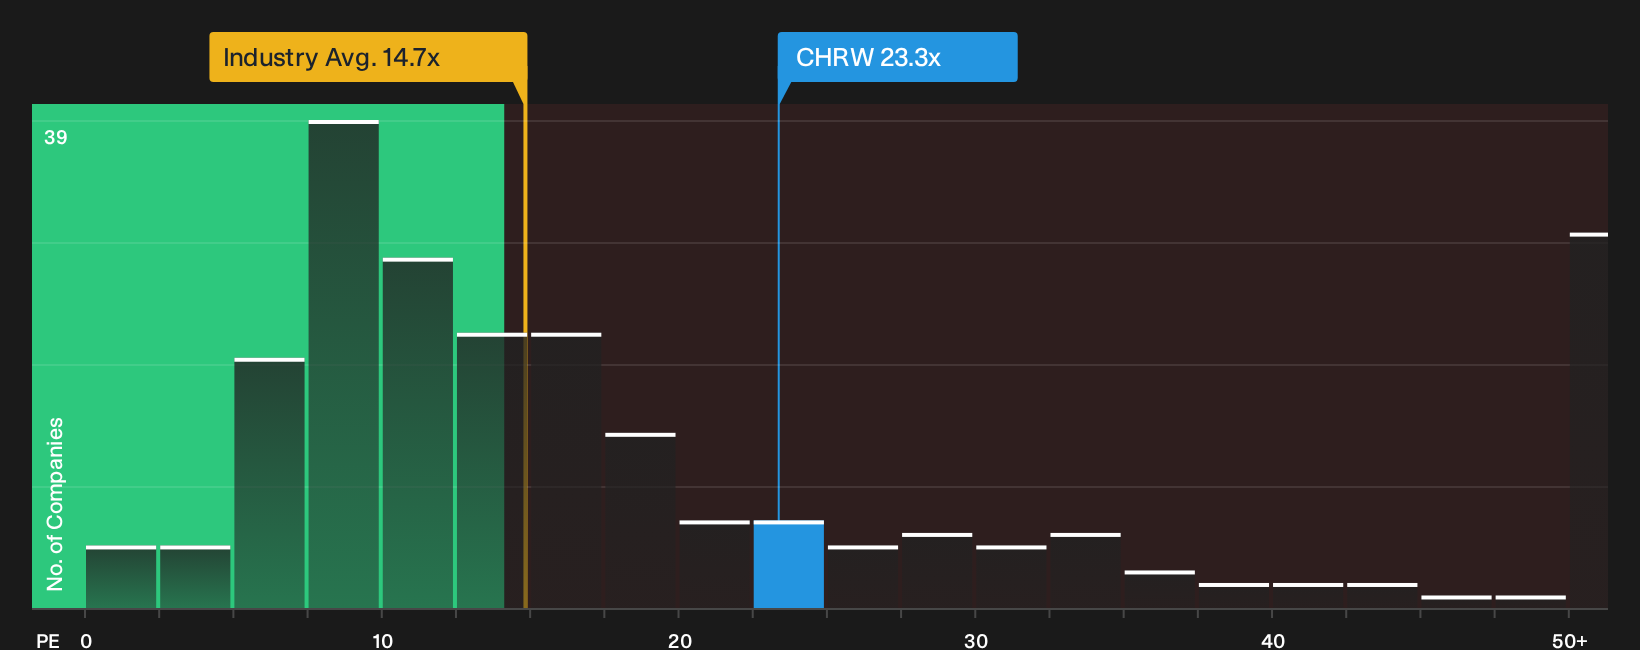
There is a different read on C.H. Robinson Worldwide when you look at the price tag on its earnings. The stock trades on a P/E of 23.3x, which is well above the Global Logistics group at 14.7x and also above its own fair ratio of 17.4x. That gap suggests investors are already paying a premium and leaves less room for error if growth or margins disappoint.
For a closer look at how that earnings multiple compares with peers and what it could mean for upside or downside risk, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around C.H. Robinson Worldwide can feel confusing, so move quickly from headline takes to your own view by weighing both sides through the 3 key rewards and 1 important warning sign.
Looking for more C.H. Robinson Worldwide style investment ideas?
If you only stop at C.H. Robinson Worldwide, you miss a wider set of opportunities that could sharpen your portfolio and balance your risk and reward.
- Prioritise resilience and capital protection by scanning a curated 31 resilient stocks with low risk scores that focuses on businesses with more defensive risk profiles.
- Target outsized upside potential by reviewing a focused 20 high quality undiscovered gems that highlights quality companies the market may be overlooking.
- Strengthen long term income potential by assessing a hand picked set of 6 dividend fortresses that emphasise higher yields with robust fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com