
Duke Energy (DUK) Secures Credit Facility Amendment, Is The Stock Cheap Or Pricey?
Duke Energy (DUK) just secured an amendment to its US$10b multi borrower credit facility, including lender consent for merging Duke Energy Progress into Duke Energy Carolinas in advance of a planned 2027 internal reorganization.
Duke Energy’s latest credit facility amendment lands after a busy spell, with the share price up 7.96% over the past 30 days and 9.98% year to date, while the 5 year total shareholder return of 58.92% points to longer term compounding.
Scan beyond Duke Energy and see how other regulated utilities are positioned on debt capacity and balance sheet strength with a curated set of 31 resilient stocks with low risk scores.
Duke Energy looks like a solid regulated utility with fresh earnings momentum and a reinforced US$10b credit backstop. After the recent share price jump, is the quality of the business matched by a fair entry price today?
Most Popular Narrative: 3.6% Undervalued
The analyst consensus Narrative on Simply Wall St points to a fair value of about $133.94 for Duke Energy against a last close of $129.16. This frames the current price as modestly below that narrative fair value and anchors expectations in detailed revenue and earnings forecasts.
The current narrative that Duke Energy is undervalued suggests the share price does not fully reflect the contracted and late-stage large-load pipeline, the size of the regulated capital plan and the company’s stated plans to strengthen its balance sheet while funding future growth and equity needs.
See why 98 investors see Duke Energy as 4% undervalued.
Result: Fair Value of $133.94 (UNDERVALUED)
Still, planned issuance of about US$10b in equity, along with potential pressure from lower regulated rates in Florida, could dilute Duke Energy’s per share earnings story.
Find out about the key risks to this Duke Energy narrative.
Another View: Our DCF Flags Duke Energy As Overvalued
The Simply Wall St DCF model tells a different story for Duke Energy. On that cash flow view, fair value sits around $111.53 per share against a market price of $129.16. That points to a premium rather than a discount. Which lens do you trust more when the signals conflict?
For readers who want to see how this cash flow view is built line by line, Look into how the SWS DCF model arrives at its fair value.
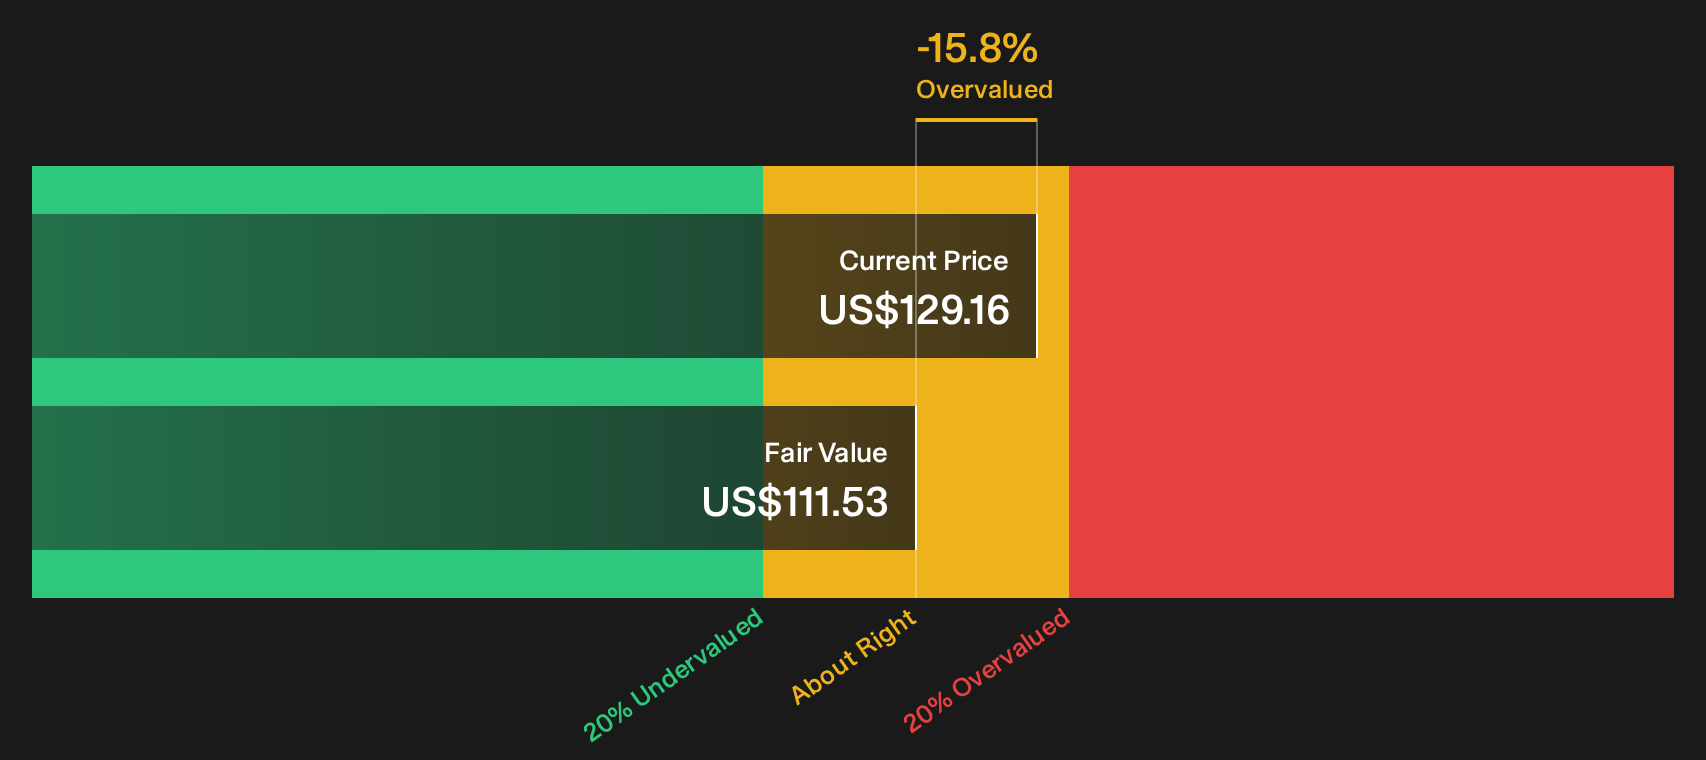
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Duke Energy for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Conflicted by the mixed messages on Duke Energy and its valuation signals? Move quickly from headline impressions to your own data-driven view by weighing 4 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Duke Energy?
If Duke Energy has sharpened your focus on quality, do not stop here. Broaden your watchlist with a few targeted screens that surface different kinds of opportunities.
- Capture potential mispricing by scanning a curated pool of companies screened as attractively valued using the 32 high quality undervalued stocks.
- Strengthen your income stream by zeroing in on steadier payers screened as 6 dividend fortresses.
- Protect your downside by focusing on balance sheet resilience with a tailored list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com