
3 AI Infrastructure Stocks Retail Investors Are Watching For Data Center Growth
AI data centers are pulling in huge capital commitments, fresh restrictions on Nvidia GPUs into China, and rising local chip rivals all at once. That turns today’s headlines into more than just tech news, because they flag where money is quietly being committed next. This piece walks through 3 stocks tied to that story and helps you decide whether they deserve a closer look or a spot on your avoid list.
The three stocks below are just a starting sample, because the full screen surfaced 27 more companies tied into AI chips, racks, cooling, networking and power that carry equally compelling narratives but are not covered here.
To identify, compare, and analyze the highest conviction ideas that fit this theme, go straight to the Global AI Data Center Infrastructure & Semiconductors screener.
Shengyi TechnologyLtd (SHSE:600183)
Overview: Shengyi TechnologyLtd produces copper clad laminates and printed circuit boards that sit inside AI servers, telecom gear, and a wide range of electronics worldwide.
Market Cap: CN¥165.5b
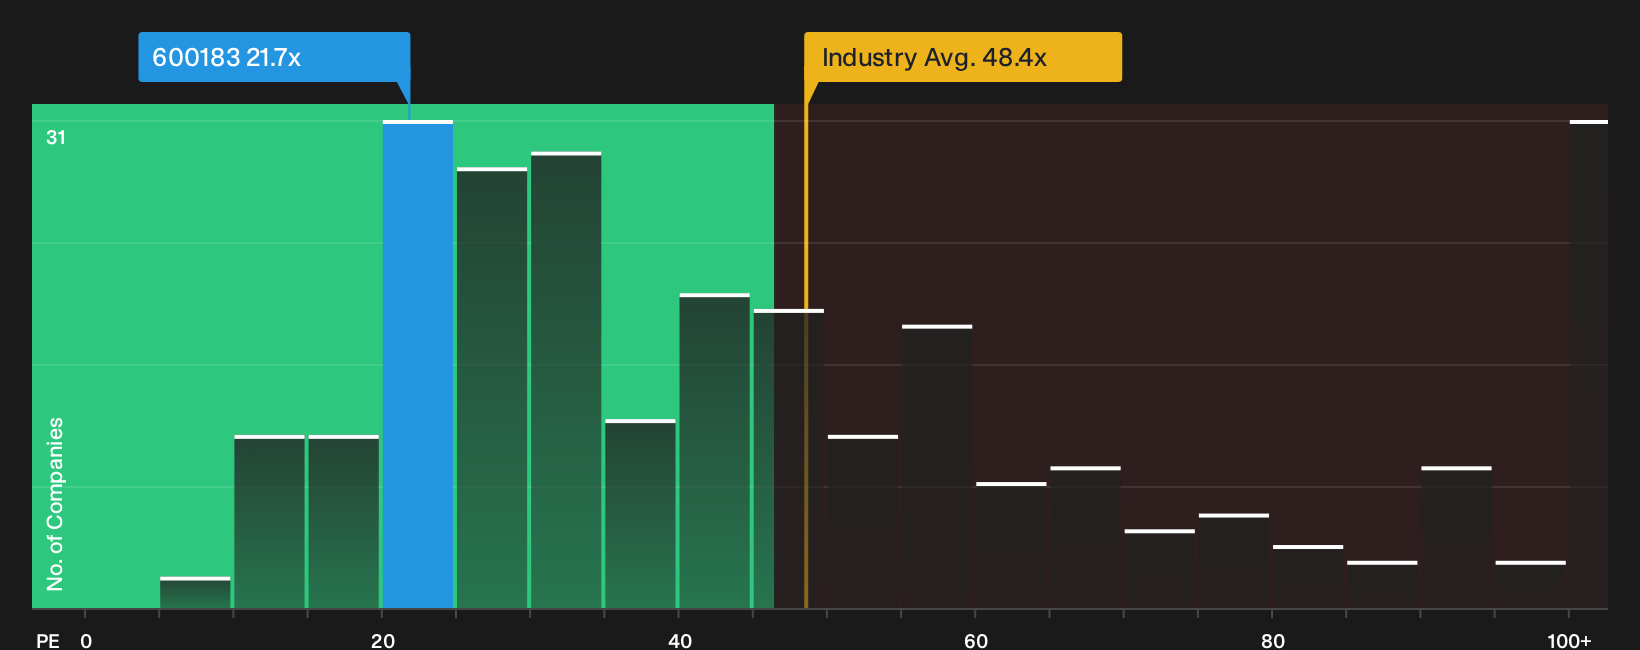
Shengyi TechnologyLtd plugs into the AI data center buildout at the materials level, supplying laminates and PCBs that go into high computing power servers and networking gear. Earnings grew 171.1% year over year and the P/E of 21.7x sits below the CN Electronic industry average. Future returns hinge on how one unseen funding pressure develops.
That funding pressure could be the real hinge, so read the 4 key rewards and 2 important warning signs (1 is major!) to see where Shengyi TechnologyLtd’s upside might be colliding with hidden constraints.
WT Microelectronics (TWSE:3036)
Overview: WT Microelectronics distributes semiconductors and electronic components into data centers, servers, and communications hardware, giving investors indirect AI infrastructure exposure.
Market Cap: NT$237.0b
WT Microelectronics plugs into the Global AI Data Center Infrastructure & Semiconductors theme as a large, profitable distributor feeding chips and parts into servers, networking gear, and power hungry racks, rather than designing GPUs itself. Investors get scale, liquidity, and a 4.18% dividend yield, with one unresolved funding pressure that could eventually ripple through margins if conditions tighten.
If that funding squeeze is what you are watching, go straight to the 5 key rewards and 2 important warning signs (1 is major!) to see where WT Microelectronics’ yield story could decouple.

Gold Circuit Electronics (TWSE:2368)
Overview: Gold Circuit Electronics manufactures printed circuit boards in Taiwan for AI servers, networking equipment, notebooks, handsets, automotive electronics, and IC testing.
Operations: The business generates about NT$89.6b in revenue from manufacturing and selling printed circuit boards across its electronics customer base.
Market Cap: NT$535.2b
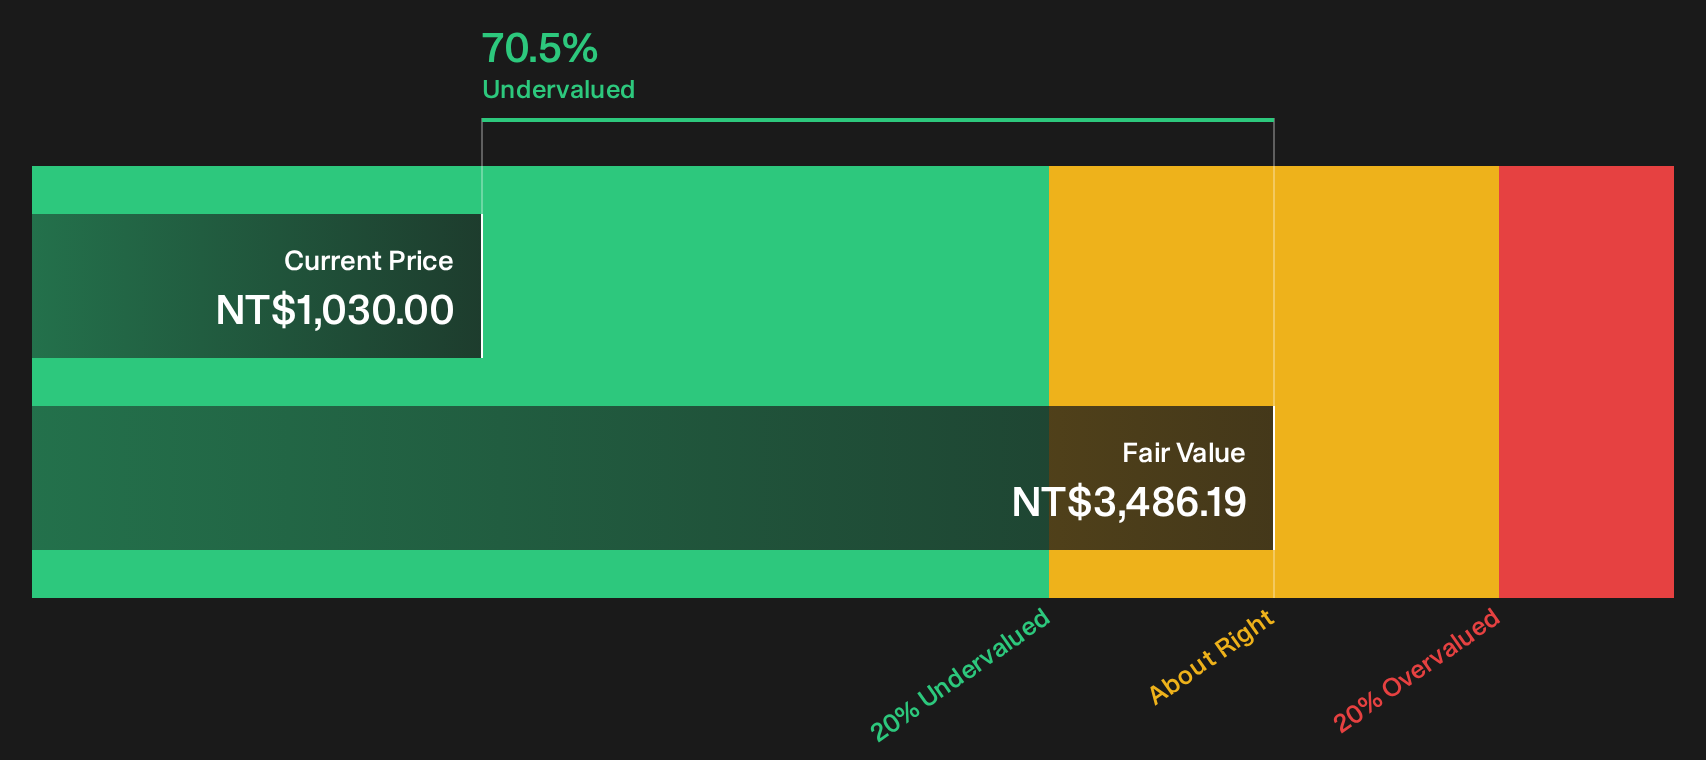
Gold Circuit Electronics supplies PCBs for servers and networking gear used in AI data center hardware as capital expenditure builds out worldwide. Recent Q3 2026 and 9M 2026 results show large year on year gains in sales and earnings, and the valuation still reflects a discount to projected cash flow, depending on how one unseen funding pressure develops.
If that funding pressure is what you are weighing, read the 3 key rewards and 2 important warning signs (2 are major!) to understand where Gold Circuit Electronics’ valuation story could accelerate or stall next.
Seeking Fresh Alternatives Before Momentum Flies
Markets move fast, and the best breakout stories rarely sit still. Scan fresh ideas before momentum runs away, while they are under the radar for now. Consider new opportunities early.
- Scan for potential breakout cash generators before the crowd by running the 197 high quality undervalued stocks while their momentum story is still forming and information decay has not caught up.
- Track trends in real assets with the 33 elite gold producer stocks before sentiment changes and prices move beyond levels that may feel comfortable for an initial entry.
- Monitor automation-related ideas by using the 86 robotics and automation stocks while adoption is still developing and valuations reflect current assumptions rather than potential future demand.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com