
Did Updated Oil Guidance Just Shift SM Energy's (SM) Investment Narrative?
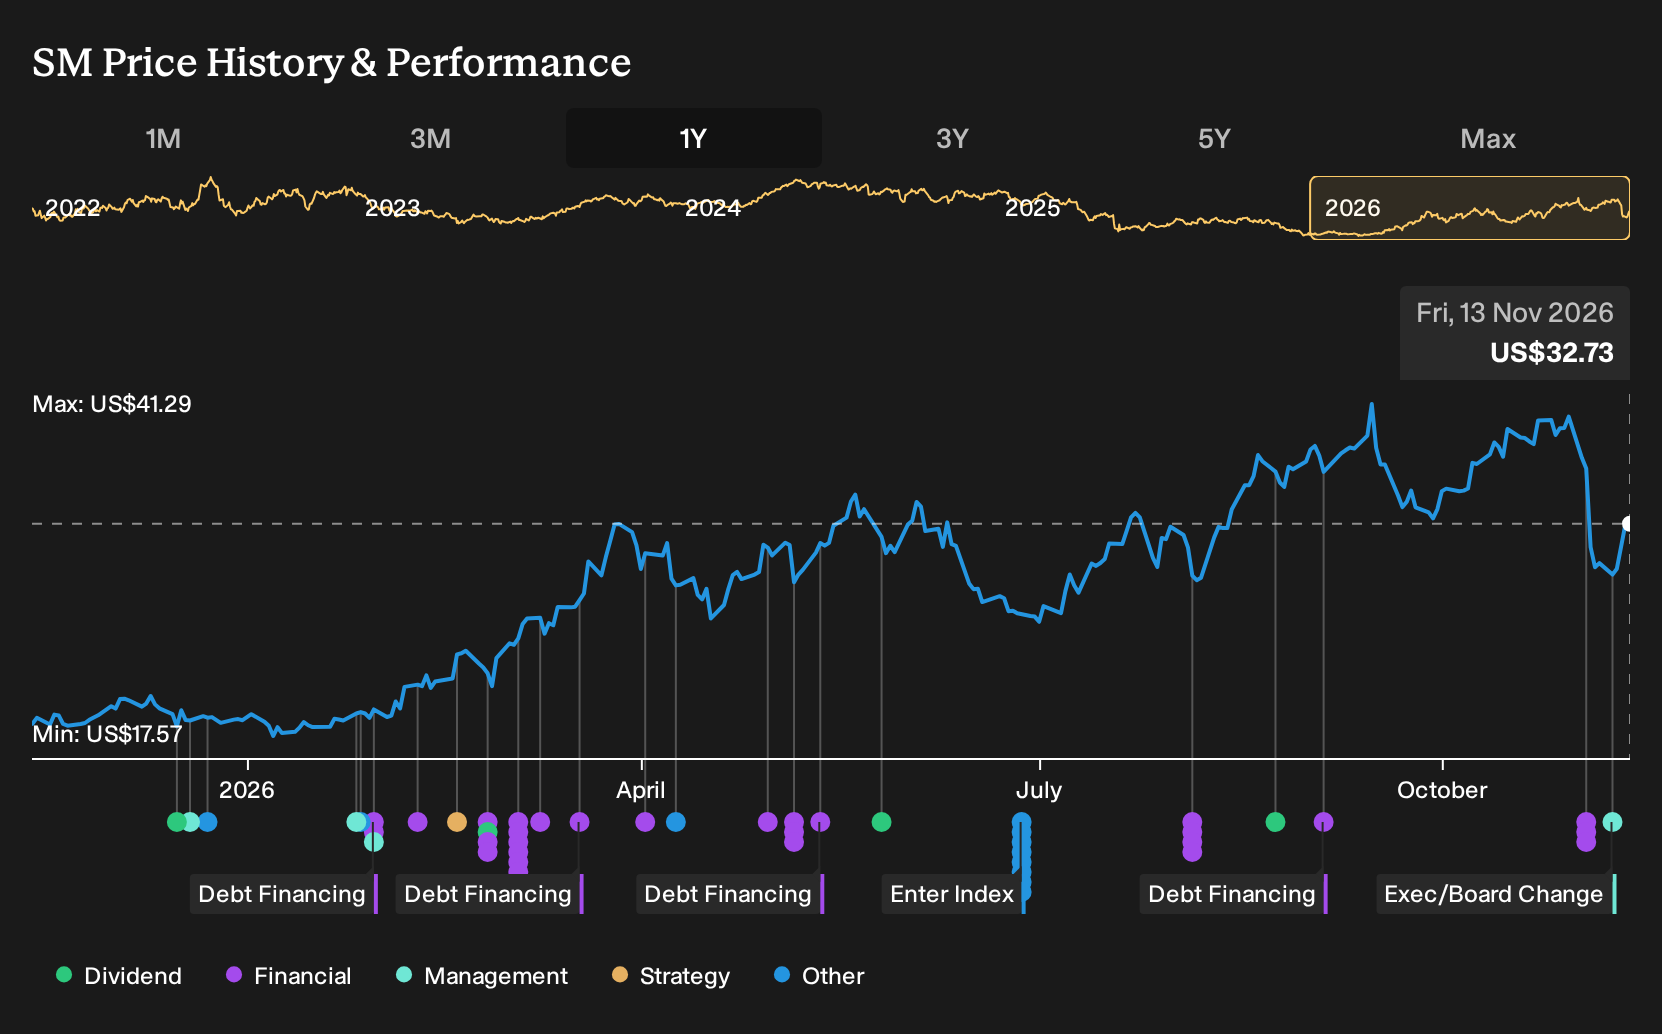
- SM Energy reported third quarter 2026 revenue of US$2,170 million and net income of US$93 million, along with higher oil, gas and NGL production and updated guidance that slightly reduced full year oil volume expectations.
- The new production outlook, combined with stronger year to date revenue and the appointment of George Green as Chief Legal Officer, shows how SM Energy is balancing growth, cost control and governance as it refines its operating plan.
- The key question now is how SM Energy's updated production guidance and mixed earnings trend will reshape the existing free cash flow investment narrative.
Scan for other energy producers reshaping their playbook after fresh earnings and guidance shifts by comparing SM Energy against list of solid balance sheet and fundamentals (24 results).
SM Energy Investment Narrative Recap
To own SM Energy, you need to believe the business can keep turning a multi basin footprint, merger synergies and cost efficiencies into resilient free cash flow. The analyst consensus Narrative on Simply Wall St assumes earnings growth comes from operational execution more than aggressive volume expansion. The slightly lower full year oil guidance and mixed quarterly earnings do not appear to alter that core thesis in a major way.
The short term swing factor is whether SM Energy can deliver the production profile and synergy capture that underpin its free cash flow maximization plan while managing a still meaningful debt load. Near term risk sits in any operational hiccups or pricing pressure that squeeze margins further, given net profit margins are already below last year.
The appointment of George Green as Senior Vice President, Chief Legal Officer and Corporate Secretary ties directly into the execution side of this story. SM Energy is running a complex portfolio that includes regulatory sensitive areas like the DJ Basin, where opposition to certain projects has been flagged as a risk to drilling plans and volumes.
A seasoned in house legal lead with prior experience at DCP Midstream and PerkinElmer may help the company manage permitting, contracts and governance while it pursues cost savings and multi basin development. For investors watching catalysts, legal and regulatory execution sits alongside production delivery, debt reduction and synergy capture as a key link between guidance and actual outcomes.
SM Energy's narrative projects US$7.4 billion revenue and US$1.8 billion earnings by 2029. That path assumes 14.4% yearly revenue growth and requires earnings to increase by about US$800 million from US$1.0 billion today.
Uncover how SM Energy's fair value indicates a 41% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts focus on SM Energy’s drilling inventory as a potential catalyst, rather than just cost control. Before this earnings print and the George Green appointment, the bullish camp was modeling about US$8.6b in 2029 revenue and US$2.4b in earnings. That is far above consensus, and those views may now shift. Use this as a prompt to compare several narratives before deciding what you think is realistic.
Explore 5 other SM Energy fair value estimates, including one that suggests as much as 278% upside from the current price!
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your SM Energy research is our analysis highlighting 5 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for SM Energy. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate SM Energy's overall financial health at a glance.
Looking For More Ideas Beyond SM Energy?
Once you have a view on SM Energy, it can help to widen the lens and compare it with other businesses that match your preferred mix of quality, risk and income. The Simply Wall St screener lets you move from a single ticker to a shortlist that fits your own criteria, rather than someone else's hot list.
- If capital preservation and steadier profiles matter most to you, start with a group of companies that screen as relatively resilient by checking out 31 resilient stocks with low risk scores.
- For readers who care about strong finances and less stressed balance sheets, build a watchlist from a list of solid balance sheet and fundamentals (24 results) that can support long term plans.
- If you are hunting for quality that is not widely followed yet, scan through a curated pool of 20 high quality undiscovered gems that combine fundamentals with lower market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com