
Warby Parker (WRBY) Could Be 15% Undervalued After Its Smart Glasses Launch
Warby Parker (WRBY) just moved smart glasses from concept to product shelf. The retailer unveiled its full Intelligent Eyewear collection, built with Google and Samsung, with preorders open and deliveries expected from mid December.
Recent news has come in a cluster for Warby Parker, with the Intelligent Eyewear launch arriving just days after third quarter results, narrowed 2026 revenue guidance of US$966 million to US$976 million, and a plan for 50 new store openings this year.
Against that backdrop, the share price has climbed to US$27.44, supported by a 1 month share price return of 10.11% and a year to date share price gain of 21.31%.
For longer term holders, the picture is even more dramatic, with a 1 year total shareholder return of 61.79% and a 3 year total shareholder return of about 2.5x. However, the 5 year total shareholder return is still down 50.46%, which keeps expectations in check despite the recent momentum.
Scan how Warby Parker's smart glasses story fits into a broader theme by reviewing hand-picked 53 AI infrastructure stocks in connected hardware and AI-enabled consumer tech.
So is Warby Parker’s latest jump a clean read on improving fundamentals after new guidance and product news, or mostly a reset in what investors are willing to pay for the story?
Most Popular Narrative: 14.9% Undervalued
Warby Parker's analyst consensus Narrative on Simply Wall St puts fair value at $32.25, above the last close of $27.44. This frames the recent rally as still short of that implied worth and leans on detailed forecasts for revenue, earnings and discounting at 8.46%.
The partnership with Google to develop AI-powered intelligent eyewear positions Warby Parker to enter a substantially larger market. It leverages advancements in wearable technology and artificial intelligence to drive new, higher-margin revenue streams in the future.
Expansion of the retail footprint including new shop-in-shops with Target and densification in underpenetrated suburban markets supports continued growth in active customers and higher average revenue per customer. This directly impacts top-line revenue and long-term market share.
See why 13 investors see Warby Parker as 15% undervalued.
Result: Fair Value of $32.25 (UNDERVALUED)
Still, the Warby Parker story could shift quickly if heavy store openings weigh on profitability or the Google powered eyewear launch struggles to gain traction.
Find out about the key risks to this Warby Parker narrative.
Another View: What Multiples Say About Warby Parker
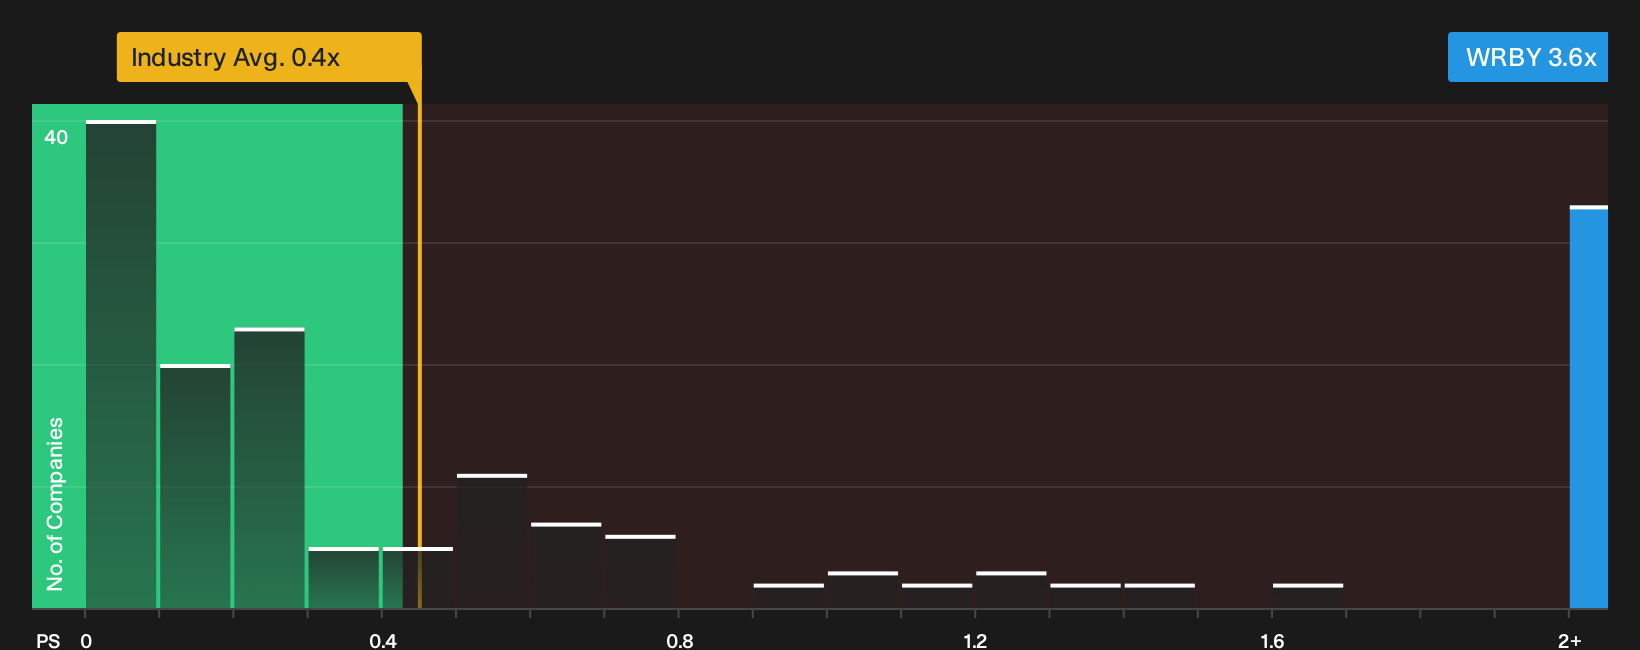
There is a different signal hiding in plain sight. On a simple P/S basis, Warby Parker trades at 3.6x sales, versus 0.4x for the broader US Specialty Retail group and 0.6x for closer peers, while the fair ratio is estimated at 1.7x.
That gap points to a rich valuation that already bakes in a lot of optimism about future growth and margin gains. The question for investors is whether the Intelligent Eyewear launch and store rollout justify paying more than double the fair ratio that the market could move towards over time.
To see how those numbers stack up in practice, review the valuation breakdown in the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Warby Parker is mixed, with enthusiasm for the story sitting alongside real questions about execution and valuation. Move quickly and stress test the data yourself. To weigh both sides of that debate in one place, review the 3 key rewards and 2 important warning signs
Looking for more Warby Parker sized ideas?
If Warby Parker has sharpened your focus, do not stop here. Use targeted screeners to quickly surface other stocks that match the kind of opportunity you are hunting.
- Target higher quality potential by scanning companies that look mispriced on fundamentals using the 32 high quality undervalued stocks.
- Strengthen your core holdings by focusing on businesses with cleaner finances through the list of solid balance sheet and fundamentals (24 results).
- Hunt for future leaders before the crowd catches on by filtering for 20 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com