
Does Strong Quarterly Earnings Change The Bull Case For Materion Stock (MTRN)?
- Materion Corporation reported third quarter 2026 sales of US$567.29 million and net income of US$38.33 million. The company also reported higher basic and diluted earnings per share from continuing operations than in the same period a year earlier, alongside stronger nine month results on both revenue and profit.
- The combination of higher sales and earnings over the first nine months of 2026 indicates that Materion is converting demand into improved profitability across its operations.
- This article reviews how Materion's investment narrative aligns with this quarterly net income performance and what that may imply for investors.
Compare Materion's profit momentum with other financially solid industrials by scanning our hand picked list of solid balance sheet and fundamentals (24 results), which may also be turning stronger earnings into durable performance.
Materion Investment Narrative Recap
To own Materion, you need to believe the business can keep turning demand in semiconductors, aerospace and defense into higher value added sales and steadier profitability. The analyst consensus Narrative on Simply Wall St leans on that view and the latest quarter supports it, with higher sales and earnings over both the three and nine month periods.
The short term swing factor is how quickly that record level demand in AI linked chips, defense and space converts from backlog into shipments without pressuring margins. The main near term risk remains exposure to a few large projects and customers. Any pause in orders could matter more for sentiment than this single earnings beat.
The fresh third quarter report is the update that matters most right now. It shows Materion producing US$567.29 million of sales and US$38.33 million of net income, with higher basic and diluted EPS from continuing operations than a year earlier, and stronger nine month figures on both the top and bottom line.
That print fits directly into the existing catalyst story around AI related semiconductor materials, high performance memory and aerospace content. It gives investors current evidence that the margin structure described in the analyst consensus Narrative on Simply Wall St is still visible, while the stated risks on customer concentration and a premium P/E remain firmly in play.
Materion's narrative projects US$3.1b revenue and US$294.9 million earnings by 2029. This implies 11.4% yearly revenue growth and an earnings increase of about US$191.9 million from US$103.0 million today.
Uncover why Materion's fair value indicates a 30% potential upside to its current price that may not last much longer.
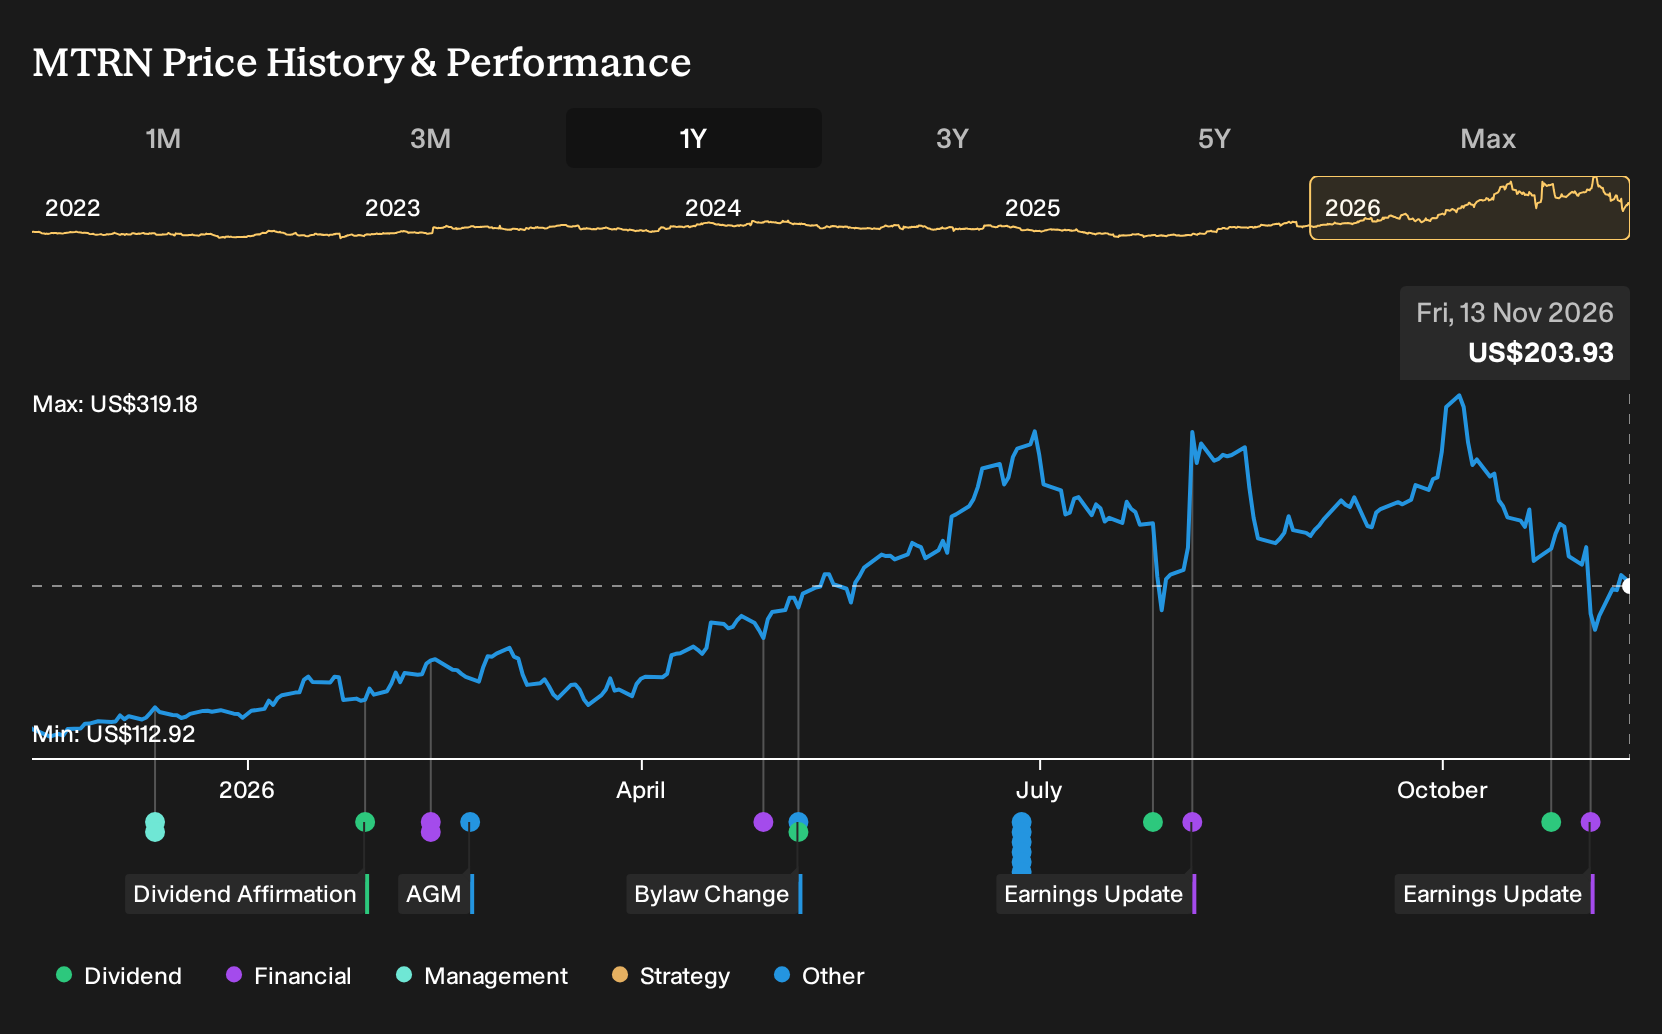
Exploring Other Perspectives
You also need to weigh a more cautious angle around Materion's AI exposure. The lowest analysts saw revenue reaching about US$2.9b and earnings of roughly US$283.3 million by 2029, which already reflected solid progress. This quarter's figures arrived after those forecasts, so their more restrained AI cycle view could shift as new data lands.
Explore 2 other Materion fair value estimates, including one that suggests it could be worth just $264.50!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own research and judgment.
- A great starting point for your Materion research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Materion. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Materion's overall financial health at a glance.
Looking For More Investment Ideas Beyond Materion?
If Materion has sharpened your thinking about earnings quality and balance sheet strength, use that same lens across the wider market with the Simply Wall St Screener. Mix and match filters, tighten your thresholds, and build a watchlist that fits how you like to invest rather than relying on a single story.
- If capital protection comes first, start with companies that pair financial resilience with measured risk profiles by scanning our 31 resilient stocks with low risk scores.
- If you want value with quality, filter for businesses with solid fundamentals that currently trade below many investors' expectations using the 32 high quality undervalued stocks.
- If steady cash returns matter most, focus on companies offering higher yields with an emphasis on payout strength and consistency through the 6 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com