
How Investors May Respond To Fastenal (FAST) Earnings Beat
- Fastenal's latest quarter produced a mixed picture, with earnings above analyst expectations, net sales below estimates yet higher year over year, and management reiterating capital spending and tax rate plans.
- The real story is operational, as Fastenal leans on long term customer contracts, pricing discipline and technology driven inventory tools to sustain momentum despite pressure on margins from larger accounts.
- We will now look at how Fastenal's earnings beat and expense discipline relate to the broader investment narrative investors track.
Scan how Fastenal’s contract driven model compares with other industrials that rely on strong cash flows and disciplined balance sheets using our curated list of solid balance sheet and fundamentals (24 results)
Fastenal Investment Narrative Recap
To own Fastenal, you need to believe the contract heavy, large account model can keep driving steady orders, while technology led inventory tools deepen customer ties. The latest quarter fits that picture. Earnings were ahead of expectations on disciplined expenses, even as net sales fell short of estimates but still grew year over year.
The key near term swing factor is whether Fastenal can keep scaling Fastenal Managed Inventory and on site programs fast enough to offset pressure from big account pricing and input costs. Margin risk from tariffs and cost inflation, flagged in the analyst consensus Narrative on Simply Wall St, does not look resolved by this quarter, but it also was not materially worsened.
One element that connects closely to this update is Fastenal’s capital investment plan for 2026. Management kept the roughly US$320m in net capex intact, or about 3.5% of sales, aimed at hubs, automation, FMI hardware and IT. That decision matters because the business model leans heavily on dense device networks and efficient logistics.
If those investments translate into more volume through digital channels and on site locations, they support the catalysts analysts highlight around higher revenue and potentially more efficient unit economics. The main execution risk is that tariffs, cost inflation or slower industrial activity dilute the payoff from that spend, which would keep pressure on margins even if contract wins and technology usage remain solid.
Fastenal's narrative projects US$11.6b revenue and US$1.9b earnings by 2029. This implies 8.6% yearly revenue growth and about a US$500m earnings increase from US$1.4b today.
Uncover why Fastenal's fair value indicates a 7% potential downside to its current price, which leaves little room for error.
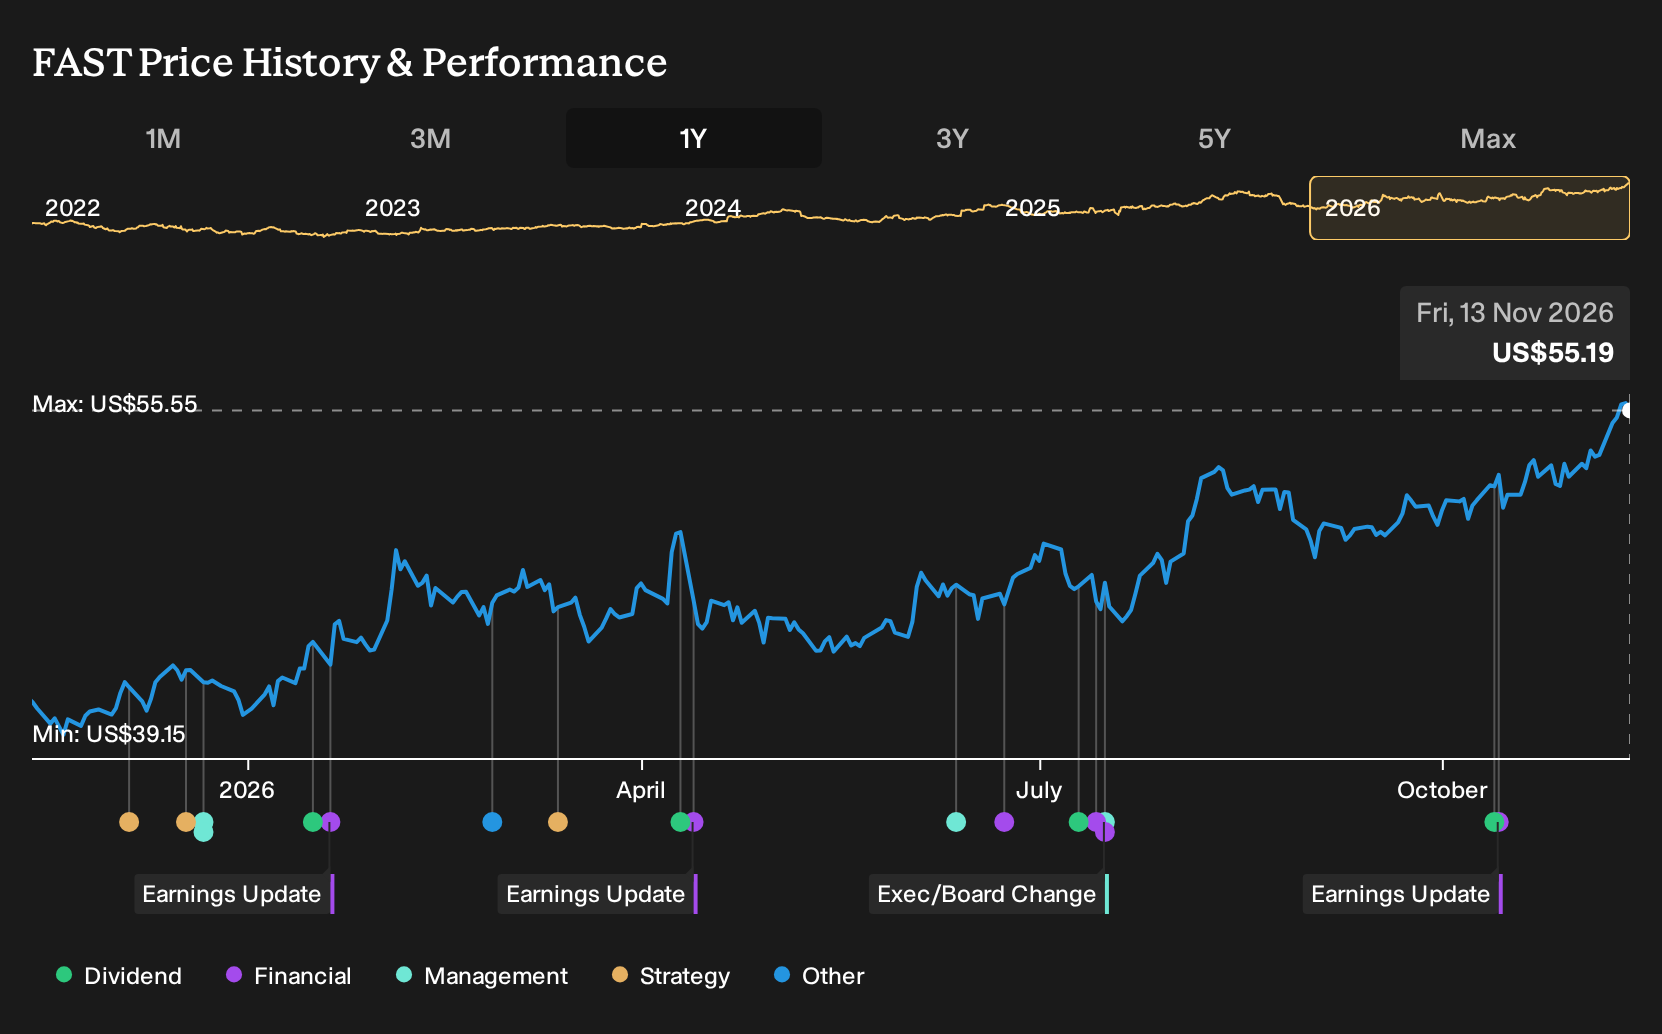
Exploring Other Perspectives
One bullish twist in the Fastenal story is how some analysts framed international expansion as a major upside catalyst. Before this quarter, the most optimistic forecasts were for revenue to reach about US$12.0b and earnings around US$2.0b by 2029. Those projections reflect a far more upbeat view than consensus. You can use this earnings beat as a prompt to revisit those assumptions and compare several competing narratives before deciding what feels realistic to you.
Explore 4 other Fastenal fair value estimates, including one that indicates up to 11% potential upside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis.
- A great starting point for your Fastenal research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Fastenal. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Fastenal's overall financial health at a glance.
Looking For More Ideas Beyond Fastenal?
If this Fastenal update has sharpened your thinking about business quality and valuation, use that same lens across a wider watchlist. The Simply Wall St Screener can help you quickly line up other companies by balance sheet strength, income potential and perceived mispricing so you are not relying on a single story.
- For investors who want resilience first, start with a 31 resilient stocks with low risk scores that score well on stability and lower risk profiles.
- If income is your priority, scan a curated set of 6 dividend fortresses that focus on robust yield with an emphasis on durability.
- To hunt for potential bargains with strong fundamentals, filter through a 20 high quality undiscovered gems that the broader market may be overlooking.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com