
Riskified (RSKD) On Fresh Results And Raised Guidance Looks Fully Valued
Riskified (RSKD) is back in focus after its latest quarterly report, which paired higher third quarter sales with a narrower net loss and another increase to full year guidance for 2026.
Those results have landed after a strong run for Riskified, with the share price up 41.74% over the past 90 days and 92.72% year to date. A 106% 1-year total shareholder return points to momentum that long-term holders, with a 5-year total shareholder return of a 14.25% decline, have not enjoyed to the same extent.
Scan beyond Riskified and size up other AI driven fintech plays focused on fraud prevention with the hand picked 42 profitable AI stocks that aren't just burning cash that already back their story with profits.
Riskified now looks more like a functioning fraud platform business than a turnaround story. After this sharp re‑rating, are you paying a fair price for that progress, or stretching for the promise of more?
Most Popular Narrative: 21% Overvalued
Riskified closed at $9.27, compared with the analyst consensus Narrative on Simply Wall St fair value of $7.65. This points to a market price running ahead of that framework, which is built on detailed revenue and earnings forecasts.
The main thing that has to go right is Riskified lifting its gross margin profile while ramping newer, lower margin merchant cohorts and higher volume categories such as ACH and digital finance, so that revenue growth and operating leverage translate into more durable profitability.
The current valuation implies the share price already incorporates strong execution on revenue, EBITDA and free cash flow guidance despite pressure on gross margins and at least one major broker maintaining a Sell rating. This leaves limited room for disappointment and supports a bearish, overvalued view.
See why 9 investors see Riskified as 21% overvalued.
Result: Fair Value of $7.65 (OVERVALUED)
Still, if ACH and digital finance categories continue to expand while gross margin stays around 46% and non-GAAP profitability improves, this overvalued narrative could look too cautious.
Find out about the key risks to this Riskified narrative.
Another View: Cash Flows Point The Other Way
Analysts on Simply Wall St see Riskified as 21% overvalued at a fair value of $7.65, based on their earnings driven Narrative. A different lens tells a very different story. The SWS DCF model puts future cash flows at $14.06 per share, which means the current $9.27 price screens as undervalued. Which storyline feels more convincing to you?
Our DCF approach leans on long term cash generation rather than near term earnings multiples, so it can highlight opportunity where headline ratios look expensive. If you want to see how that picture is built line by line, Look into how the SWS DCF model arrives at its fair value.
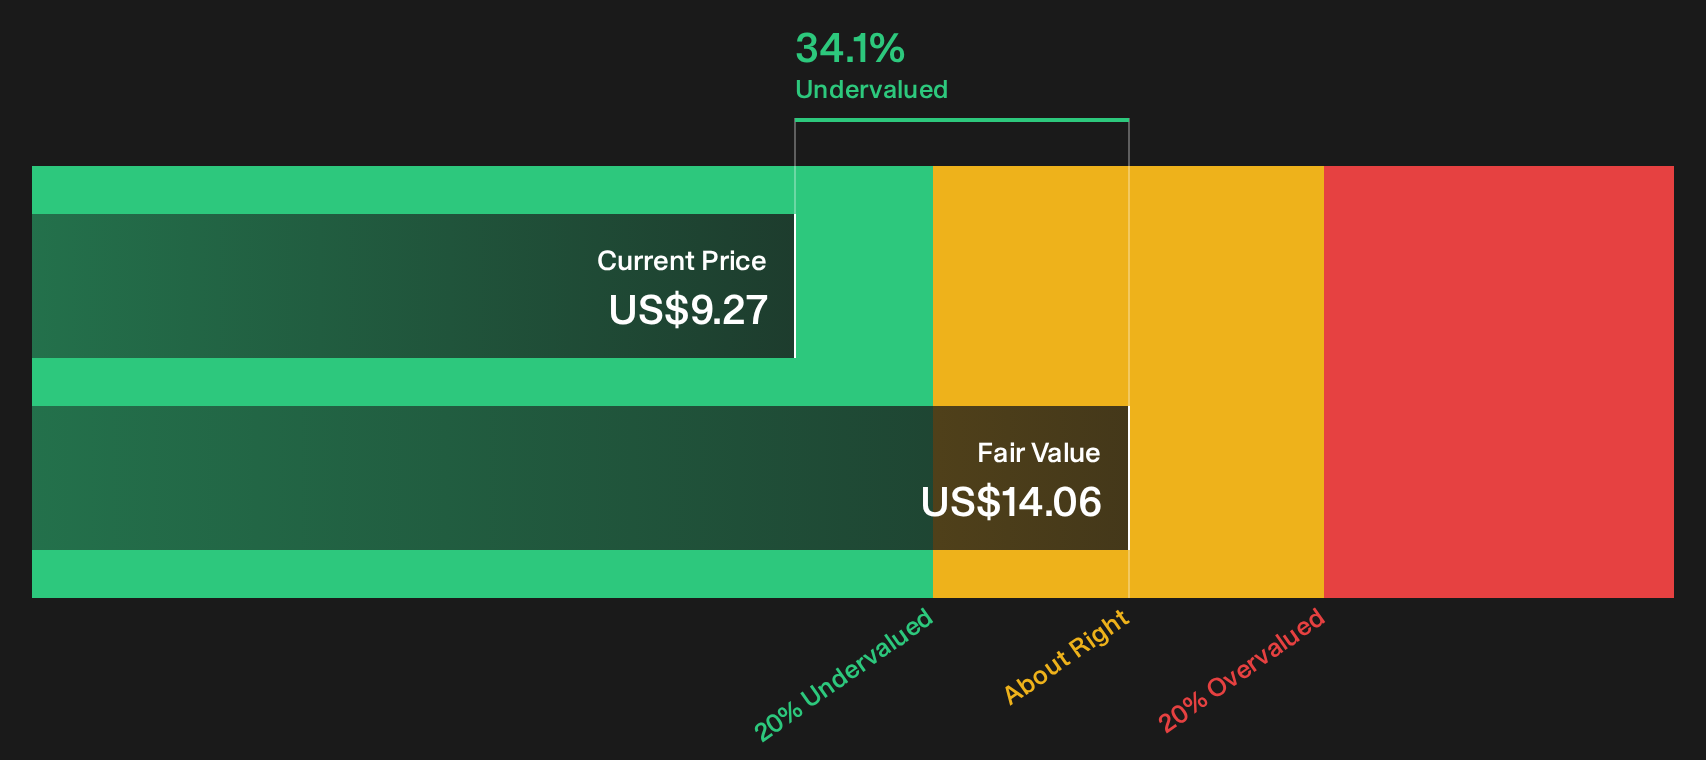
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Riskified for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Risk and reward are both on the table for Riskified. Move quickly past the headlines and weigh the evidence yourself with 3 key rewards and 1 important warning sign.
Ready For More Ideas Beyond Riskified?
Do not stop with one opportunity when a whole menu of different risk and reward profiles is sitting in front of you on the Simply Wall St Screener.
- Target resilient compounding by scanning a 31 resilient stocks with low risk scores that filters for businesses with more stable risk scores and fewer nasty surprises.
- Hunt for mispriced quality through a 20 high quality undiscovered gems that focuses on strong fundamentals the market has not fully embraced yet.
- Anchor your portfolio around strength by using a list of solid balance sheet and fundamentals (24 results) that highlights companies with sturdier finances backing their operations.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com