
What WEG Doubters Overlooked
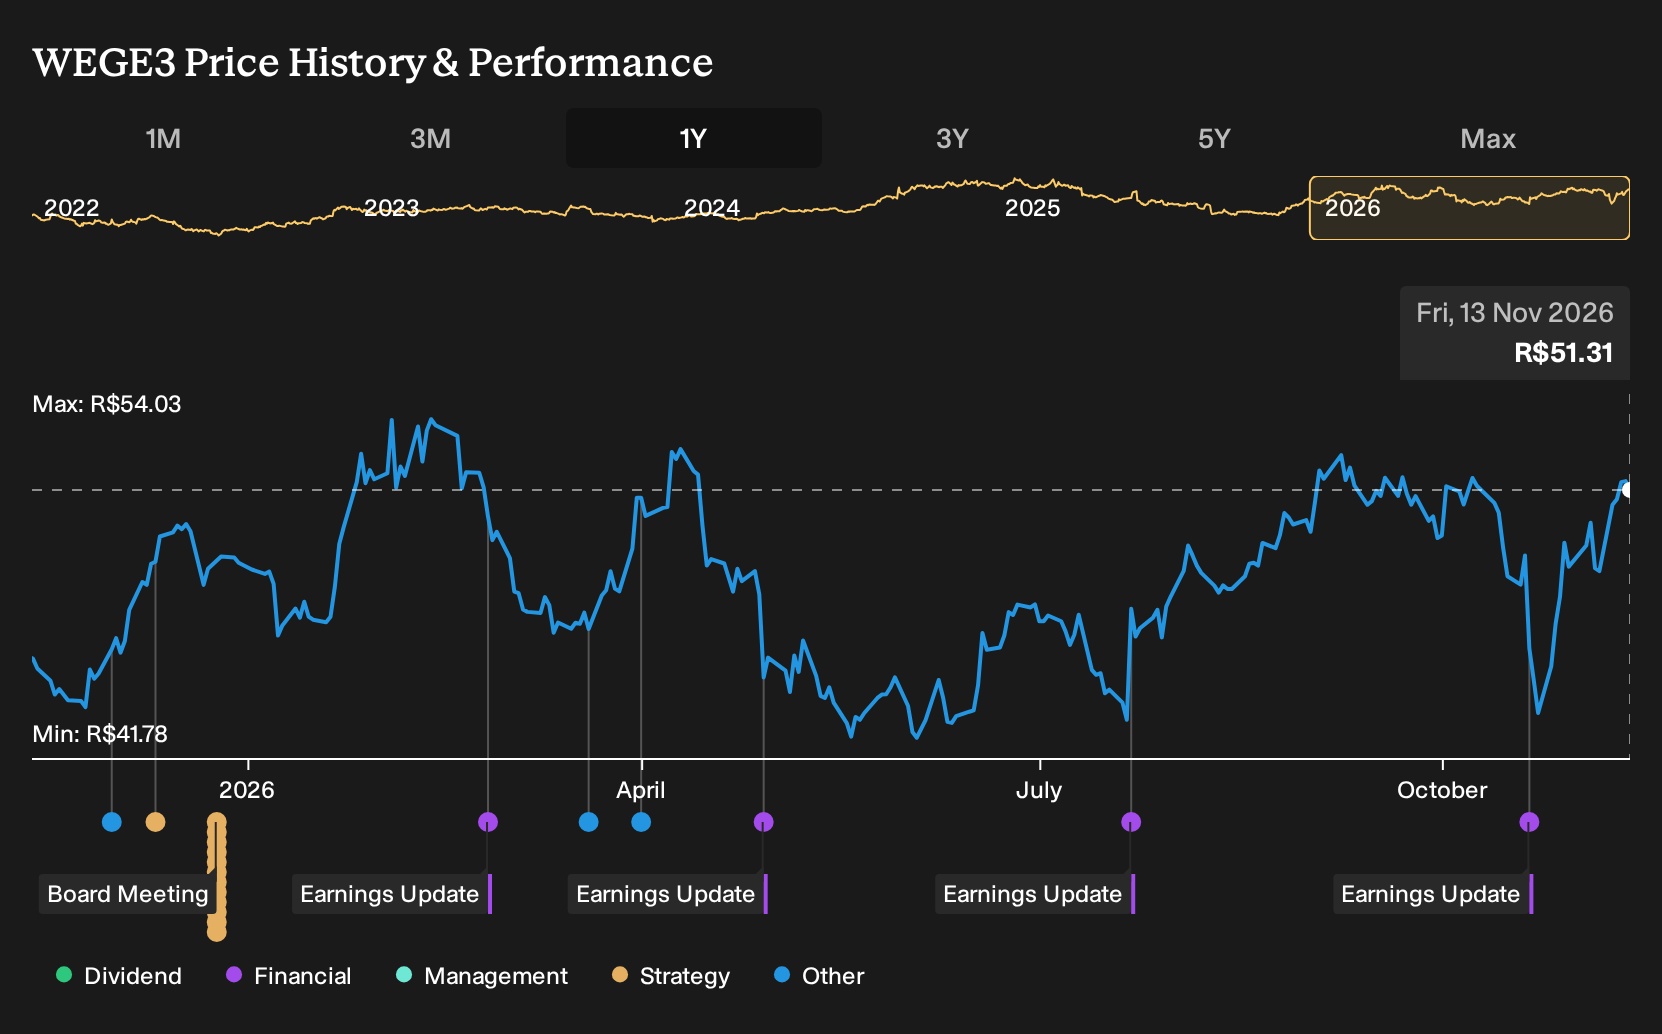
If you only looked at WEG’s latest results, with revenue and profit both higher but net margin slightly thinner, the shareholder outcome might surprise you. Holding WEG over the past year would have returned 20.2%, including dividends. If you had decided on 13 November 2025 to either back the bullish growth story or side with the tariff focused bears, what exactly in the record justified taking that risk?
The easy part of this move is behind WEG. Zero in on 198 high quality undervalued stocks for companies trading below our estimates.
The Two Stories WEG Investors Had To Weigh
WEG shares cost R$44.74 at the start of the period, and you had to choose which story about the future you trusted more without knowing how tariffs or capacity plans would play out.
The bullish narrative saw the stock as fairly valued at around a R$50.82 Fair Value. This represented a price level that could be justified if revenue grew 11.2% a year and margins edged from 15.6% to 15.8% by about 2028.
The bearish view pointed to a R$38.8 Fair Value. It was based on concern that rising tariffs and raw material costs could pressure net margins even if revenue still increased 6.8% annually.
What The WEG Results Actually Tested
The clearest datapoint came from WEG’s Q3 2026 release, where total revenue and net income were both higher than in Q3 2025, yet net margin slipped from 16.1% to 15.3%. That combination supported the growth side of the thesis but challenged the idea that profit quality would keep improving. Overall, the evidence cut both ways.
The useful takeaway is simple. When a story leans on margin strength, you should track net margin alongside revenue and earnings, and compare any optimistic case with that ratio each reporting season.
What WEG's Recent Gain Already Assumes
After rising 20.2% over the past year to R$51.31, WEG now trades above the Fair Value that the bearish analyst Narrative on Simply Wall St assigns to the stock.
That Narrative leans on heavy investment in transformers, generators, BESS and global plants, so you need to judge whether data center, grid and energy transition demand can fully support those assets without margins being squeezed by tariffs and shifting domestic orders.
"Key Takeaways: Bearish analysts expect WEG’s margins and international growth to be squeezed over time as tariffs, FX swings and weaker short‑cycle demand offset the current benefits from long‑cycle projects and capacity expansion. The main thing that has to go right is that WEG converts its heavy investment in transformers, generators, BESS and international plants into sustained, profitable demand from data centers, power grid projects and energy transition customers."
That disagreement has a full argument behind it. → Uncover the lower Fair Value this Narrative argues for
Which Company Could Surprise You Next?
What if your next investment idea came before the headlines? Go straight to the companies whose prices and our estimates still disagree. Three places to start, with the names waiting behind the link.
- Company 1 - 17% below our estimate - targets first-time adopters of tiltrotators within traditional construction equipment fleets.
- Company 2 - 47% below our estimate - develops AI tools that streamline talent discovery, job matching and dynamic ad placement.
- Company 3 - 36% below our estimate - handles AI driven routing, documentation and brokerage tasks for intricate cross-border freight.
That is three of the list. See every one of the 198 solid balance sheet companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com