
How Strong Half Year Earnings Will Impact ORIX (TSE:8591) Investors
- ORIX Corporation reported half year 2026 revenue of JPY 1,673,875 million and net income of JPY 856,218 million, and lifted its interim dividend to JPY 113.56 per share for the period ended September 30, 2026.
- The combination of higher earnings per share and a larger interim dividend indicates that ORIX is currently converting its diversified business model into higher cash returns for shareholders.
- We will now see how ORIX's stronger half year earnings profile could influence the longer term asset light investment narrative.
Scan how ORIX's higher earnings and dividend fit into the broader hunt for resilient income opportunities with our curated 28 dividend fortresses.
ORIX Investment Narrative Recap
For an investor to stay with ORIX, the core belief is that the asset light, fee focused model described in the analyst consensus Narrative on Simply Wall St can keep doing the heavy lifting even as capital gains from asset sales become less central. The latest half year numbers show strong earnings and higher dividends. Yet the most important near term catalyst still looks like steady execution on growing fee income and recycling capital into higher return assets.
The biggest near term risk remains that earnings stay heavily skewed toward disposals or one off gains, especially with high debt and funding mostly from external borrowing. Recent results alone do not remove concerns about forecast profit declines or the exposure to credit losses and impairments in ORIX USA or weaker demand in Greater China linked assets.
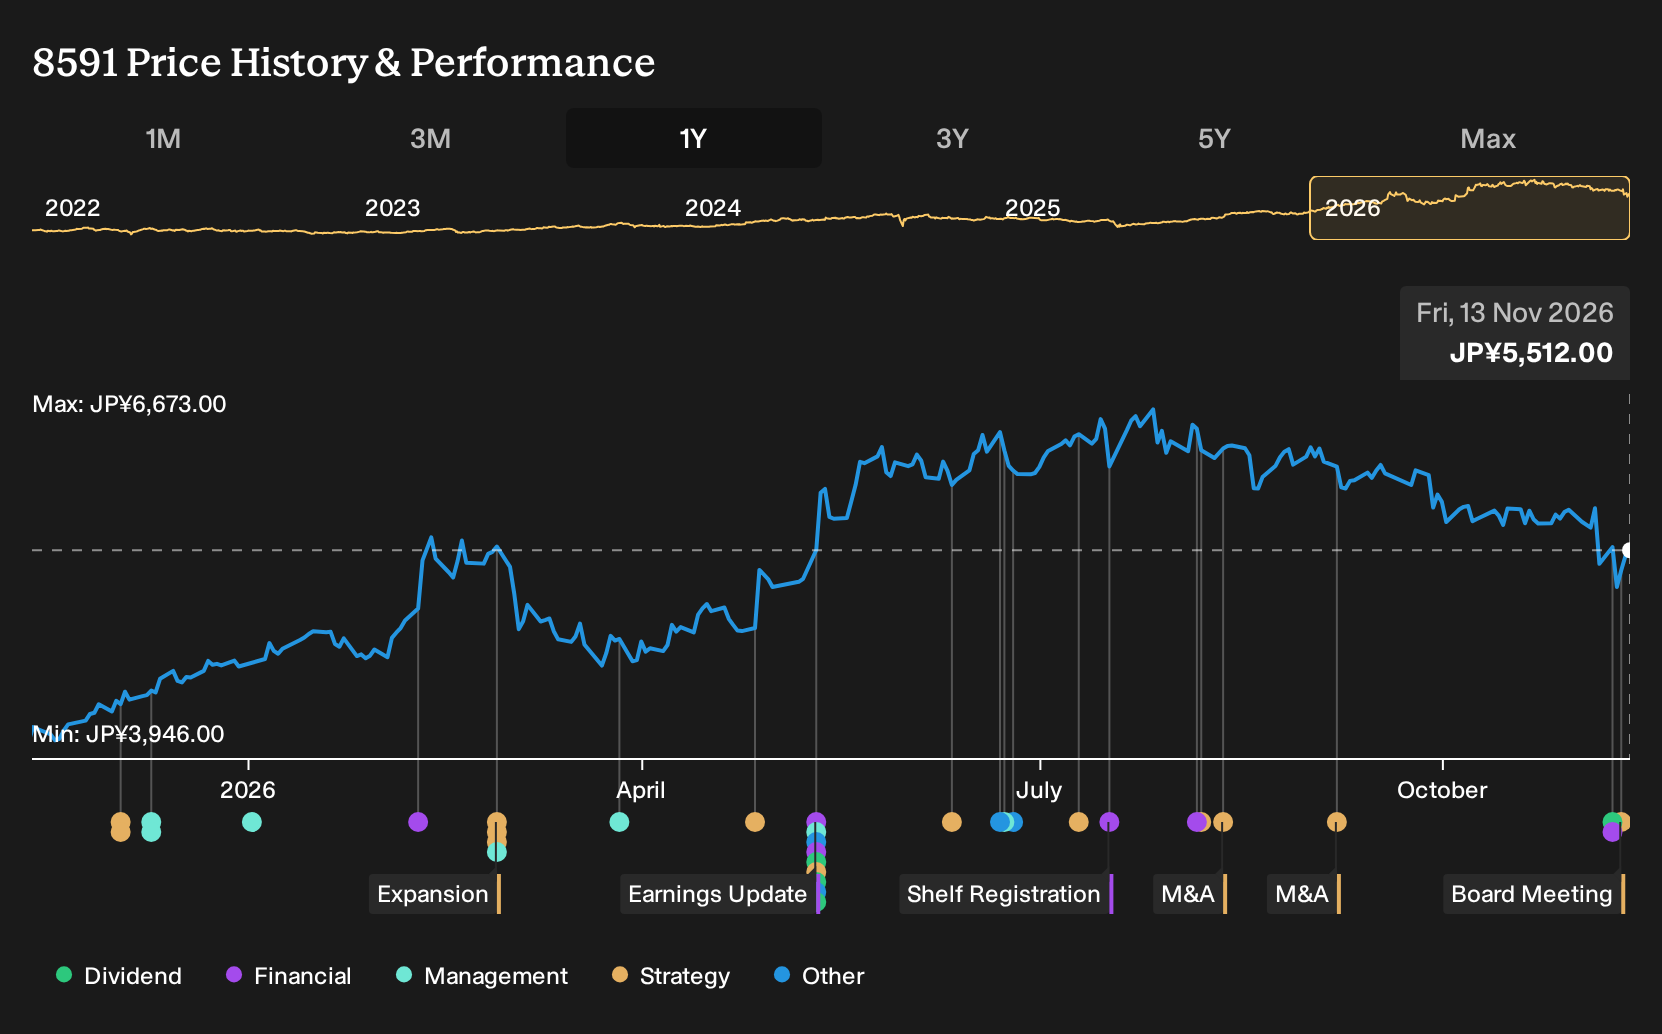
The dividend increase announcement for the six months to September 30, 2026, feels most relevant for this update because it sits right where shareholders feel operational progress, in cash received. ORIX lifted the interim payout to ¥113.56 per share from ¥93.76 a year earlier, while also reporting basic earnings per share of ¥785.16 for the period.
That combination signals that management is comfortable returning more cash even as the analyst consensus Narrative on Simply Wall St still points to forecast earnings declines over the next three years and a dividend that is not well covered by free cash flow. For you as a holder, the operational question is whether fee based income and capital recycling can support this level of shareholder return without leaning too hard on asset sales or extra balance sheet risk.
What ORIX's Forecasts Say About Earnings Power
ORIX's narrative projects ¥3,957.2b revenue and ¥538.6b earnings by 2029. This assumes 4.6% yearly revenue growth and a decrease in earnings of ¥84.5b from ¥623.1b today.
Uncover how ORIX's fair value indicates a 27% potential upside to its current price, which could narrow quickly if sentiment catches up.
Exploring Other Perspectives
One alternate view focuses on ORIX using record profits and higher ROE targets as fuel for a much faster fee income build out. Before this dividend and earnings news, the most optimistic analysts were already pencilling in about ¥4,440.3b of revenue and ¥600.2b of earnings by 2029. You can use this spread in expectations to explore how those forecasts might shift as fresh information, including the higher payout and the IBC tender offer, feeds into different narratives.
Explore 2 other ORIX fair value estimates, including one that suggests up to 148% potential upside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment outcomes rarely come from following the herd, so consider forming your own view.
- A great starting point for your ORIX research is our analysis highlighting 4 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for ORIX. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate ORIX's overall financial health at a glance.
Looking for more investment ideas beyond ORIX?
Once you have a handle on ORIX, it can help to widen the lens and compare it with other opportunities that share some of the qualities you care about most, whether that is income resilience, valuation, or balance sheet strength.
- If you want income that aims for staying power rather than headline yield, scan a curated universe of companies with resilient payouts through the 28 dividend fortresses.
- For investors who care most about paying a sensible price for solid fundamentals, use the screener focused on quality at a discount with the 19 high quality undervalued stocks.
- When capital preservation and financial robustness sit at the top of your checklist, start with businesses that carry stronger balance sheets through the list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com