
Lam Research (LRCX) Draws Fresh Analyst Support, Is The Stock Still A Bargain?
Recent analyst commentary around Lam Research (LRCX) has focused on strong earnings growth, rising earnings estimates, and a new US$25b buyback authorization, a combination that has refocused attention on what investors are paying for the stock.
Over the past few weeks, Lam Research has been hit by a sharp pullback, with the 30‑day share price return down 21.26% and the 90‑day move down 32.03%. At the same time, the 1‑year total shareholder return sits at 53.08% and the 3‑year total shareholder return at roughly 3.3x. This points to longer term momentum still intact despite recent pressure as investors reassess growth potential and risk around AI spending and China exposure.
Scan beyond Lam Research and stress test your AI equipment thesis against a curated list of 53 AI infrastructure stocks that may react just as sharply to shifting capex and sentiment.
Lam Research has moved from a sharp drawdown to a richer earnings story backed by a US$25b buyback. Does that set up a reasonable entry now, or argue for patience and a deeper pullback before committing fresh capital?
Most Popular Narrative: 47% Undervalued
On the latest view, the narrative fair value for Lam Research is $423.85 against a last close of $225.92, which frames the current slide as a valuation gap rather than just short term volatility. According to isidrohg, an investor in the Simply Wall St Community who authored the narrative, the key question is how Lam gets paid across the AI memory buildout.
Lam Research is the position I hold to be right about the AI memory bottleneck without having to be right about how long it lasts.
See why 46 investors see Lam Research as 47% undervalued.
Result: Fair Value of $423.85 (UNDERVALUED)
Still, two pressure points could flip this Lam Research narrative fast: a sudden drop in AI-related capex or stricter China export controls biting into orders.
Find out about the key risks to this Lam Research narrative.
Another View: SWS DCF Flags Less Upside
Lam Research looks attractively priced on earnings at 33.4x P/E, below both the US semiconductor industry on 39.4x and peers on 34.9x. The SWS DCF model tells a different story. On that framework, the stock around $225.92 screens as overvalued versus an estimated future cash flow value of $178.07. Which lens should carry more weight for you: the cash flows or the peer pricing?
To see how that cash flow approach is built and where the sensitivities really sit, take a closer look at the Look into how the SWS DCF model arrives at its fair value..
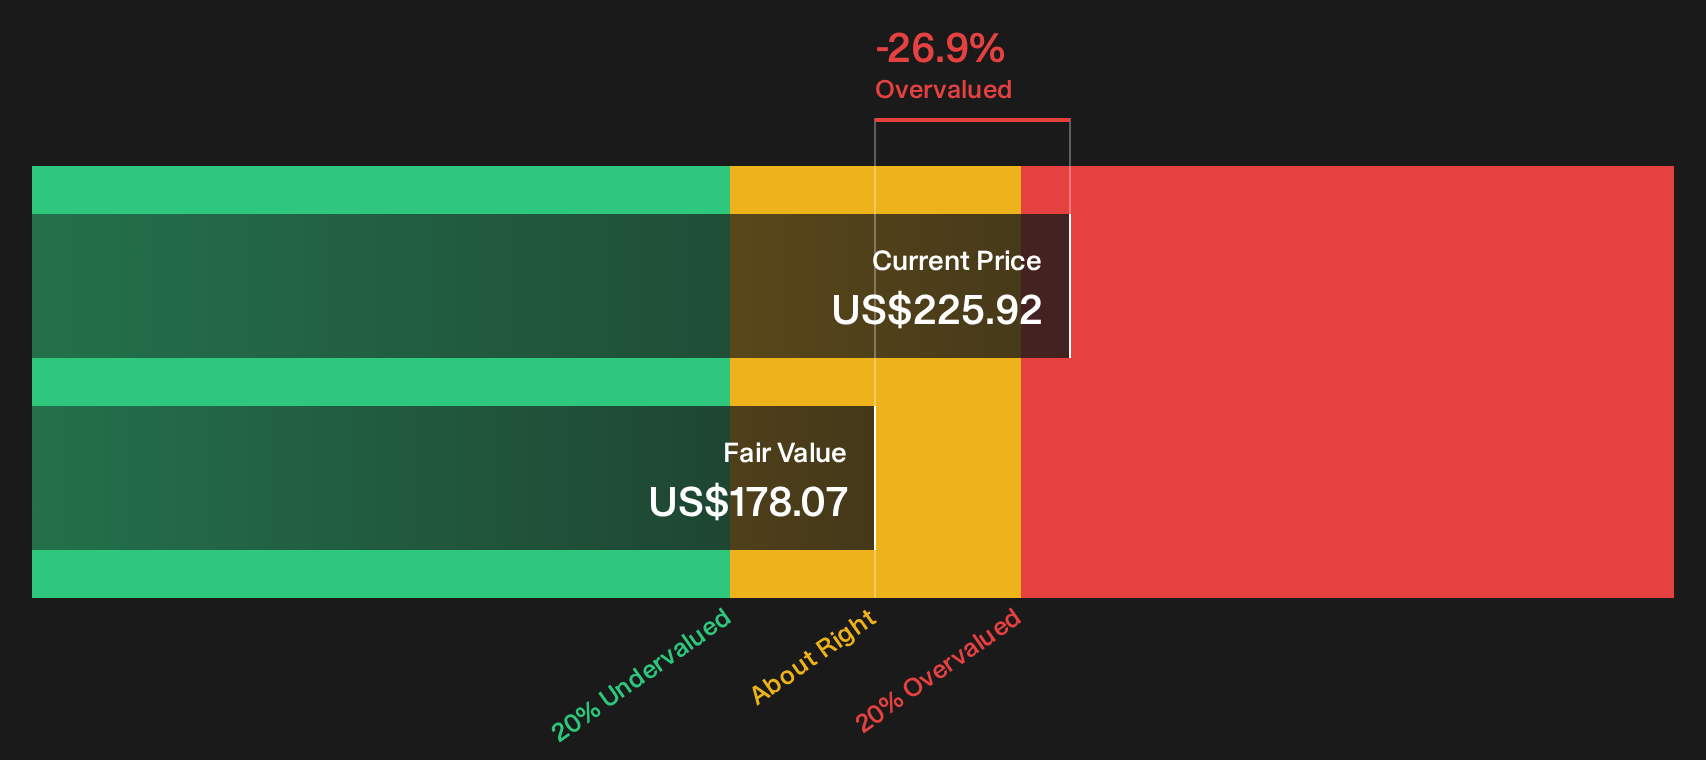
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Lam Research for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment on Lam Research is mixed, with both risks and potential upsides in play. Consider reviewing the data promptly and refining your own thesis using the 4 key rewards and 2 important warning signs.
Hunting For More Investment Ideas Beyond Lam Research?
If Lam Research sharpened your thinking on valuation and risk, do not stop here. Broaden your watchlist with fresh ideas that match your own rules and comfort zone.
- Target potential mispricings by scanning a curated 32 high quality undervalued stocks that combines solid fundamentals with pricing that may not fully reflect their profiles.
- Strengthen your defensive side by reviewing a 31 resilient stocks with low risk scores designed to highlight companies with more resilient risk scores and steadier profiles.
- Spot earlier-stage opportunities by checking a 20 high quality undiscovered gems that filters for quality metrics in stocks that fly under most investors' radar.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com