
How Investors May Respond To Benchmark Electronics Stock As U.S. Production Expands
- Benchmark Electronics announced in early November 2026 that it expanded U.S. production for Oxide Computer Company to support Oxide’s rack scale on premises cloud systems. The company added a second domestic site that increases capacity and supply chain flexibility while keeping engineering collaboration and security tightly linked.
- This deeper role in Oxide’s on premises cloud infrastructure points to Benchmark Electronics leaning further into complex, high value advanced computing programs, where close customer integration and resilient manufacturing are critical operating advantages.
- We will now look at how Benchmark Electronics' broader investment narrative could be influenced by this added U.S. capacity for Oxide.
Scan beyond Benchmark Electronics and line up other advanced computing and infrastructure manufacturers with resilient balance sheets using our curated list of solid balance sheet and fundamentals (24 results) as a comparison set.
Benchmark Electronics Investment Narrative Recap
To own Benchmark Electronics, you need to believe the firm can turn its advanced computing, Semi Cap and medical program ramps into durable manufacturing volume and healthier margins. The analyst consensus Narrative on Simply Wall St leans on earnings growth forecasts and improving cash generation. The Oxide capacity news fits that story, but on its own it does not materially change the near term setup.
The sharper swing factor remains execution. Benchmark Electronics still faces tight component supply, valuation that screens expensive on P/E and a history of uneven free cash flow. Any stumble converting new wins into cash, or any stretch in long lead time parts, is the immediate risk that could matter most.
With no fresh company announcements beyond the Oxide expansion, the most relevant comparison point comes from earlier AC&C momentum. Analysts cite 41% and 71% year over year AC&C revenue gains in Q1 and Q2 2026 tied to clustered AI and on premises cloud programs. Oxide sits in that same lane of complex racks and high touch engineering.
For you as an investor, the operational question is simple. Can Benchmark Electronics keep layering programs like Oxide on top of that AC&C base without breaking schedule, quality or working capital discipline? If those ramps stay on track while management holds P/E rich expectations in check, the existing catalysts have room to keep working.
Benchmark Electronics Forecast Assumptions and Valuation Context
Benchmark Electronics' story in the analyst models is very specific. Forecasts point to revenue of US$3.7b and earnings of US$145.3m by 2029, built on an assumed 9.1% yearly revenue growth rate and an increase in profit margins from 1.9% today to 4.0% in three years. That earnings figure compares with current profit of US$53.1m, which means analysts are effectively underwriting an earnings uplift of about US$92m over the period. For you, the key question is whether the added U.S. Oxide capacity, together with other advanced computing, Semi Cap and medical ramps, can support that level of expansion while the business manages component tightness and working capital without slipping on delivery or quality.
Benchmark Electronics' narrative projects US$3.7b revenue and US$145.3m earnings by 2029. This requires 9.1% yearly revenue growth and an earnings increase of about US$92m from US$53.1m today.
Uncover why Benchmark Electronics' fair value indicates a 36% potential upside to its current price that could narrow quickly.
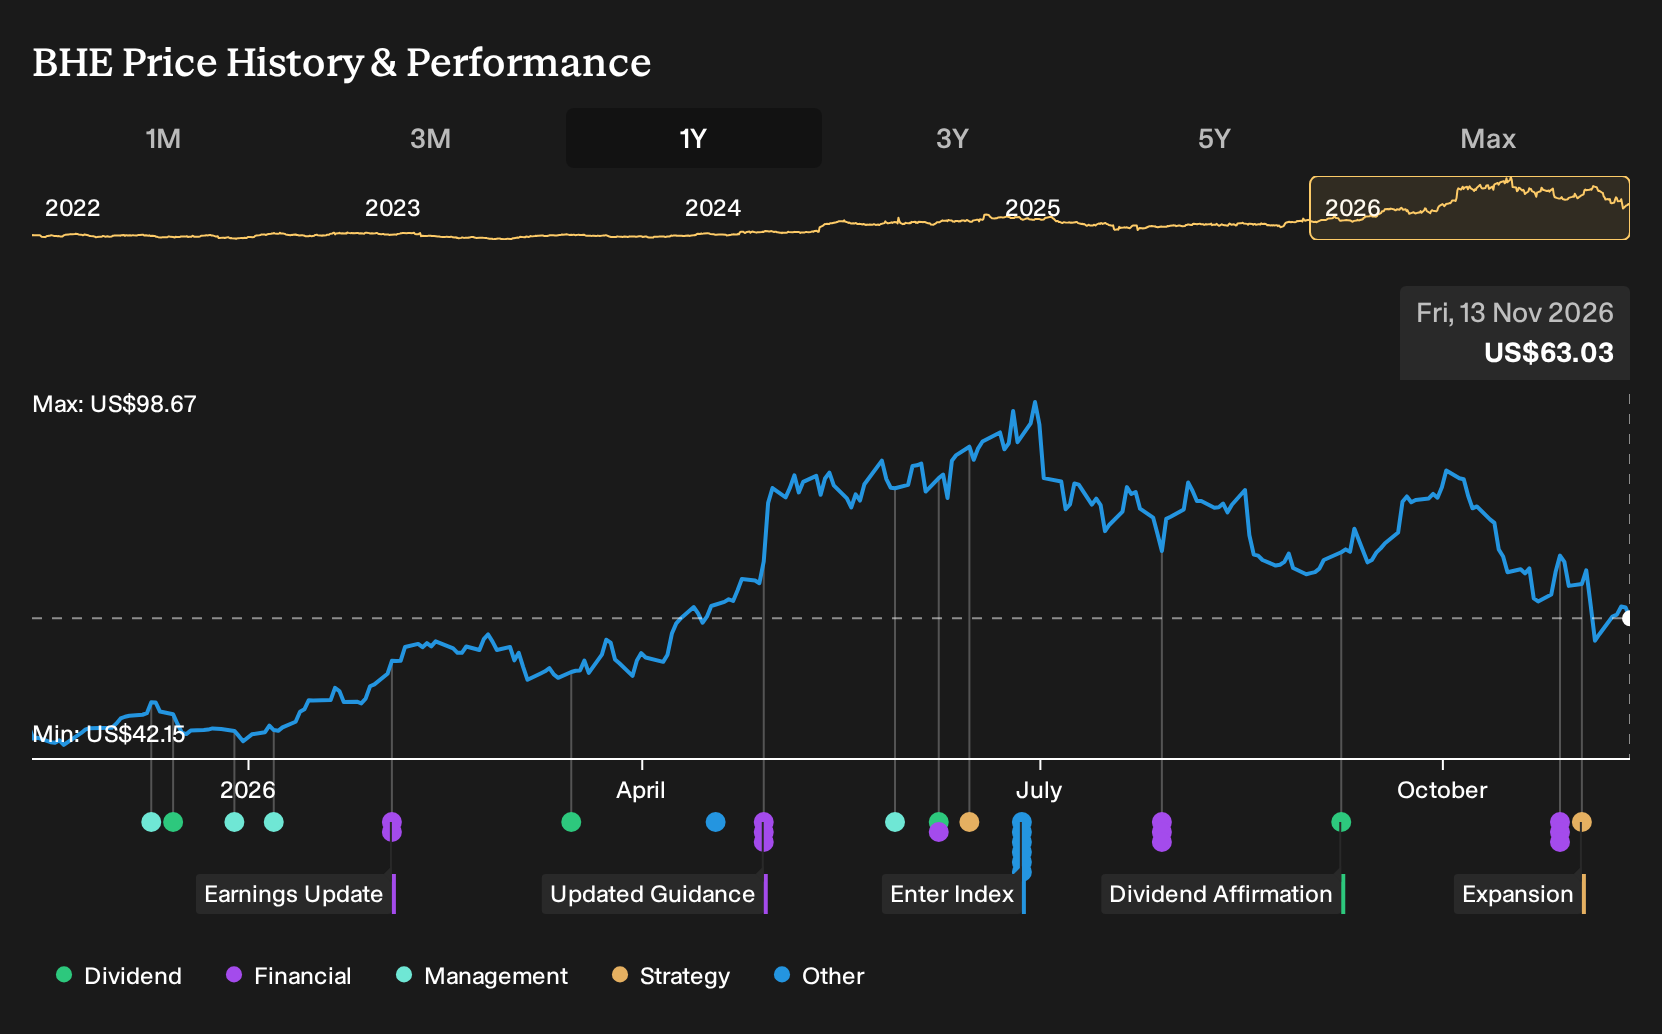
Exploring Other Perspectives
Some analysts frame a very different catalyst around Benchmark Electronics. They focus on record bookings and facility builds and had been modeling revenue of about US$3.8b and earnings near US$120.6m by 2029 even before this Oxide expansion. If that sounds optimistic to you, treat it as one lens and compare several viewpoints.
Explore another Benchmark Electronics fair value estimate, including one that suggests as much as 36% upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own analysis.
- A great starting point for your Benchmark Electronics research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Benchmark Electronics. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Benchmark Electronics' overall financial health at a glance.
Looking For More Investment Ideas Beyond Benchmark Electronics?
If Benchmark Electronics has sharpened your focus on high quality manufacturing and resilient financials, it can help to widen the lens and compare it with other listed businesses. The Simply Wall St Screener offers several targeted ways to build a watchlist that matches your own style and risk tolerance.
- If capital preservation matters most to you, start with steadier profiles by reviewing a set of 31 resilient stocks with low risk scores that may better align with a more cautious approach.
- If you prefer to hunt for potential bargains with strong fundamentals, scan through 32 high quality undervalued stocks and see which companies merit a closer look.
- If you are willing to research earlier stage opportunities with higher risk and potentially higher payoff, sort through 13 elite penny stocks with strong financials and filter for situations that fit your own criteria.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com