
Cibus Real Estate (OM:CIBUS) Is Back In Focus, What Is Catching Investors' Attention?
Cibus Real Estate (OM:CIBUS) has just posted its third quarter 2026 report, giving investors fresh numbers on sales, earnings and profit per share that help clarify how the property portfolio is performing.
Cibus Real Estate’s recent earnings update lands after a mixed stretch in the market, with the share price rising 7.18% over the past month but declining 7.28% year to date. The 3 year total shareholder return of 33.20% contrasts with an 11.47% decline over the past 12 months, pointing to momentum that has cooled compared with earlier gains.
Scan how Cibus Real Estate compares to other property-focused plays with resilient balance sheets by reviewing the hand-picked list of solid balance sheet and fundamentals (198 results) in this segment of the market.
After a sharp month-long rebound but weaker year performance, Cibus Real Estate now asks a simple question of shareholders: Does the current price still leave enough upside to justify the risks you are taking on?
Most Popular Narrative: 10% Undervalued
Cibus Real Estate closed at SEK134.35, while the analyst consensus Narrative on Simply Wall St points to a fair value of SEK149.59 using a 10.46% discount rate, which frames the stock as modestly undervalued based on those long term forecasts.
The strategic focus on necessity-based, grocery-anchored assets ensures defensiveness during economic cycles and leverages demographic trends toward urbanization and stable consumer spending, underpinning occupancy rates and rental stability. Indexation-linked, long-term leases with dominant grocery retailers provide inflation-protected, resilient cash flows and reduce vacancy risk, supporting stable revenue streams and consistent dividend capacity going forward.
See why 24 investors see Cibus Real Estate as 10% undervalued.
On that view, the fair value estimate of SEK149.59 sits above both the current share price and the SEK139.70 analyst price target, which suggests the narrative is factoring in a richer long term earnings multiple than the market is currently applying. That conclusion leans heavily on forecasts for relatively flat revenue, profit margins easing from 41.8% to 36.6%, and earnings of €75.3m in 2029 that are then discounted back at 10.46%.
For you as a shareholder or potential investor, the key question is whether those inputs feel realistic given Cibus Real Estate’s high quality past earnings, leverage profile and concentrated exposure to grocery anchored tenants, or whether you would adjust the margin and required return assumptions before leaning on that SEK149.59 figure.
Result: Fair Value of SEK149.59 (UNDERVALUED)
Still, the narrative around Cibus Real Estate could easily be knocked off course if concentrated grocery tenants weaken or if high leverage bites harder as financing costs shift.
Find out about the key risks to this Cibus Real Estate narrative.
Another View: What The P/E Ratio Says About Cibus Real Estate
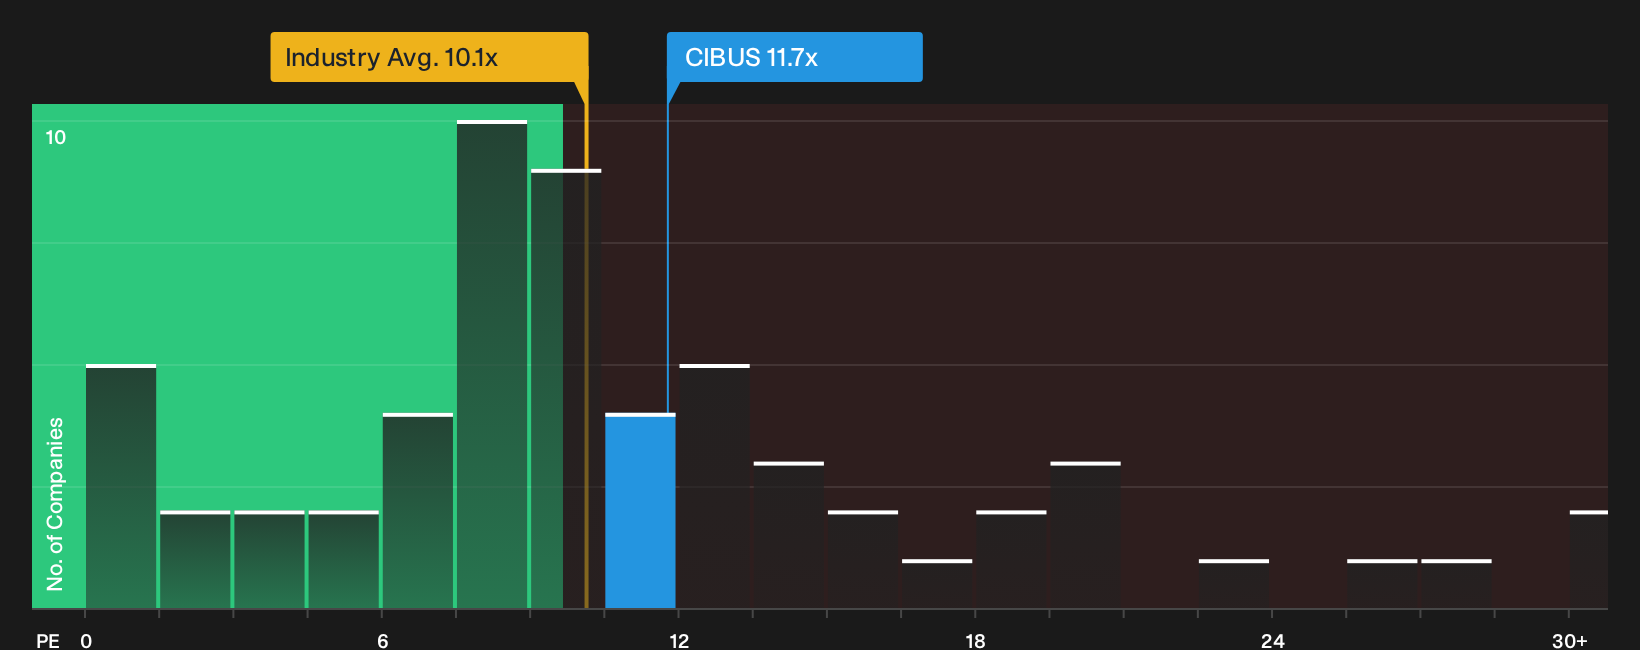
The story shifts once you look at Cibus Real Estate through its P/E ratio. The stock trades on 11.7x earnings, which is higher than the Swedish real estate sector at 10.7x and also above its own fair ratio of 11.4x. That points to only a slim margin for error if earnings soften.
At the same time, Cibus Real Estate still trades below the broader Swedish market on 18.2x and below its peer average of 13x. This hints at more of a middle ground than a clear bargain or clear excess. The question is simple for you as an investor: does a narrow gap between market P/E and fair ratio feel like enough compensation for the balance sheet and earnings risks outlined above, or not?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals run through this Cibus Real Estate story, so treat the next step as a race to your own judgment. Tension between risk and upside is real here, so before leaning on any single metric, weigh both sides using the 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Cibus Real Estate?
If Cibus Real Estate has sharpened your thinking, do not stop here. Broader screening can surface opportunities that fit your risk limits and income goals.
- Hunt for underpriced quality by scanning the 198 high quality undervalued stocks that pairs strong fundamentals with potentially appealing valuations.
- Strengthen your income stream by reviewing the 220 dividend fortresses focused on higher yielding businesses with more robust payouts.
- Prioritise resilience by checking the 210 resilient stocks with low risk scores built around companies with lower risk scores and sturdier profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com