
3 Canadian Dividend Stocks With Yields Over 3%
With the Federal Reserve again stressing that interest rate decisions hinge on sticky inflation, dependable cash income has fresh appeal for investors looking beyond short term price swings. Canadian dividend payers yielding more than 3%, with payouts that are well covered and steadily growing, can help create that reliability. This article walks through three of the strongest dividend candidates from this group and what makes each worth a closer look.
The three stocks highlighted here offer a compelling starting point if you want exposure to dependable cash payouts that focus on well covered, growing and stable dividends. However, if you want the absolute best, these 3 dividend aristocrats stocks are the cream of the crop.
Sun Life Financial (TSX:SLF)
Overview: Sun Life Financial is a global insurance and wealth manager that offers life and health coverage, retirement plans, and fee-based asset management solutions that support consistent dividend payments.
Operations: Sun Life Financial generates most of its revenue in the U.S. at about CA$14.0b and Canada at roughly CA$12.1b, with Sun Life Asset Management contributing around CA$7.1b.
Market Cap: CA$57.7b
Sun Life Financial sits firmly in the Dividend Powerhouses (3%+ Yield) theme because its long-term insurance and asset management franchises generate recurring cash flows that can support a covered, growing payout. This is exactly what the analyst consensus Narrative on Simply Wall St focuses on.
"Expansion and integration of SLC Management into a roughly $400 billion global alternatives platform, together with management equity ownership and plans to generate client cross sell and expense synergies, is aimed at increasing fee based revenue and shifting the earnings mix toward more capital light asset management income.
What ultimately happens to dividend resilience and valuation sensitivity will hinge on how one unresolved pressure in its funding mix plays out.
That funding question is exactly what the full narrative for Sun Life Financial unpacks, separating short term noise from the forces that could accelerate or stall the dividend story for Sun Life Financial.

Magna International (TSX:MG)
Overview: Magna International supplies global automakers with vehicle systems, components, and contract assembly, including ADAS and EV hardware that help fund its dividend.
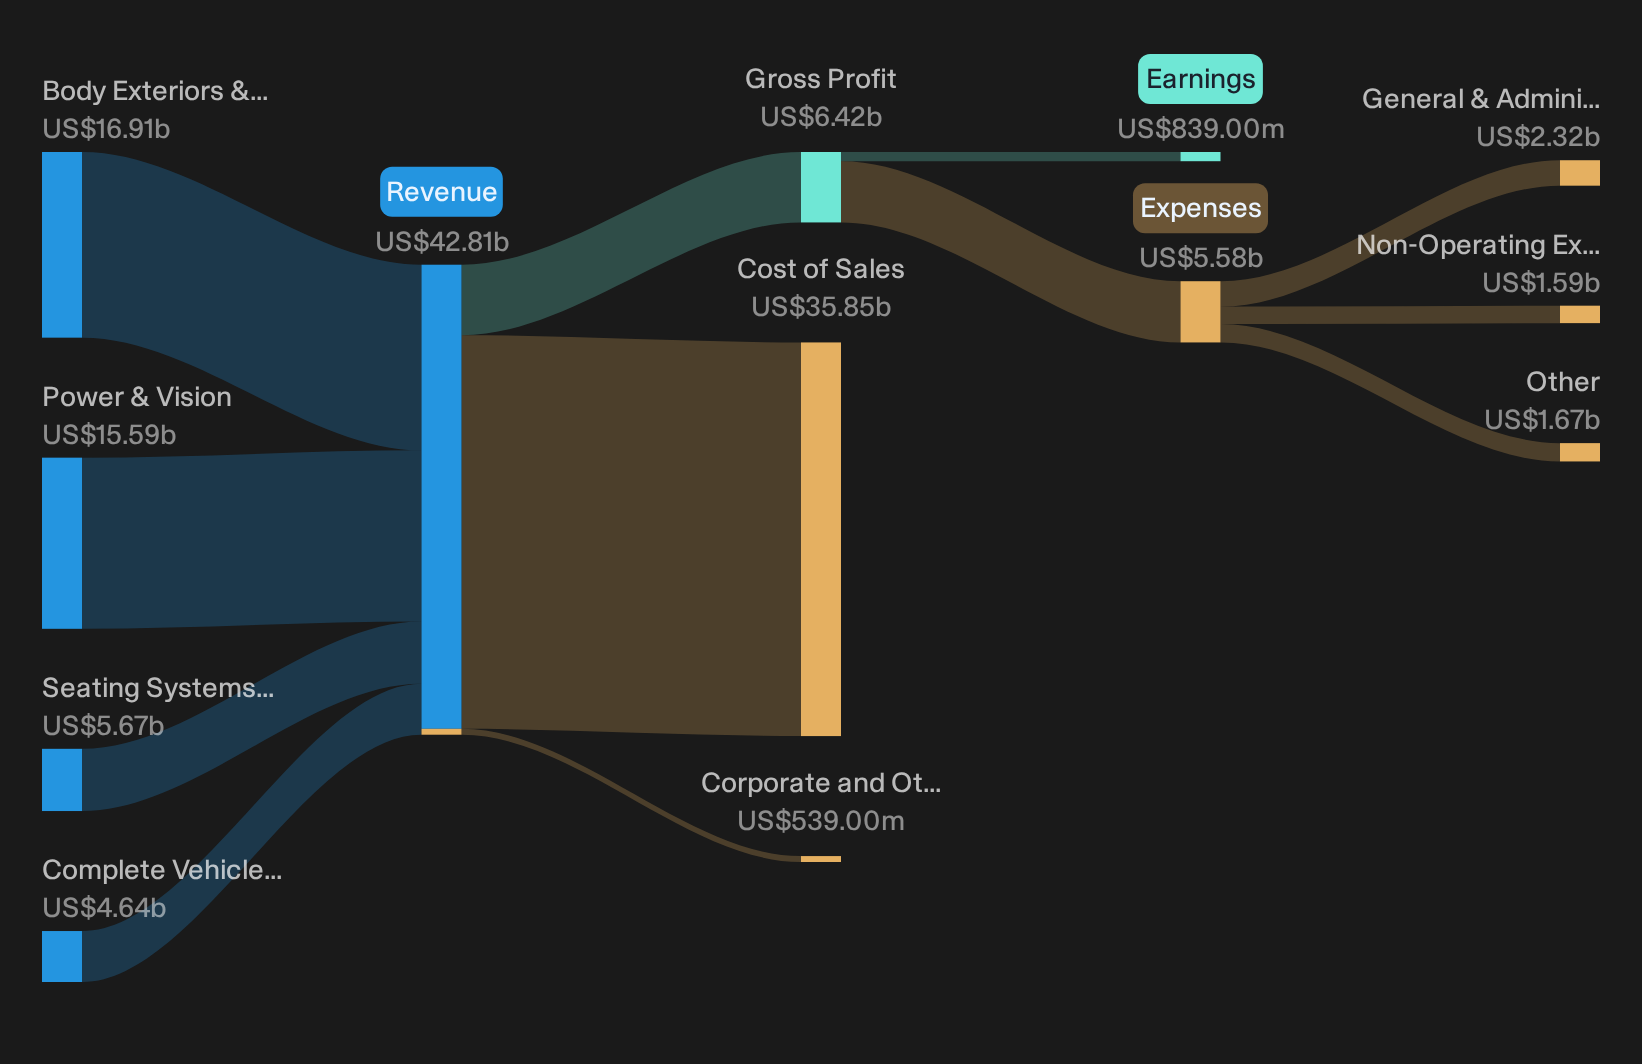
Operations: Magna International generates about US$16.9b from Body Exteriors & Structures, US$15.6b from Power & Vision, US$5.7b from Seating Systems, and US$4.6b from Complete Vehicles.
Market Cap: CA$23.0b
Magna International fits this Dividend Powerhouses theme because its cash-generating auto parts and contract assembly operations, particularly Power & Vision and Complete Vehicles, sit behind a 3.21% yield that analysts in the analyst consensus Narrative on Simply Wall St link to durable free cash flow.
"The company anticipates meaningful improvements in free cash flow as sub 4% capex and greater reuse of EV equipment reduce capital intensity while structurally higher conversion supports the recent US$1.8b full year 2026 free cash flow guidance, which directly feeds into future cash generation and earnings quality."
What eventually happens to Magna International's dividend growth and valuation sensitivity will depend on how one quiet cost and margin assumption plays out.
That margin assumption is exactly what the full narrative for Magna International unpacks, revealing how Magna International's capital intensity, reuse plans, and cash conversion could reshape the payout profile.
Bank of Nova Scotia (TSX:BNS)
Overview: Bank of Nova Scotia is a diversified international bank that uses broad retail, commercial, and wealth operations to support a 3%+ dividend.
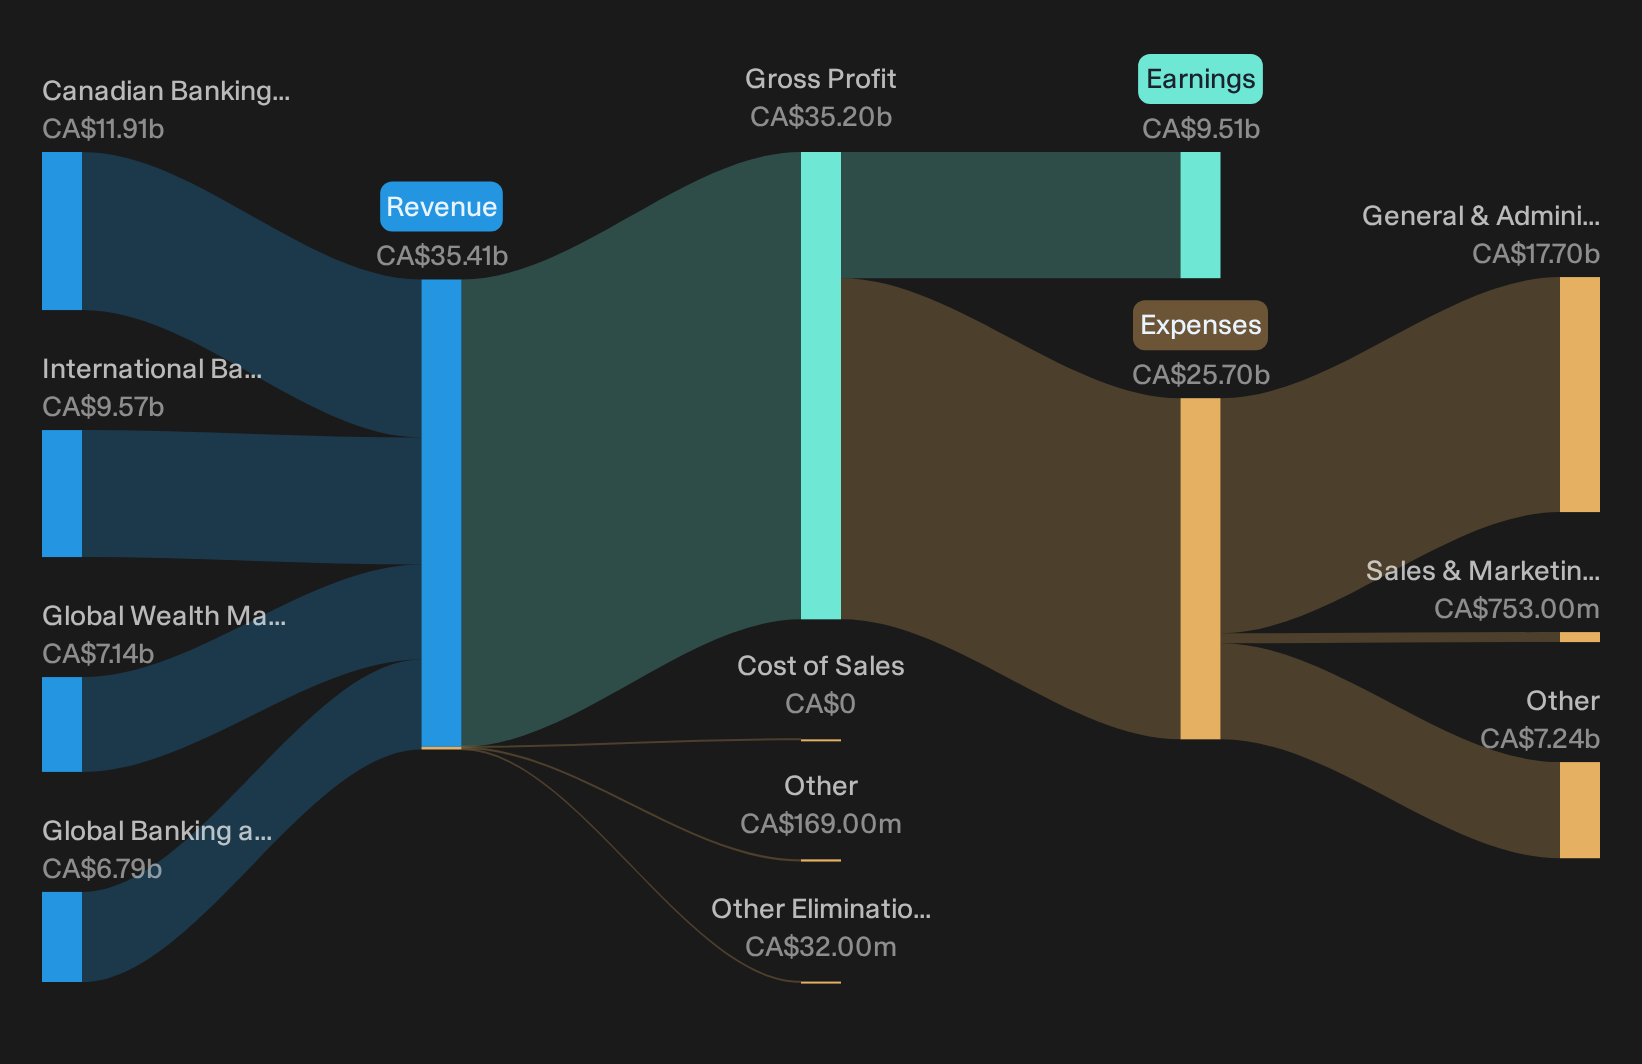
Operations: Bank of Nova Scotia generates about CA$11.9b from Canadian Banking, CA$9.6b from International Banking, CA$7.1b from Global Wealth Management, and CA$6.8b from Global Banking and Markets.
Market Cap: CA$160.9b
Bank of Nova Scotia matters for this Dividend Powerhouses theme because its 3%+ yield rests on diversified earnings from Canadian banking, international franchises, and wealth operations. The analyst consensus Narrative on Simply Wall St links this to recurring cashflow rather than a single profit engine.
"Expansion of banking and wealth management services in Pacific Alliance markets such as Mexico, Peru, Chile and Colombia remains a live driver. International Banking revenue and loan growth in these regions and ROE above 16% point to further potential for fee income and earnings growth as Bank of Nova Scotia continues to deepen client relationships."
What ultimately happens to dividend resilience and the payout trajectory will depend on how one evolving capital and credit trade off plays out.
That trade off is exactly where the full narrative for Bank of Nova Scotia shows how capital pressure, credit risk and Latin American earnings could be quietly reshaping the income story.
Seeking Fresh Alternatives Before They Fly
Fresh ideas often move first. Breakout momentum, adjusting entry points, and under the radar for now stocks can be identified early. Scan these curated lists before the broader market reacts.
- Spot established payouts backed by sturdy finances and steadily compounding potential in a hand picked 3 dividend fortresses before yields change as more buyers participate.
- Track early movers in AI infrastructure as capital flows develop, using the curated 53 AI infrastructure stocks to see which enablers of data centers and networking continue to show momentum.
- Look for under followed quality with strong balance sheets and cash generation through a carefully filtered 9 high quality undiscovered gems before broader institutional attention increases.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com