
Is Ciena (CIEN) Getting Too Expensive For Its Earnings Growth?
Ciena has delivered a striking share price story in recent years, and the scale of that move now puts a spotlight on whether the current valuation lines up with its earnings power. After such a strong run, the core question for you is how much of the business's profit profile is already reflected in today's price.
- Over the past 3 years, Ciena has produced a very large share price gain of about 7x, which raises the stakes on whether its earnings now fully support that kind of re-rating.
- Management expects revenue to grow strongly in the coming years, which can matter a lot for how much investors are willing to pay for each dollar of profit.
- Your read on Ciena is one view; the desks covering it have another. See what analysts think Ciena's shares could be worth.
The issue now is whether Ciena's earnings justify the current share price once you compare its valuation to the Fair Ratio benchmark.
If you are weighing whether Ciena's recent surge already prices in its earnings power, it can help to compare it with a focused list of other technology stocks using the 53 AI infrastructure stocks.
Is Ciena Getting Expensive on Earnings?
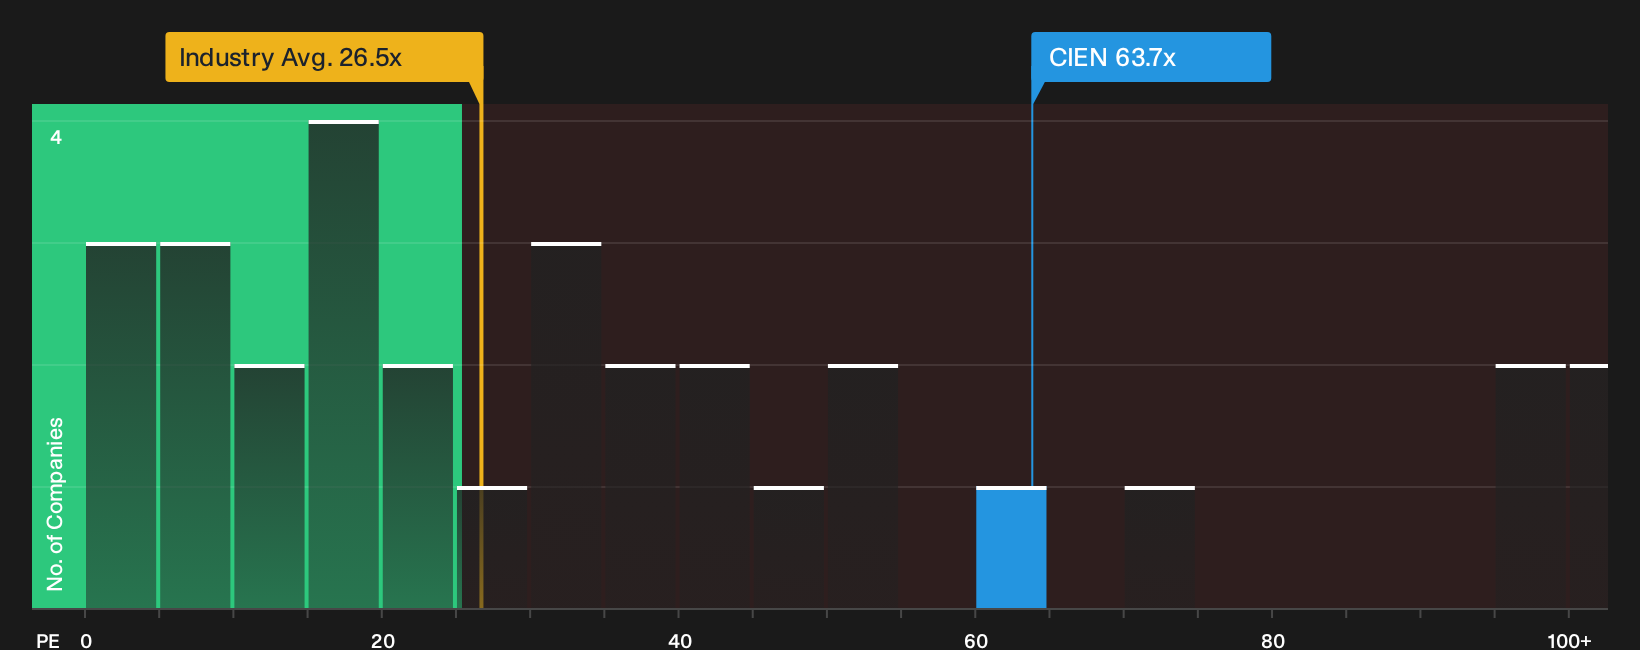
The P/E ratio fits Ciena because earnings sit at the center of how investors are framing its story now. Ciena currently trades on a P/E of 60.8x, which is very close to the peer average of 61.3x and more than double the Communications sector average of 26.5x. That combination suggests the stock is priced in line with specialist peers, but at a significantly higher level than the broader group of listed operators in the same industry.
The Fair Ratio framework, which looks at Ciena's growth profile, margins, size and risk to estimate a more tailored P/E yardstick, points to a lower multiple than where the shares trade now. On this basis, the stock screens as overvalued. Because management is talking about at least 30% revenue growth in fiscal 2027, investors appear willing to keep paying this premium P/E even as it stretches the model's earnings-based benchmark. Explore the numbers behind Ciena's P/E valuation.
The Ciena Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where Ciena's valuation puzzle leaves off by spelling out the specific assumptions on future growth, profitability and earnings that would need to hold for the stock to be worth materially more or less than today, and they sit on the Community page. Each scenario focuses on the drivers behind its fair value estimate rather than a single multiple, so you can track those inputs against Ciena's reported results over time.
One of the top narratives on Ciena: 45% undervalued
This Narrative is the analyst consensus Narrative on Simply Wall St, which compiles analysts' consensus price target and revenue and earnings forecasts, not one person's view.
"The current valuation implies the market is still sceptical that Ciena will achieve its 2029 goals for around $14b of revenue, higher margins and at least 70% of free cash flow returned to shareholders…"
Discover why this Narrative puts Ciena at 45% undervalued.
One more Ciena angle you should not ignore
Valuation only tells part of the story, and the research on Ciena has also surfaced specific risk checks that could change how you weigh everything you have just read. Take a closer look at 2 warning signs before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com