
Keysight Technologies (KEYS) Shares Moved, What Is Driving Attention Today?
Keysight Technologies (KEYS) has been in focus after unveiling new high power test gear, compact XR3 oscilloscopes, and photonic design tools at electronica 2026. These moves are tied directly to AI, EV, and aerospace testing demand.
All this new test gear is landing against a backdrop of choppy trading in Keysight Technologies, with the share price down 16.8% over the past 90 days but still showing a 44.1% year to date share price return and a 66.3% total shareholder return over the past year. This indicates longer term momentum even after the recent pullback.
Scan for other test and measurement players riding the same AI and high power trend as Keysight Technologies by checking out the hand picked 53 AI infrastructure stocks in this space.
After a 16.8% slide over 90 days yet a 66.3% total return over the past year, Keysight Technologies now forces a simple question: Is the bigger opportunity still ahead, or has most of the payoff already shown up in the share price?
Most Popular Narrative: 28% Undervalued
Keysight Technologies closed at $297.68, while the analyst consensus Narrative on Simply Wall St anchors fair value at $415.08. This frames the recent pullback as a discount within that model and places more emphasis on execution relative to multiple expansion.
Expansion of software, simulation and recurring service offerings is advancing, with software and services reaching roughly 33% of Q3 2026 revenue, annual recurring revenue at 24% of mix and the simulation business expected to exceed US$0.5b in 2026. This supports high gross margins near the upper 60s percentage range and contributes to operating margin strength.
See why 22 investors see Keysight Technologies as 28% undervalued.
Result: Fair Value of $415.08 (UNDERVALUED)
Still, the narrative around Keysight Technologies can crack if supply bottlenecks continue to push roughly US$100m of orders out, or if Spirent integration falls short of planned cost synergies.
Find out about the key risks to this Keysight Technologies narrative.
Another View on Keysight Technologies: Rich Multiples, Different Message
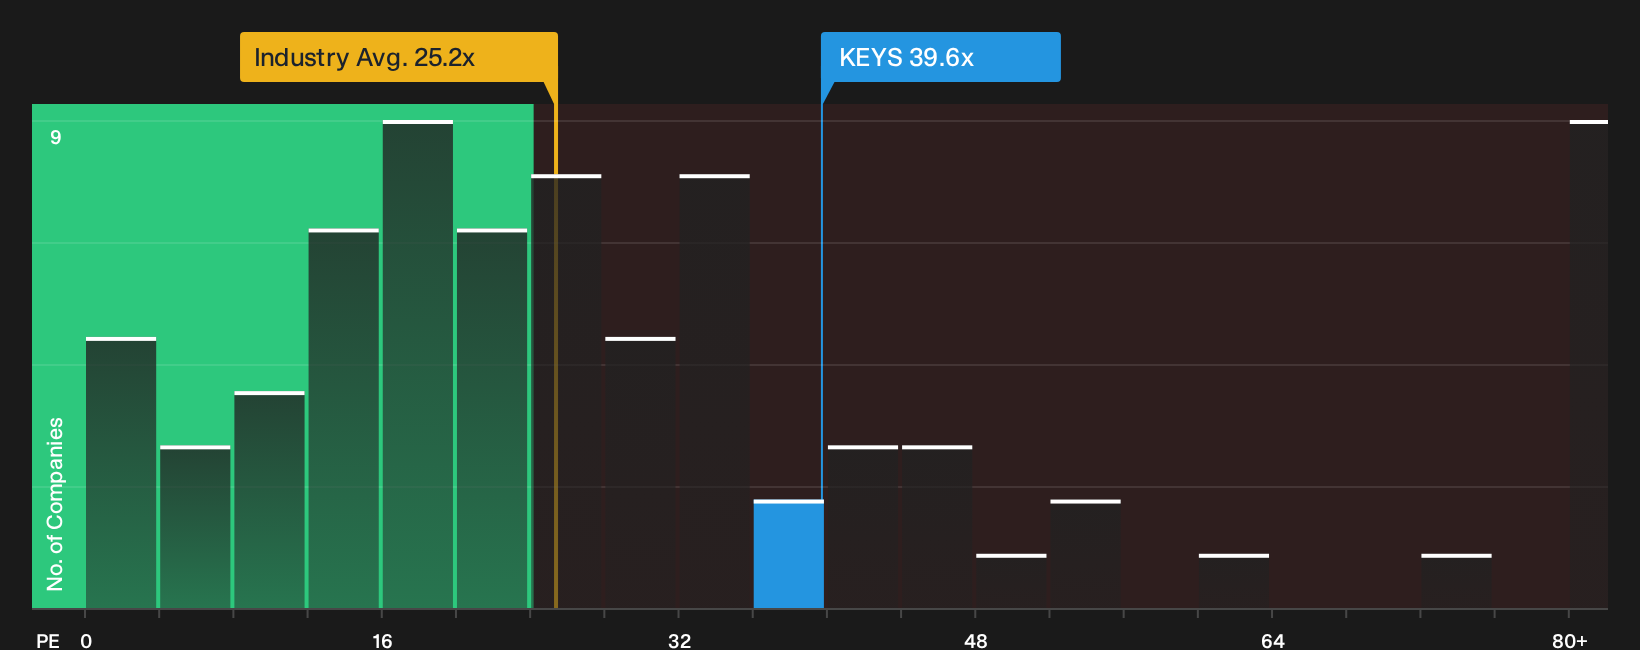
The analyst Narrative and SWS fair value framing point to Keysight Technologies trading at a discount to modeled worth. The simple P/E check tells a different story. At 39.6x earnings, KEYS sits well above the US Electronic industry on 25.2x and ahead of peer averages at 29.9x, while the SWS fair ratio sits at 31.9x.
That gap suggests the market is already paying a premium for Keysight Technologies, which can limit upside if expectations cool or execution wobbles. It leaves a practical question for investors: Is that extra multiple a risk worth accepting, or a signal to demand more of a safety margin first?
For a closer look at how this richer earnings multiple stacks up against what the numbers imply, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals around Keysight Technologies can feel confusing, so move quickly past the headlines and stress test the story against the underlying numbers for yourself. To weigh both the upside potential and the watch points in one place, start with the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Keysight Technologies?
If Keysight Technologies has your attention, do not stop here. Spread your research across other angles so a single story never dominates your watchlist.
- Target long term compounding by scanning a curated pool of financially strong companies through the list of solid balance sheet and fundamentals (24 results).
- Hunt for quality at a discount by reviewing the hand picked 32 high quality undervalued stocks before others reprice them.
- Strengthen your income playbook by checking out dependable payers inside the 6 dividend fortresses while yields still look appealing.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com