
NCR Voyix Stock After Earnings Has The Bull Case Changed?
- NCR Voyix reported Q3 2026 revenue of US$539 million compared with US$677 million a year earlier, while moving from a loss to US$24 million of net income and appointing Darren Wilson as President alongside Brendan Tansill as Executive Vice President and President, Retail and Payments.
- The mix of lower revenue but higher earnings, combined with leadership reshuffles across retail and payments, highlights how NCR Voyix is recalibrating execution, cost discipline and commercial focus within its platform-led model.
- We will examine how NCR Voyix's combination of lower revenue guidance and improved profitability may reshape the investment narrative that investors have been using.
Compare how NCR Voyix's push toward higher profitability at lower revenue stacks up against other payment and retail platform players by scanning our hand picked 32 high quality undervalued stocks.
NCR Voyix Investment Narrative Recap
To own NCR Voyix, you need to believe the shift to a higher mix of recurring, software led revenue can offset pressure in hardware and smaller restaurant customers. The analyst consensus Narrative on Simply Wall St leans on this mix change, along with expanding adjusted EBITDA margins, as the key driver of future earnings power.
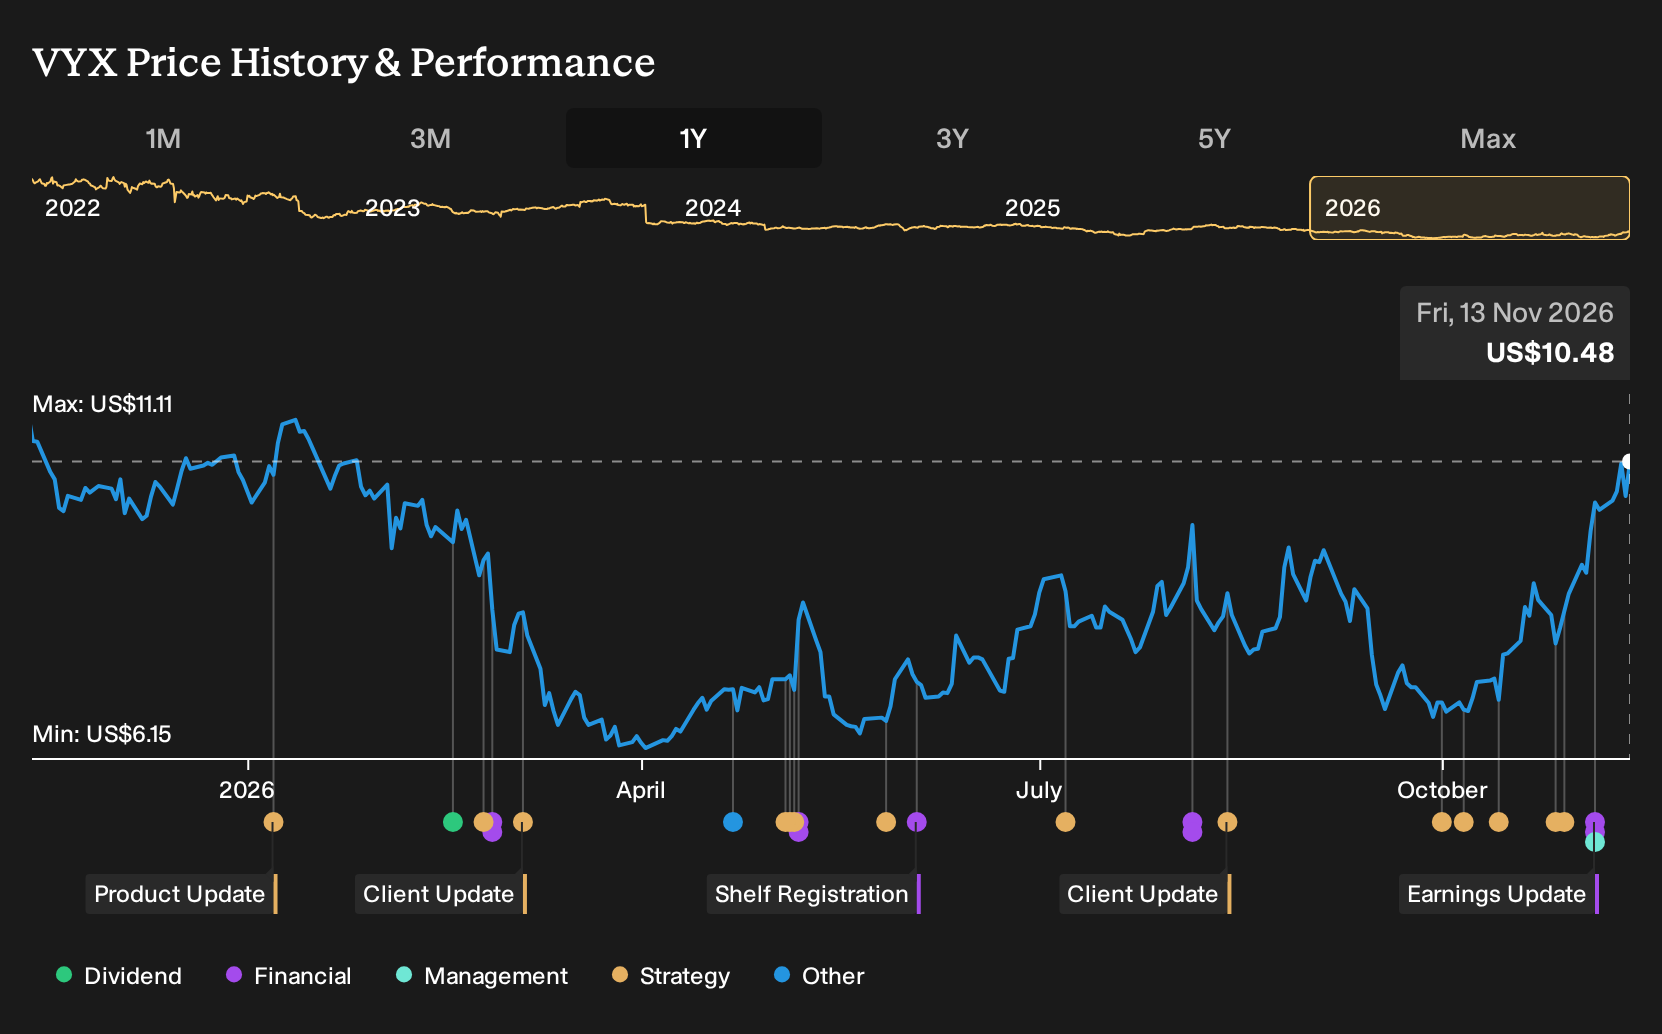
The latest quarter shows that story under real stress. Revenue for Q3 2026 fell to US$539 million while net income moved to US$24 million. The near term catalyst is clear execution on cost control and platform adoption. The biggest risk is continued revenue contraction as hardware projects reset and restaurant SMB weakness drags on.
The most relevant update for that thesis is management guiding full year 2026 revenue to the lower end of US$2,188 million to US$2,303 million. That range sits against nine month revenue of US$1,668 million, so you are effectively being told to expect a smaller top line base while profitability improves.
For catalysts, this tighter outlook puts more weight on Voyager Commerce Platform and Aloha Next scaling fast enough to support earnings even if sales remain under pressure. It also sharpens the main risk already flagged around restaurant SMB softness and slightly lower payment sites, since any further drag could limit how much NCR Voyix can lean on margin expansion alone.
NCR Voyix's narrative projects US$2.1b revenue and US$10.2 million earnings by 2029. This reflects a 4.5% yearly revenue decline and an earnings decrease of US$63.8 million from US$74.0 million today.
Uncover how NCR Voyix's fair value indicates a 26% potential upside to its current price before the discount window narrows.
Exploring Other Perspectives
For the most optimistic analysts, the real catalyst is NCR Voyix using those roughly US$2.5b of divestiture proceeds and about 2x leverage to push harder into software and payments. Before this earnings update, they were pencilling in US$2.1b of revenue and US$31.1 million of earnings by 2029. That is a very different story from the more cautious consensus. The latest guidance cut plus leadership changes could nudge both camps to rethink their assumptions. As a reader, you can treat these wide opinion gaps as an invitation to compare several viewpoints rather than rely on a single narrative.
Explore 3 other NCR Voyix fair value estimates, including one that suggests as much as 29% upside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your NCR Voyix research is our analysis highlighting 5 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for NCR Voyix. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate NCR Voyix's overall financial health at a glance.
Looking For More Investment Ideas Beyond NCR Voyix?
If the NCR Voyix story has sharpened how you think about risk, cash generation and balance sheet strength, use that same lens across the wider market with the Simply Wall St Screener to build a watchlist that actually matches your investing style.
- If capital preservation comes first for you, start with a group of companies screened for resilience and lower risk by checking out 31 resilient stocks with low risk scores.
- If steady income is the priority, focus on businesses offering higher dividend yields and review the 6 dividend fortresses as a hunting ground for potential cash flow ideas.
- If you prefer to back lesser known opportunities with solid fundamentals, cast a wider net across under-followed stocks through the 20 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com