
Earnings And Dividend Might Change The Case For Investing In IGM Financial Stock
- IGM Financial reported third quarter 2026 revenue of C$1,317.12m and net income of C$487.54m, with higher basic and diluted earnings per share from continuing operations compared with the prior year period, and the board declared a C$0.62 per share dividend payable in January 2027.
- The combination of stronger reported earnings across the quarter and year to date, together with an affirmed common share dividend, indicates a business that is translating operating performance into ongoing cash returns for shareholders.
- This article considers how IGM Financial's investment narrative is affected by this reported earnings increase and the confirmed dividend.
Compare IGM Financial's reported earnings strength and confirmed payout with other income focused ideas by scanning our hand picked list of 3 dividend fortresses.
IGM Financial Investment Narrative Recap
To own IGM Financial, you need to be comfortable with a wealth and asset manager that is leaning on fee based advice, affiliates and cost efficiencies, while still facing fee pressure. The analyst consensus narrative on Simply Wall St highlights that the key near term swing factor is whether AI and data investments offset guided fee compression and planned 2026 expense growth.
The third quarter result, with higher revenue and earnings versus a year ago, supports that the current operating plan is translating into profit, so it slightly improves confidence in that catalyst. The biggest risk stays the same. If fee rates and ChinaAMC outflows bite harder, higher expenses could quickly squeeze margins.
The affirmed C$0.62 per share dividend payable in January 2027 is the update that matters most for short term catalysts. It signals the board is keeping capital return steady after a quarter where basic earnings per share from continuing operations were C$2.12 and diluted earnings per share were C$2.10.
For an income focused holder, that payout interacts directly with the narrative of reliable distributions and a business funding AI and affiliate growth from structural savings. The risk is that if fee pressure, ChinaAMC redemptions or rising expenses reduce earnings over time, maintaining this kind of dividend could limit flexibility for reinvestment.
IGM Financial's narrative projects CA$4.6b revenue and CA$1.4b earnings by 2029. This assumes revenue declines by 2.4% per year and implies earnings stay flat relative to current earnings of CA$1.4b.
Uncover why IGM Financial's fair value aligns with its current price.
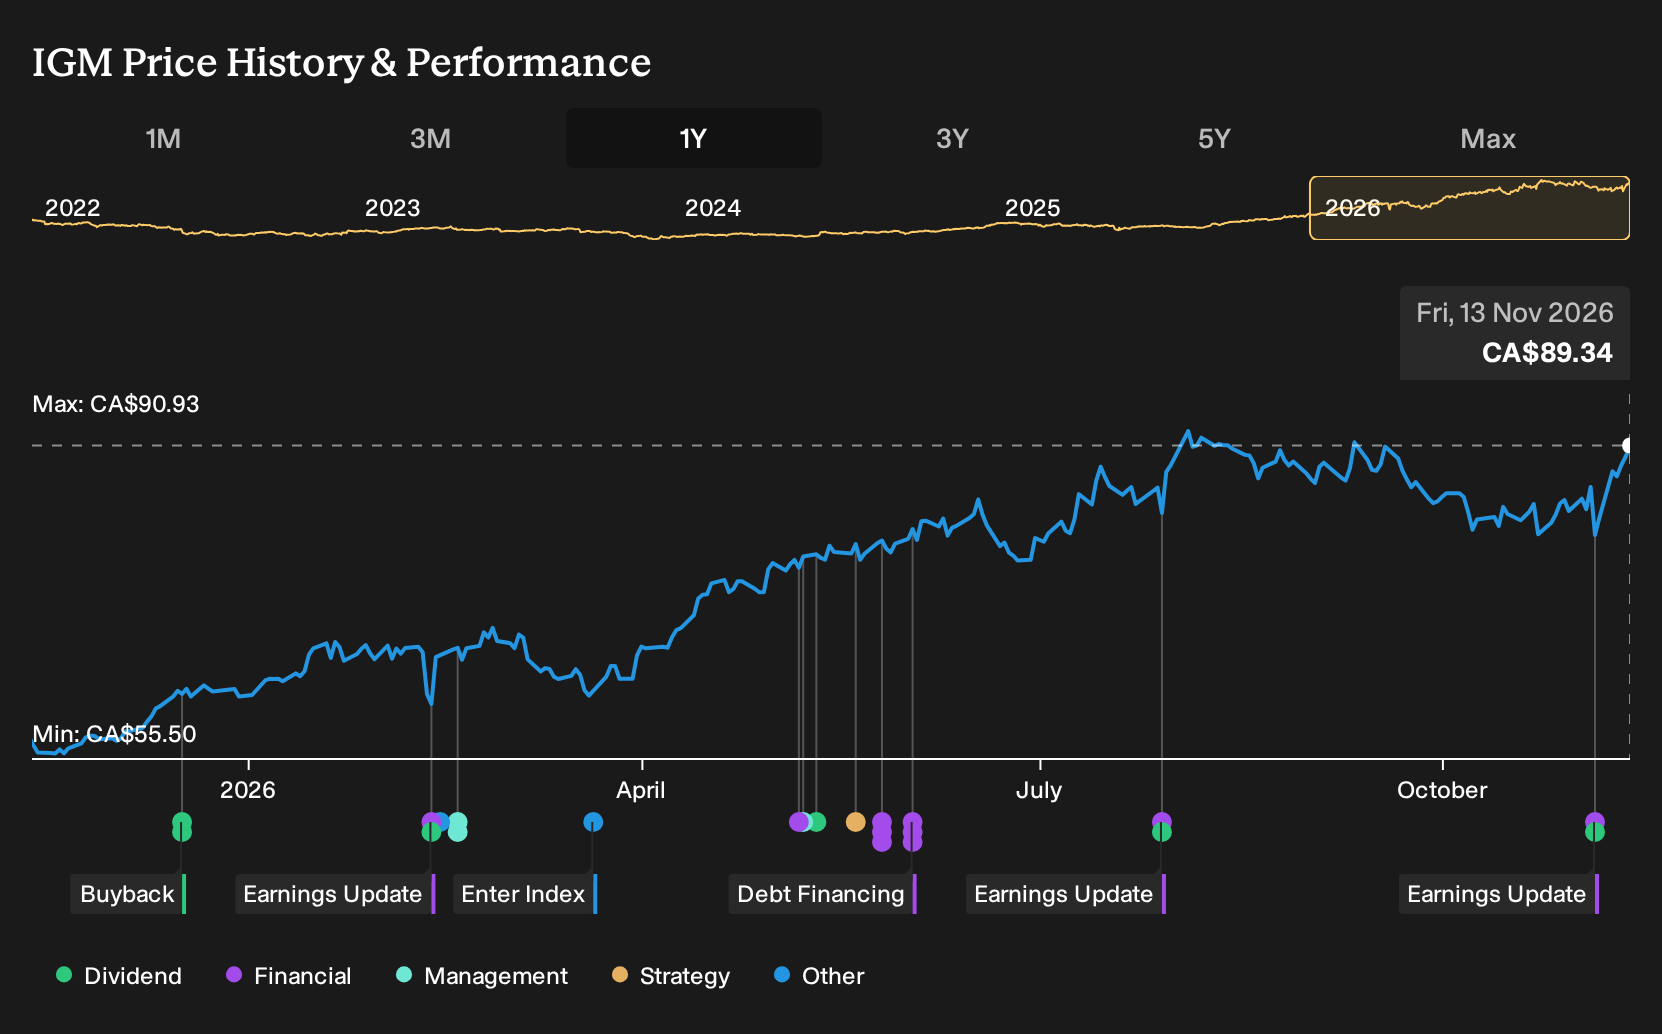
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community cluster tightly between 91.33 and 98.96, so retail investors currently surveyed see IGM Financial in a fairly narrow valuation band. Those views were formed before the latest earnings and dividend affirmation, so you may want to weigh them against fee pressure, ChinaAMC outflow risk and AI driven productivity catalysts before deciding how this fits in your portfolio.
Explore another IGM Financial fair value estimate, including one that suggests up to 11% upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis.
- A great starting point for your IGM Financial research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for IGM Financial. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate IGM Financial's overall financial health at a glance.
Looking for more investment ideas beyond IGM Financial?
If the IGM Financial story has sharpened your thinking on dividends, valuation and risk, use that same lens across the wider market with the Simply Wall St Screener.
- For investors who want income without ignoring balance sheet strength, review a curated 3 dividend fortresses that combine yield with resilience.
- If capital preservation sits high on your priority list, start with a 9 resilient stocks with low risk scores that score well on fundamentals and volatility.
- When you are hunting for the next potential outlier before it hits mainstream screens, scan a 9 high quality undiscovered gems built around quality, not hype.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com